

GE To Sell U.S. Online Deposit Platform To Goldman Sachs Bank USA
FAIRFIELD, Conn. – GE (NYSE:GE) announced today an agreement to sell GE Capital Bank’s U.S. online deposit platform along with all deposits of GE Capital Bank, including online savings accounts, online CDs and brokered CDs, to Goldman Sachs Bank USA (“GS Bank”). Under this agreement approximately $16 billion of deposits will be transferred to GS Bank. The sale relates only to the deposit platform and deposits of GE Capital Bank.
“As we work to reduce the size and complexity of GE Capital, this transaction is another key step. It advances GE Capital’s new strategic direction by facilitating closure of one of our two U.S. bank charters, which we believe will help us become less systemically important,” said Keith Sherin, GE Capital chairman and CEO. “I am confident that under GS Bank our deposit customers will continue to receive the high level of service and commitment they have come to expect,” he added.
The transaction is subject to regulatory approval and includes management, employees, software, and technology used to operate the platform. Scott Roberts, president of GE Capital Bank, is expected to join GS Bank to oversee the platform.
GE Capital Bank is a Utah-chartered industrial bank. GE expects to wind down the remaining operations of GE Capital Bank following closing of the transaction, subject to regulatory approval.
Synchrony Financial, the U.S. consumer financial services business majority owned by GE Capital, also takes retail deposits at Synchrony Bank. Synchrony Financial is targeted to be split off in a share exchange later this year, subject to regulatory approval.
Sherin said, “Coupled with the split off of Synchrony Financial, this transaction will facilitate our complete exit from U.S. banking operations, eliminate the exposure of the U.S. deposit insurance safety net to GE Capital and thereby significantly reduce our regulatory footprint in the United States as we work to pair a smaller GE Capital with GE’s long-term industrial growth.”
As previously announced, GE is embarking on a strategy to create a simpler, more valuable company by reducing the size of its financial businesses through the sale of most GE Capital assets and by focusing on continued investment and growth in its world-class industrial businesses. GE and its Board of Directors have determined that current market conditions are favorable to pursue these dispositions. GE will retain the financing businesses that relate directly to GE’s industrial businesses.
About GE
GE (NYSE:GE) imagines things others don’t, builds things others can’t and delivers outcomes that make the world work better. GE brings together the physical and digital worlds in ways no other company can. In its labs and factories and on the ground with customers, GE is inventing the next industrial era to move, power, build and cure the world. www.ge.com.
GE’s Investor Relations website at www.ge.com/investor and our corporate blog at www.gereports.com, as well as GE’s Facebook page and Twitter accounts, including @GE_Reports, contain a significant amount of information about GE, including financial and other information for investors. GE encourages investors to visit these websites from time to time, as information is updated and new information is posted.
Fannie Mae Announces Third Credit Risk Sharing Transaction with Reinsurance Industry
WASHINGTON, DC – Fannie Mae (FNMA/OTC) announced today that it is continuing efforts to reduce taxpayer risk by increasing the role of private capital in the mortgage market and has completed its latest credit risk sharing transaction. The Credit Insurance Risk Transfer (CIRT™) transaction shifts credit risk on a pool of loans to a panel of reinsurers. For the first time since the CIRT program’s inception in 2014, an international reinsurer participated in this type of Fannie Mae risk sharing transaction.
“Through CIRT, we remain focused on finding new ways to build liquidity and move credit risk away from Fannie Mae. In this transaction we attracted new global capital, providing opportunities for reinsurers to gain exposure to the U.S. housing market,” said Rob Schaefer, vice president for credit enhancement strategy & management. “We’ve focused on educating reinsurers on our company’s strategic approach to managing credit risk and to explore opportunities to work together. We want to continue to lead this space and grow the CIRT program as a repeatable, frequent structure, and increase the number of reinsurers we work with on these deals. We look forward to bringing similar transactions to market in the future.”
In this transaction, CIRT-2015-2 which became effective July 1, 2015, Fannie Mae retains risk for the first 50 basis points of loss on an $8.1 billion pool of loans. If this $40.5 million retention layer were exhausted, reinsurers would cover the next 250 basis points of loss on the pool, up to a maximum coverage of approximately $202.5 million. Coverage is provided based upon actual losses for a term of 10 years. Depending upon the pay down of the insured pool and the amount of insured loans that become seriously delinquent, the aggregate coverage amount may be reduced at the 3-year anniversary and each anniversary of the effective date thereafter. The coverage may be canceled by Fannie Mae at any time after the 5-year anniversary of the effective date by paying a cancellation fee.
The reference loan pool for the transaction consists of 30-year fixed rate loans with loan-to-value (LTV) ratios greater than 60 percent and less than or equal to 80 percent. The loans were acquired by Fannie Mae from April through August of 2014.
In addition to the CIRT program, Fannie Mae continues to reduce risk to taxpayers through its flagship Connecticut Avenue Securities (CAS) program and other forms of risk transfer. Through both CIRT and CAS, Fannie Mae has sold a portion of the credit risk on approximately 60 percent of recent acquisitions and on approximately $400 billion of loans in recent years. These transactions are structured so that if the covered loans experienced the same stress as the most recent housing crisis, Fannie Mae’s projected losses would be limited to the small first-loss piece of credit risk retained by the company.
Securities and Exchanges Commission Charges Bank of New York Mellon With FCPA Violations
Washington D.C., — The Securities and Exchange Commission today announced that BNY Mellon has agreed to pay $14.8 million to settle charges that it violated the Foreign Corrupt Practices Act (FCPA) by providing valuable student internships to family members of foreign government officials affiliated with a Middle Eastern sovereign wealth fund.
An SEC investigation found that BNY Mellon did not evaluate or hire the family members through its existing, highly competitive internship programs that have stringent hiring standards and require a minimum grade point average and multiple interviews. The family members did not meet the rigorous criteria yet were hired with the knowledge and approval of senior BNY Mellon employees in order to corruptly influence foreign officials and win or retain contracts to manage and service the assets of the sovereign wealth fund.
According to the SEC’s order instituting a settled administrative proceeding, the sovereign wealth fund officials requested that BNY Mellon provide their family members with internships, and they made numerous follow-up requests about the status, timing, and other details of the internships for their relatives. BNY Mellon employees viewed the internships as important to keep the sovereign wealth fund’s business.
“The FCPA prohibits companies from improperly influencing foreign officials with ‘anything of value,’ and therefore cash payments, gifts, internships, or anything else used in corrupt attempts to win business can expose companies to an SEC enforcement action,” said Andrew J. Ceresney, Director of the SEC Enforcement Division. “BNY Mellon deserved significant sanction for providing valuable student internships to family members of foreign officials to influence their actions.”
The SEC’s order finds that BNY Mellon lacked sufficient internal controls to prevent and detect the improper hiring practices. The company did have an FCPA compliance policy, but maintained few specific controls around the hiring of customers and relatives of customers, including foreign government officials. Sales staff and client relationship managers were permitted wide discretion in their initial hiring decisions, and human resources personnel were not trained to flag potentially problematic hires. Senior managers were able to approve hires requested by foreign officials with no mechanism for review by legal or compliance staff. BNY Mellon’s system of internal accounting controls was insufficiently tailored to the corruption risks inherent in the hiring of client referrals, and therefore was inadequate to fully effectuate BNY Mellon’s stated policy against bribery of foreign officials.
“Financial services providers face unique corruption risks when seeking to win business in international markets, and we will continue to scrutinize industries that have not been vigilant about complying with the FCPA,” said Kara Brockmeyer, Chief of the SEC Enforcement Division’s FCPA Unit.
The SEC’s order finds that in 2010 and 2011, BNY Mellon violated the anti-bribery and internal controls provisions of the Securities Exchange Act of 1934. Without admitting or denying the findings, the company agreed to pay $8.3 million in disgorgement, $1.5 million in prejudgment interest, and a $5 million penalty. The SEC considered the company’s remedial acts and its cooperation with the investigation when determining a settlement.
The SEC’s investigation was conducted by Eric Heining, Rory Alex, Richard Harper, and Rachel Hershfang of the Boston Regional Office. The case was supervised by Paul G. Block of the FCPA Unit.
Bank Deleveraging Slowed Down in Eastern Europe while Capital Outflows Moderated
Banks in Central, Eastern and Southeastern Europe (CESEE) reduced the pace of deleveraging in the first quarter of 2015 compared with the previous quarter, and the related capital outflows moderated. Credit growth continued to diverge across the CESEE region, according to the latest report from the Vienna Initiative Steering Committee.
Banks reporting to the Bank for International Settlements (BIS) reduced their exposure to the region by 0.3 percent of GDP in the first quarter of 2015, following a 0.7 percent reduction in the fourth quarter of 2014. Excluding Russia and Turkey, the fall in exposure in the first quarter of 2015 was also 0.3 percent of GDP.
BIS reporting banks lowered their exposure in about half of the countries in the region, mostly toward Southeastern Europe and the Commonwealth of Independent States. They increased or maintained their exposure elsewhere.
In line with developments in the BIS banks’ external positions, overall net capital outflows from the region moderated in the first quarter of 2015 relative to the previous quarter.
Credit growth remained uneven across CESEE countries, reflecting differences in growth prospects and different degrees of corporate balance sheet repair. While economic recovery continues in many countries in the region, in about half of the countries output recovery is accompanied by continued contraction or stagnation of credit to the private sector.
The CESEE Deleveraging and Credit Monitor is prepared by the staff of international financial institutions taking part in the Vienna Initiative’s Steering Committee. It is based on the BIS’s International Banking Statistics published on July 24, 2015.
The Vienna Initiative was established at the height of the global financial crisis of 2008/09 as a private-public sector platform to secure adequate capital and liquidity support by Western banking groups for their affiliates in Central, Eastern, and South Eastern Europe (CESEE). It was relaunched as “Vienna 2” in January 2012 in response to renewed risks for the region from the Euro zone crisis.
IMF Managing Director Christine Lagarde Calls for Debt Relief for Greece
Ms. Christine Lagarde, Managing Director of the International Monetary Fund (IMF), made the following statement today:
“The policy package specified in the Memorandum of Understanding (MoU) recently agreed between the Greek authorities and European institutions, with input from Fund staff, is a very important step forward. It not only reverses much of the policy backtracking that caused the previous program to run seriously off track, but puts in place wide-ranging policies to restore fiscal sustainability, financial sector stability, and a return to sustainable growth. I particularly welcome the authorities’ efforts to overcome the serious loss of confidence in recent months through strong upfront actions. Most of these actions have been fully specified in the MoU, and key measures including in the fiscal structural areas will be implemented as prior actions for the disbursement of the first European Stability Mechanism (ESM) tranche.
“In two areas that are of critical importance for Greece’s ability to return to a sustainable fiscal and growth path—the specification of remaining parametric fiscal measures, not least a sizeable package of pension reforms, needed to underpin the program’s still-ambitious medium-term primary surplus target and additional measures to decisively improve confidence in the banking sector—the government needs some more time to develop its program in more detail. This is understandable, and I am encouraged in this regard by the government’s commitment to work with its European partners and the Fund on completing these essential reforms in the coming months. With the detailed specification of these outstanding reforms, the recently agreed MoU will entail a very decisive and credible effort on the part of the Greek authorities to restore robust and sustainable economic growth.
“However, I remain firmly of the view that Greece’s debt has become unsustainable and that Greece cannot restore debt sustainability solely through actions on its own. Thus, it is equally critical for medium and long-term debt sustainability that Greece’s European partners make concrete commitments in the context of the first review of the ESM program to provide significant debt relief, well beyond what has been considered so far.
“In conclusion, I believe that the actions to be taken by the authorities by the time of the first review, in conjunction with the policies specified in the MoU, once they have been supplemented by the above-mentioned fiscal structural and financial sector reforms, as well as by significant debt relief, will provide the basis for a credible and comprehensive program to restore medium-term sustainability. We look forward to working closely with Greece and its European partners in the coming months to put in place all the elements needed for me to recommend to the Fund’s Executive Board to consider further financial support for Greece.”
GE To Sell Healthcare Financial Services U.S. Lending Business To Capital One
FAIRFIELD, Conn. – GE [NYSE:GE] announced today that it has reached an agreement to sell $8.5 billion of healthcare-related loans and its Healthcare Financial Services (HFS) U.S. lending business to Capital One for approximately $9 billion. Separately, GE has signed an agreement with another buyer to sell approximately $600 million of HFS real estate equity investments.
“This transaction is another example of the value generated by GE Capital’s strong businesses and exceptional teams as we continue to demonstrate speed and execute on our strategy to sell most of the assets of GE Capital,” said Keith Sherin, GE Capital chairman and CEO. “We are on track to reduce our ending net investment (ENI) by $100 billion by the end of 2015 and expect to be substantially done with our exit strategy by the end of 2016,” he added.
GE Capital, Healthcare Financial Services provides financing to U.S. healthcare companies, sponsors, investors and developers across various healthcare sectors including senior housing, hospitals, medical offices, outpatient services, pharmaceuticals and medical devices. Darren Alcus, president and CEO of HFS, will join Capital One. Capital One also will retain the HFS management team and employees.
“We’re pleased to sell HFS to a company that is committed to expanding the business,” said Sherin. “Our customers, sponsors and HFS employees will benefit from the synergies of combining Capital One’s existing healthcare lending businesses with the expertise, relationships and experience of our highly-regarded HFS team.”
As previously announced, GE is embarking on a strategy to focus on its high-value industrial businesses and is selling most GE Capital assets. GE and its Board of Directors have determined that market conditions are favorable to pursue disposition of these assets.
GE Capital will retain the financing “verticals” that relate to GE’s industrial businesses, including a unit that provides healthcare equipment financing to GE Healthcare customers and others.
When completed, the transaction, which represents about $8.4 billion of ENI ($8.5 billion of assets), will contribute approximately $1.5 billion of capital to the overall target of approximately $35 billion of dividends expected to GE under this plan (subject to regulatory approval). GE is on track to reduce total ENI at GE Capital by about $100 billion by year end. With this transaction, the total for announced sales is approximately $78 billion.
Sherin concluded, “This announcement is the next step in GE’s transformation to a more focused industrial company.”
The transaction is subject to customary regulatory and other approvals and is expected to close in the fourth quarter of 2015. Citigroup Global Markets Inc. and J.P. Morgan Securities LLC provided financial advice to GE and Hogan Lovells US LLP provided legal advice.
About GE
GE (NYSE:GE) imagines things others don’t, builds things others can’t and delivers outcomes that make the world work better. GE brings together the physical and digital worlds in ways no other company can. In its labs and factories and on the ground with customers, GE is inventing the next industrial era to move, power, build and cure the world. www.ge.com.
GE’s Investor Relations website at www.ge.com/investor and our corporate blog at www.gereports.com, as well as GE’s Facebook page and Twitter accounts, including @GE_Reports, contain a significant amount of information about GE, including financial and other information for investors. GE encourages investors to visit these websites from time to time, as information is updated and new information is posted.
Berkshire Hathaway Inc. to Acquire Precision Castparts Corp. for $235 Per Share in Cash
OMAHA, Neb. & PORTLAND, Ore. – Aug. 10, 2015 – The boards of directors of Berkshire Hathaway Inc. (NYSE: BRK.A; BRK.B) and Precision Castparts Corp. (“PCC”) (NYSE: PCP) have unanimously approved a definitive agreement for Berkshire Hathaway to acquire, for $235 per share in cash, all outstanding PCC shares. The transaction is valued at approximately $37.2 billion, including outstanding PCC net debt.
“I’ve admired PCC’s operation for a long time. For good reasons, it is the supplier of choice for the world’s aerospace industry, one of the largest sources of American exports. Berkshire’s Board of Directors is proud that PCC will be joining Berkshire,” said Warren E. Buffett, Berkshire Hathaway chairman and chief executive officer.
“We are very pleased to be joining forces with Berkshire Hathaway,” said Mark Donegan, PCC’s chairman and chief executive officer. “We see a unique alignment between Warren’s management and investment philosophy and how we manage PCC for the long-term. We believe that as part of Berkshire Hathaway, PCC will be exceptionally well-positioned to support our customers’ needs into the future. This transaction offers compelling and immediate value for our shareholders, and allows PCC’s employees to continue to operate in the same manner that has generated many years of exceptional service and performance to our customers.”
The transaction requires approval by a majority of PCC’s outstanding shares. Closing is expected to occur during the first quarter of calendar 2016, subject to customary closing conditions, including clearance under the Hart-Scott-Rodino Act and competition clearance in certain foreign jurisdictions.
PCC will continue to do business around the world under the Precision Castparts name and maintain its headquarters in Portland, Oregon.
In light of this announcement, the three nominees who would have joined PCC’s Board of Directors if elected at PCC’s upcoming Annual Meeting of Shareholders, Peter B. Delaney, James F. Palmer and Janet C. Wolfenbarger, have withdrawn their candidacy. None of Mr. Delaney, Mr. Palmer or Ms. Wolfenbarger currently serves on PCC’s Board of Directors and PCC does not intend to nominate replacement directors for election at the Annual Meeting in their place. Other than Mr. Delaney, Mr. Palmer and Ms. Wolfenbarger, the nominees named in the Proxy Statement sent or made available to PCC shareholders, all of whom currently serve on PCC’s Board of Directors, intend to stand for election at the Annual Meeting. PCC intends to convene its Annual Meeting on August 11, 2015 as currently scheduled and, without conducting any business, adjourn the Annual Meeting to August 17, 2015 at 10:00 a.m., Pacific Time, in the Bella Vista Room of the Aquariva Restaurant, 0470 SW Hamilton Court, Portland, Oregon.
Credit Suisse acted as financial advisor to PCC and PCC’s legal counsel is Cravath, Swaine & Moore LLP and Stoel Rives LLP. Berkshire Hathaway’s legal counsel is Munger, Tolles & Olson LLP.
About Berkshire Hathaway (www.berkshirehathaway.com):
Berkshire Hathaway and its subsidiaries engage in diverse business activities including insurance and reinsurance, utilities and energy, freight rail transportation, finance, manufacturing, retailing and services. Berkshire Hathaway’s common stock is listed on the New York Stock Exchange, trading symbols BRK.A and BRK.B.
About Precision Castparts Corp. (www.precast.com):
Precision Castparts Corp. is a worldwide, diversified manufacturer of complex metal components and products. It serves the aerospace, power, and general industrial markets. PCC is a market leader in manufacturing complex structural investment castings and forged components for aerospace markets, machined airframe components, and highly engineered, critical fasteners for aerospace applications, and in manufacturing airfoil castings for the aerospace and industrial gas turbine markets. PCC also is a leading producer of titanium and nickel superalloy melted and mill products for the aerospace, chemical processing, oil and gas, and pollution control industries, and manufactures extruded seamless pipe, fittings, and forgings for power generation and oil and gas applications.
HSBC to sell Brazil Business to Bradesco
HSBC is selling its entire business in Brazil to Bradesco for a consideration of US$5.2bn
The transaction represents a significant step in the execution of the actions announced during the Investor Update on 9 June 2015
Overview of transaction
HSBC Holdings plc (‘HSBC’) has entered into an agreement to sell its entire business in Brazil, comprising HSBC Bank Brasil S.A – Banco Multiplo and HSBC Servicos e Participacoes Ltda (collectively ‘HSBC Brazil’), to Banco Bradesco S.A (‘Bradesco’) for an all cash consideration of US$5.2bn (‘the Transaction’). This represents a price to tangible book value multiple of 1.8x based on 30 June 2015 accounts. As at the completion of the Transaction, the purchase price is subject to adjustment to reflect the movement in the net asset value of the business between 31 December 2014 and completion.
Progress in executing HSBC’s strategy
The sale of HSBC Brazil represents a significant step in HSBC’s stated goal to optimise its global network and reduce complexity, outlined during the HSBC Investor Update on 9 June 2015.
The Transaction will also be a key contributor to the Investor Update action to reduce Group RWAs, accounting for c.US$37bn of the overall c.US$290bn planned reduction, enabling future redeployment of RWAs to support growth opportunities.
Commenting on the Transaction, Stuart Gulliver, Group Chief Executive, said: “We announced at our Investor Update on 9 June that we were targeting a series of actions to generate increased value for shareholders. I am pleased to be able to announce today a transaction which achieves both a solid financial outcome and swift delivery of one of our stated actions.”
HSBC is pleased to be working with Bradesco on this Transaction, given its leading franchise in the Brazilian market and commitment to HSBC staff and customers.
The Transaction is subject to regulatory approval.
HSBC plans to maintain a presence in Brazil to serve large corporate clients with respect to their international needs.
“IMF Can Only Support a Program For Greece That is Comprehensive” Says IMF Official on Greece
MS. GAVIRIA: Hello, everyone. I’m Angela Gaviria with the IMF’s Communications Department. Welcome to this conference call on Greece. Here with me is an IMF official, who will make some points and then take your questions.
IMF OFFICIAL: Yes. Thank you. And welcome. I want to focus on explaining to you the process that is now ongoing and the role of the IMF in this regard. Those of you who have been following us closely, and particularly the discussions we’ve had in the last couple of months, will not find that I’m saying anything that is new, but let me nevertheless repeat where we are.
Let me start from the point that, again, as we’ve said before, the IMF can only support a program that is comprehensive. What do we mean? We mean a program that ensures medium-term sustainability. There’s nothing new to that; every time the IMF goes to the Board, we need to ensure our Board that there is sustainability in the medium-term context.
And this is nothing special for Greece. It’s a criterion we apply to all members, to all releases of IMF money, and we will, of course, also apply this in this case. What we have also said is that the Greek situation is very difficult. In order to ensure that sustainability, that medium-term sustainability, there’s a need for difficult decisions on both sides and by both sides. I mean, difficult decisions in Greece regarding reforms, and difficult decisions for Greece’s European partners about debt relief.
So, for it to –and we have used the phrase many times– for it to add up, one needs difficult decisions, and you should not be under the illusion that just one side of it can fix the problem. Greece will not be in a medium-term sustainable position just on debt relief, and on the other hand, yet Greece cannot get into a medium-term sustainable position just on reforms of its own. It needs to be a combination of these two sets of issues. What is clear is that it will take some time before the two sides are ready to take these decisions, it was made clear at the meeting of European leaders a few weeks ago that they were not ready to consider the debt operation before the fall.
They said that at the time of the first review of the ESM program they wanted to see implementation of the policies before they are willing to discuss debt relief in the necessary details. And I think it’s also clear from discussions on the part of the Greek authorities that some of the necessary decisions regarding particular fiscal structural reforms will only be taken in the coming months.
So I think everybody understands that the IMF can only be in at that time when these decisions on these two sides are taken. There’s nothing new here, nothing new on deciding to suddenly have a two-stage approach. It’s always been clear that the IMF will only come in once these conditions are in place. So, let me stop here; and I’ll take your questions.
QUESTIONER: Thanks for doing this. One quick, just technical question, and then another, perhaps, more substantive one. When you are talking about — in terms of sustainability, I just want to confirm, you are talking about debt sustainability. Correct? And then secondly, can you be more precise in terms of what you mean the IMF cannot support a program until medium-term sustainability is in place? By that do you mean you will not take a program to the Board for approval? Or, are you saying that you don’t think the Board will approve it without that in place? Can you elaborate on that? Thanks.
IMF OFFICIAL: Yes to the first question. I’m talking about medium-term debt sustainability, but you cannot have medium-term debt sustainability while other parts of the program are not sustainable. So, it’s the overall program that needs to be sustainable, but this indeed comes down to a test of whether the debt is sustainable.
On the second question, yes, management will clearly not want to submit to the Board, and I’m sure the Board will not want to approve, a program that does not meet the normal criteria for access to the Fund’s resources, and the normal criteria is that there is medium-term sustainability. So, this is the answer.
QUESTIONER: A quick follow. Is another one of your conditions that it be fully financed for 12 months? Is that also a condition?
IMF OFFICIAL: Yes. As always, programs have to be fully financed. We need to have adequate financing assurances, and the way you operationalize this is that we need concrete assurances for the first 12 months, that’s the normal practice for the IMF.
QUESTIONER: I was wondering if you could be more precise about what you expect from the Europeans. Do you expect like a formal commitment to reduce the debt and what is the scale that you are looking at? And also can you also give some clarification on, I mean, does it mean that the former debt program of the IMF that was running until 2016, is dead? I mean, can you clarify that? Thank you.
IMF OFFICIAL: There has been no detailed discussion yet about how this debt relief is going to be provided. There’s a menu of options, but there’s essentially an agreement; we accept that that discussion will take place in stage 2, and I think that the Greek authorities have accepted that also because it’s in the communiqué from the recent Leaders’ meeting. So that’s the conversation that we will have in the next couple of months, but there has not been a detailed conversation about debt yet.
Yes, there is a request for a new program, a new multi-year program. And why? We had a program, and we currently have to replace the program that expires by the end of March. The criteria of the IMF when approving a program is always that the program has to meet its objectives by the end of the program period. The current program is off-track and it will only be able to reach the objectives by the end of the program period, so we need to recalibrate the program and get an essentially longer time to reach the objectives, and this is why we have a longer program now under consideration.
QUESTIONER: If I could just follow up quickly. Can you be more precise? Are you expecting a formal commitment from the Europeans to join them on this new bailout? Can you be more precise?
IMF OFFICIAL: I don’t understand what you mean by the question.
QUESTIONER: I mean, do you expect them to come with the terms of the debt release number to join the new bailout?
IMF OFFICIAL: We expect that by the time we go to the Board there is an explicit and concrete agreement between Greece and its European partners on how to provide debt relief. Yes, we expect that by the time we go the Board at stage 2, an explicit and concrete agreement of how to provide debt relief.
QUESTIONER: Thank you very much for doing this. My question is first about the debt relief. You’ve indicated earlier that there will be a point at which maturity extensions no longer are feasible, and there would need to be haircuts basically, which is a no-go for the Europeans. Can you give us some idea when that point would be reached? And given the drastic situation in the Greek finances, is it, maybe, already reached? And then another, the Greek government has said that in order to basically calm the internal opposition, there will be no additional reform negotiated with the renewed Troika. Is that acceptable to the IMF as long as Greece does everything that it has agreed to so far here in the Brussels summit? Thank you.
IMF OFFICIAL: On the first question, I will refer you to our updated DSA that was released a couple of weeks ago. Our views have not changed since then. We have a mission in the field that just started discussions, actually the mission chief is only arriving today. And so we have no reason to change our views since that DSA.
That DSA said that there’s a menu of options. If we’re going to reach the point where that menu of options will narrow, well, let’s see what these discussions that have just got underway will produce. I don’t have any other views than reflected in the DSA. On the second part of the question, I have not heard the authorities put it like the way you put it. I have heard the authorities say — or I’ve seen press reports, I’ve never heard it from them — I’ve seen press reports questioning the need for further measures before the ESM approval of a new program, so in stage one. That I have seen in press reports, but I have not had any – as I said, we have a mission in the field today so I do not know what the authorities’ view and it’s best to ask them directly. But that’s a different issue. What are the conditions for the ESM to disburse at stage one is really between Europe and the Greek authorities. We come in at stage two.
QUESTIONER: In excerpts from the minutes of the Board meeting yesterday that were published in the Financial Times, the German representative seemed to express dismay that the IMF would not be going along, would not be following the process in parallel with them. And so if it’s really the case that — so it made it sound like it was a live issue at that meeting. If that’s not the case and your decision to wait for stage two was made some time ago, could you confirm who made that decision and when it was made?
The second question: Does this make for a substantive change in the IMF’s role in the current negotiations, the current talks in Europe? Because it sounds like on some level this just might be procedural of whether you reach a staff agreement when your negotiators could be involved in helping shape whatever deal is going to be arrived at. So does this make for a substantive change in what your people will be doing in Brussels and Athens in the coming weeks? Thanks.
IMF OFFICIAL: On the first part of it, I am not going to comment on who said what at the Board. Let me make very clear that the Fund, our Managing Director, myself, we’ve been talking about this to our partners and to the public and we have always made very clear what are the conditions for the Fund. It’s a comprehensive program. There’s nothing new — I mean, go and look at the Mr. Blanchard’s two recent blog posts. They’re very explicit about that.
They were posted before the summit and I can assure you that at the recent summit and Eurogroup meeting there was no misunderstanding about what is the role of the Fund and when we can come in. There is nothing new here. That was also accepted yesterday and understood at the Board.
Now in terms of — you say there’s a change in the role of the Fund. It is not correct. We are not just an observer; we’re not sitting in the sidelines. We are participating actively and fully in the policy discussions in the coming weeks. But there is a clear understanding among all of us that these policy discussions will not include at this stage, will not pertain at this stage to a number of issues — policy issues — that are critical for a medium-term program. So there’s no expectation that all the issues that would need to be covered for us to have a credible package on the table, would all be settled in the next couple of weeks. So this is another way of saying that part one will be completed while a number of policy issues are still outstanding, we are fully involved in these discussions and I can’t see how we are an observer on the sidelines on anything like that.
QUESTIONER: When does the IMF expect Greece’s arrears to be cleared, and is that a prerequisite for getting involved in any new program? And the second is that given that Greece (inaudible) conditions in the earlier bailouts, including a very aggressive fiscal tightening and actually moved considerably further away from debt sustainability rather than towards it. Shouldn’t there be questions asked about whether the IMF should ever have gotten involved in these bailouts in the first place?
IMF OFFICIAL: On the first point, arrears were cleared a long time ago, several weeks ago.
QUESTIONER: Okay. Sorry. All right. Apologies.
IMF OFFICIAL: So the situation is evolving. And that leads me to the next question also. We are always happy to revisit whether we can do things differently and should have done things differently.
I can assure you that we learn as we go along and evolving circumstances and whatever experience we have will be embodied in any new discussions that we have. And this is of course one of the reasons why we say this requires difficult decisions on both sides.
QUESTIONER: Thank you. I would like confirmation that the new IMF program which has been requested by the Greek government will have the same end period and the same horizon with the ESM program, meaning 2018.
IMF OFFICIAL: There has been no discussion on the exact duration of this program. But my understanding would be that it would sort of broadly coincide with the duration of the ESM program. But I have to admit that those discussions have not taken place yet.
QUESTIONER: Yesterday you briefed the Board. Can you tell us what the Board decided and if they decided to support the mission and the involvement in the third program?
IMF OFFICIAL: Formally what happened was that the Managing Director informed the Board that she has decided to authorize staff to open discussions on a new program that could be supported under the exceptional access policy. So the Board accepted that staff opens discussions on the option and see whether we can get agreement on a credible program that we can support. So that is formally what happened, that the Board accepts that we start these discussions.
MS. GAVIRIA: Well, thank you all. We’ll end this conference call here.
Euro Area Recovering, But Lasting Growth Requires Collective Push According to IMF
The euro area recovery is strengthening, but the weak medium-term outlook calls for focus on four key areas: increasing demand, cleaning up bank balance sheets, stepping up structural reforms, and strengthening governance, said the IMF’s latest review of the currency union.
Although unemployment is still high, steady job growth and rising real wages have underpinned a rebound in consumption, the report said. Strong policy actions by the European Central Bank (ECB) have also boosted confidence and improved financial conditions.
Among the large economies, Germany continues to grow slightly above 1½ percent, while Spain is rebounding strongly. Italy is emerging from three years of recession, and activity in France picked up at the beginning of this year.
The recovery is supported by cheaper oil, monetary easing, and a weaker euro, with growth in euro area economies expected to rise modestly to 1.5 percent this year and 1.7 percent in 2016.
But medium-term prospects are less bright. “Several factors cloud the outlook for growth over the next five years,” said Mahmood Pradhan, mission chief for the euro area. “These include high unemployment, especially among the youth; large corporate debt; and, rising non-performing loans (NPLs) in the banking system.” Slow progress on structural reforms has also dampened the business climate and reduced growth potential. As a result, the euro area remains vulnerable to shocks. “A moderate shock to confidence—whether from lower expected future growth or heightened geopolitical tensions—could tip the block into prolonged stagnation,” said Pradhan.
To counter the risks of stagnation, the report called for a stronger collective push to strengthen the recovery and make the monetary union more resilient.
Strengthening demand
Staying the course on the expanded asset purchase program, or quantitative easing (QE) is essential, says the report. “While quantitative easing has already improved financial conditions and raised inflation expectations, international experience suggests that its impact on the real economy will take more time,” said Pradhan. But strengthening bank and corporate balance sheets could significantly amplify the impact of quantitative easing via more bank lending to revive credit growth. While there are currently few signs of scarcity in sovereign bond markets, the ECB should develop a common securities lending framework to increase the availability of collateral for market participants. Macro-prudential policies should serve as the first line of defense against potential financial stability risks.
On fiscal policy, the report encourages countries to adhere to their commitments under the Stability and Growth Pact. Countries with limited budget space (such as France and Portugal) should save interest windfalls from quantitative easing to pay down debt. Others (such as Germany and the Netherlands) should use them to support investment and structural reforms. Doing this now in a period of low interest rates, can have a powerful growth impact. There is a further call to expedite the centralized investment initiative (“Juncker Plan”) to support demand, especially in countries with limited fiscal room.
Cleaning up bank balance sheets to support new lending
The ECB’s 2014 Comprehensive Assessment of European banks enhanced transparency and strengthened capital positions. The report, however, notes NPLs have continued to rise and are dangerously high in some economies—eroding bank profitability and locking up capital that could otherwise support new lending. Expeditiously reducing NPLs could generate significant capacity for new lending, particularly in countries with high bad loans.
Three complementary actions to remove bad loans from bank balance sheets quickly include: strengthening prudential supervision; undertaking insolvency reforms to accelerate court procedures and facilitate out-of-court settlements; and developing a market for bad loans to help corporate restructuring. Asset management companies (AMCs), for example, could help banks to work with investors to offload bad loans. In some cases, public sector involvement in AMCs may be beneficial, subject to EU State aid rules.
Advancing reforms within a stronger, simpler governance framework
The report urges authorities to leverage the opportunity provided by the cyclical upturn and monetary accommodation to accelerate structural reforms. At the national level, priorities include reforms to make hiring and firing easier; improve the business climate; and promote competition. At the regional level, the priorities are to implement swiftly the Services Directive to eliminate long-held national barriers; enhance insolvency regimes; and push more strongly for a single market in capital, transport, energy and the digital economy.
The report also calls for a stronger and simpler governance framework to support such efforts. Important components of this framework would include: benchmarking reforms against outcomes (that are clearly observable and measurable), stronger EU oversight with less discretion in applying existing rules, and better financial incentives for reforms. A capital markets union would help diversify funding sources for small- and medium-sized enterprises, reduce reliance on bank lending, and promote more cross-border finance.
The fiscal framework has become more complex following successive reforms over the past years, the report observed. To make it more effective, it should be simplified by focusing on two main pillars: a single fiscal anchor (public debt-to-GDP) and a single operational target (an expenditure growth rule) linked to the anchor.
Japan is Ramping up Policy Actions for Lasting Economic Change – IMF
Abenomics has lifted Japan out of the doldrums, according to the IMF’s latest assessment of the Asian economy. But, policies need to be reinforced to end the lingering deflationary mindset, raise growth, restore fiscal sustainability, and maintain financial stability without undue reliance on yen depreciation.
The IMF report found that Abenomics’ three-pronged strategy of aggressive monetary easing, flexible fiscal policy, and structural reforms constituted a clear break from previous incremental efforts. But, despite initial positive results, the pace of real GDP growth has remained at about 1 percent—similar to the post-bubble period—and deflation risks remain.
“This is partly due to external shocks, including slower global growth, and the collapse in commodity prices” said Kalpana Kochhar, Deputy Director in the IMF’s Asia and Pacific Department, and head of the mission that conducted the assessment.
In addition, the negative impact of the consumption tax rate hike in 2014 lasted longer than expected, but structural impediments have also played a role, including sluggish wage growth, production increasingly moving to other countries through foreign direct investment, and headwinds from an aging and declining population.
Recovery underway but momentum still fragile
The economy is projected to grow by 0.8 and 1.2 percent in 2015 and 2016, provided higher real wages support consumption, and business investment rises on the back of lower production costs from declining oil prices, record-high corporate profits, ongoing corporate governance reforms, and the abundant availability of credit.
“However, risks are elevated and clearly to the downside, including from a disappointing outcome of the Shunto wage negotiations, and weaker spending of the oil windfall,” said Kochhar.
Japan also faces short-term risks from lower-than-expected growth in China and the United States, and possible yen appreciation in the event of global financial turbulence given its status as a safe-haven currency.
“Over the medium term, weak domestic demand, and incomplete fiscal and structural reforms could result in stagnation, and doubts about fiscal sustainability” added Luc Everaert, Head of the Japan Division in the IMF’s Asia and Pacific Department.
The report suggests accelerating structural reforms is the only effective policy lever to address these downside risks, and maintain confidence in Abenomics.
Wanted: stronger structural reforms
Structural reforms have progressed in a number of areas. Female labor force participation, which had been rising gradually since the mid-2000s, got a further boost with Abenomics.
“Even so, countering the headwinds on labor supply from adverse demographics requires more forceful labor market reforms” said Kochhar. Female labor force participation can be boosted further by eliminating tax-induced disincentives to work, and raising the availability of child-care facilities through deregulation.
The government can also address labor shortages by drawing more aggressively on foreign labor by relaxing immigration restrictions, as well as providing incentives for older workers to remain in the workforce.
New hiring should take place under contracts that balance job security and flexibility to reduce labor market duality, and raise horizontal mobility, contributing to higher productivity and wage growth.
The financial sector should become a catalyst for growth, the report notes. It should take advantage of the recent significant progress with corporate governance reforms to unwind cross-shareholdings, foster consolidation in the enterprise sector, and promote exit of unviable enterprises.
The report recommends that authorities phase out financial sector support schemes for small and medium-sized enterprises that do not invest or hire workers, and promote the expansion of securitization, and the provision of risk capital. Private sector–led consolidation in the financial system, in particular among regional banks, would also be beneficial.
Balanced fiscal adjustment
Low and stable Japanese government bond yields should not be taken for granted as shifts in investor sentiment could happen abruptly. A concrete and credible medium-term plan would remove uncertainties about fiscal intentions, which could be hampering domestic demand, and create space to respond to downside risks.
And stronger fiscal institutions will be necessary to impart credibility to such a strategy. In this context, the announced medium-term plan provides a useful anchor to guide fiscal policy with the planned adjustment between now and 2020 striking the right balance between supporting growth, and making headway with fiscal consolidation.
“However, the use of overoptimistic growth assumptions risks undermining the credibility of the plan, while it also lacks specifics about how to contain social security spending,” said Kochhar.
Supportive and predictable monetary policy
“Raising inflation has proven to be a marathon rather than a sprint,” said Everaert. Market-based measures of inflation expectations have declined since mid-2014, and recently stabilized at around 1 percent, suggesting the hoped for “regime change” has not yet fully materialized.
The report suggests that several factors will put upward pressure on the price level in the near term, including the recovery of oil and commodity prices from their lows, the lagged effect of the recent episode of yen weakening, and the closing of the output gap–or the difference between the potential output of an economy and its actual output. Continued tightening of the labor market could accelerate nascent wage-price dynamics. Under current policies, IMF staff expect inflation to rise gradually to 1½ percent over the medium term.
As a result, the Bank of Japan needs to stand ready to ease monetary policy further, provide stronger guidance to markets through enhanced communication, and put greater emphasis on achieving the 2 percent inflation target in a stable manner.
Further monetary easing should take the form of increased asset purchases, and lengthening their duration. At the same time, further fiscal and structural reforms remain imperative to unburden monetary policy and, together with macroprudential policies, mitigate financial stability risks. This would also help avoid harming direct competitors through excessive yen depreciation.
“The BoJ should communicate more clearly the drivers that underpin its forecasts,” said Kochhar. Similarly, clarifying the conditions that would trigger additional actions would help guide market expectations when there is a need to adjust the asset-purchase program, and facilitate preparations for an eventual exit.
“In this context, the BoJ recently announced helpful modifications to its communication framework, but more needs to be done to enhance transparency, and predictability of monetary policy decisions,” concluded Everaert.
Decline in Euro Banknote Counterfeits in First Half of 2015 – Overall Number Remains Very Low
In the first half of 2015 a total of 454,000 counterfeit euro banknotes were withdrawn from circulation –10.5% down on the figure for the second half of 2014, but still higher than in the first half of 2014. The number of counterfeits continues to remain very low in comparison with the increasing number of genuine banknotes in circulation (over 17 billion during the first half of 2015).
Ever since the first euro series was issued, the Eurosystem – i.e. the European Central Bank (ECB) and the national central banks of the euro area – has urged people to stay vigilant when receiving banknotes. Genuine banknotes can be easily recognised using the simple “feel, look and tilt” method described on the euro pages of the ECB’s website and the websites of the Eurosystem national central banks.
If you receive a suspect banknote, you can compare it directly with one you know is genuine. If your suspicions are confirmed, you should contact either the police or – depending on national practice – the respective national central bank. The Eurosystem supports the law enforcement agencies in their fight against currency counterfeiting.
The Eurosystem has a duty to safeguard the integrity of the euro banknotes and continue improving banknote technology. The Europa series is designed to make the banknotes even more secure and to help maintain public confidence in the currency.
During that period:
the €20 and €50 continued to be the most counterfeited banknotes. Compared with the figures reported for the second half of 2014, the proportion of counterfeit €20 notes decreased slightly and that of counterfeit €50 notes increased. Together, they accounted for 86% of the counterfeits; most (97.9%) of the counterfeits were found in euro area countries. Only around 1.6% were found in EU Member States outside the euro area and less than 0.5% were found in other parts of the world.
The Eurosystem communicates in various ways to help people distinguish between genuine and counterfeit notes, and to help professional cash handlers ensure that banknote-handling and processing machines can reliably identify and withdraw counterfeits from circulation. Banknote equipment manufacturers and suppliers will continue to receive support from the Eurosystem in adapting their machines and authentication devices to the Europa series banknotes. If their equipment is still unable to accept these banknotes, operators/owners should contact their suppliers or manufacturers without delay.
The new €20 banknote will be issued as from 25 November 2015.
China Launches First World Bank Trust Fund to End Poverty and Promote Development
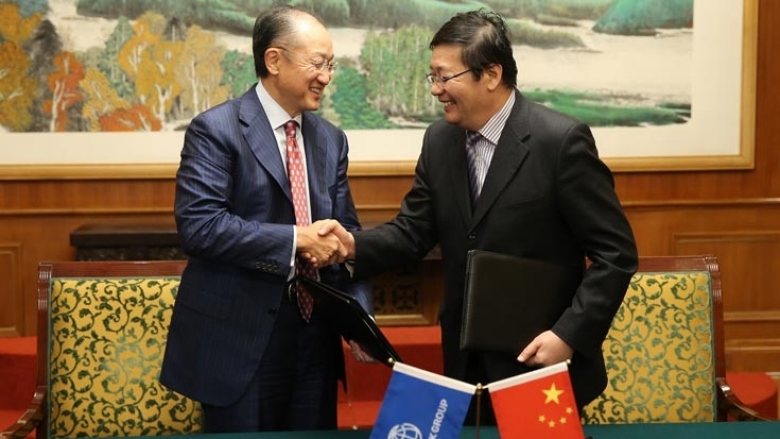
BEIJING, — World Bank Group President Jim Yong Kim today praised China for its growing role in global development in meetings with Premier Li Keqiang and other senior leaders including Finance Minister Lou Jiwei and Governor Zhou Xiaochuan of the People’s Bank of China.
On the first day of his two day visit, President Kim had a far reaching discussion with Premier Li Keqiang on the global economy, development finance and China’s health reforms.
In a separate meeting today, President Kim and Finance Minister Lou Jiwei signed an agreement to establish a $50 million fund to help reduce poverty. The World Bank President also met with leaders of the Multilateral Interim Secretariat for Establishing the Asia Infrastructure Investment Bank (AIIB) to discuss closer collaboration.
These initiatives reinforce the growing partnership with China, which already is the Bank’s third-largest shareholder and an important contributor to IDA, the institution’s fund for the poorest, as well as the Global Infrastructure Facility.
“China is a strong partner in development and a strong partner for the World Bank Group, and we share the commitment to ending poverty and boosting shared prosperity,” said President Kim. “I look forward to a continued strong, cooperative, and productive relationship, which will benefit developing countries around the world.”
The trust fund, which is expected to start later this year, aims to enhance the cooperation between China and the World Bank Group and leverage financial and knowledge-based resources to help developing countries achieve inclusive and sustainable development. It will finance investment projects, operations, knowledge development and human-resource cooperation at both global and regional levels.
“The establishment of this trust fund signals that our partnership with existing multilateral development banks is growing, even as we support new ones. We will continue to partner with the World Bank in fighting poverty and promoting development around the world,’ said Minister Lou.
During his two-day trip to China, President Kim also met with Secretary General Jin Liqun of the AIIB Multilateral Interim Secretariat, who has been nominated by the Chinese government to be the bank’s President-designate. Both agreed to expand their cooperation and explore opportunities for joint financing of projects in the coming months. The prospective founding members of the AIIB signed the Articles of Agreement last month and the bank is expected to be operational by the end of the year.
“I congratulate Secretary General Jin Liqun and all prospective founding members on the great progress made in establishing the AIIB,” said President Kim. “More funding for infrastructure will help the poor, and we are pleased to be working with China and others to help the AIIB hit the ground running.”
Secretary General Jin said: “Since the establishment of the Multilateral Interim Secretariat last November, the World Bank has been very generous in sharing its expertise, lessons of experience and global good practice knowledge with the Secretariat. We plan to identify projects for possible co-financing in the fall. Based on my time at the World Bank as an Alternate Executive Director, I am fully confident that such close cooperation between the Banks will lead to improved lives for citizens of our Member countries.”
The AIIB Multilateral Interim Secretariat and the World Bank are already working together, having exchanged views on matters such as institutional governance, organizational structure, social and environmental safeguards and procurement procedures.
United Kingdom £20 Banknote Character Selection and Future Banknote Design
Yesterday, the two month public nomination period to determine who should appear on the next £20 note officially closed.
Since 19 May, members of the public have nominated visual artists who they believe helped to shape British thought, innovation, leadership, values and society.
In total 29,701 nominations were made, covering 592 eligible visual artists. The Bank of England’s Banknote Advisory Committee will now consider all eligible nominations and, together with input from public focus groups, produce a shortlist of 3-5 names. These will then go to the Governor for a final decision. Both the Committee and the Governor will make their decisions with reference to the character selection principles announced in December 2013 and will only consider people nominated by the public.
The decision will be announced in spring next year, alongside a concept image showing the character’s portrait as it will appear on the note. The new £20 note is expected to enter circulation by 2020.
The Bank of England is also announcing today that future banknotes, starting with the £5 polymer note in 2016, will include symbols representing all four of the home nations. The imagery will be taken from the Royal Coat of Arms and the Royal Badge of Wales. This follows discussions with the First Ministers of Wales, Scotland and Northern Ireland. The design will be released at the unveiling of the new £5 note next year.
Chief Cashier, Victoria Cleland said:
“The Bank is delighted with the number and breadth of the nominations we have received, and we are very grateful to all those who have engaged with us on this new initiative. The fact that so many visual artists have been put forward by the public underlines the extent of British achievement in the visual arts and reinforces why this field deserves to be recognised on the next £20 note.”
“During this process, we have repeatedly heard how important banknotes are as a symbol of the United Kingdom. So the Bank is pleased to announce today that after careful consideration future banknote designs, starting with the new polymer £5 note, will explicitly represent all four nations of the UK.”
From Lincoln to Lothbury: Magna Carta and the Bank of England – speech by Mark Carney
A burst of inflation. A crisis in the public finances. Public sector bailouts. Infighting in Europe. Not eight years ago, but eight hundred.
That was the economic context for the striking of Magna Carta.
To many today, Magna Carta is a document of profound, almost mythical, significance. It is seen as the cornerstone of the United Kingdom’s constitutional arrangements and as a blueprint for the constitutions of many other nations, including the United States. It is credited with establishing the foundations of parliamentary democracy, creating a framework for the rule of law, protecting individual liberty, defending the rights of the innocent, and limiting the role of the State.
It is undoubtedly true that Magna Carta – or more correctly the idea of Magna Carta – has played a central role in British political development over the centuries, not least as a banner under which those seeking liberty from oppression have rallied.
But many modern scholars argue that its significance, in and of itself, has been overstated. They characterise Magna Carta as a pragmatic political document that was a product of its time, including the difficult economic circumstances that then prevailed.
As usual with historical arguments, the answer lies somewhere in between.
In what follows, I will spend a few moments on the pragmatic element not only because it plays to my comparative advantage as an economist but also because it ultimately underscores the foundational character of the document itself.
The enduring legacy of Magna Carta is how its strictures on unconstrained power are reflected in our systems of political and economic governance.
I will conclude that both the constitutional and pragmatic perspectives are relevant to modern central banking and the current conduct of monetary policy. Specifically, the costs of inflation were among the key economic catalysts of Magna Carta, and its core constitutional legacy – namely the importance of delegated authority, with clear lines of public accountability – is at the heart of the Bank of England’s institutional arrangements. In the spirit of Magna Carta, the Bank of England has been given a great responsibility: to deliver monetary stability for the good of the people of the United Kingdom. Our goal, the 2 per cent inflation target, is set by the Government, and we operate under constrained discretion in its pursuit.
1. The economic and political context
Where did Magna Carta come from?
The political background is one of nearly constant conflict both within the dysfunctional ‘English’ monarchical family, as well as with France over control of Normandy and the rest of Henry II’s continental empire.[1]
The England of the 1200s was far from a unitary state. Most matters were administered by local barons, with the King acting as an arbiter in the event of a dispute. The relationship between local (baronial) and central (monarchical) authority was much less deferential, and much more arms-length, than it is today. Indeed, the early Plantagenet Kings of England spent most of their time living at home in Normandy or Anjou, allowing the English barons a considerable degree of autonomy. It was only after King John lost Normandy to the French in 1204 that the King resided full-time in England, breathing down the necks of the barons, who did not much like the closer observation of their activities, and the eyeing of their stockpiles of silver that this proximity entailed.
The relationship between the barons and King John broke down in part because of unsustainable public finances, with John imposing an intolerably heavy and arbitrary tax burden in order to pay for royal extravagance, infighting, and wars with the French. The royal judicial system, whose tendrils extended ever deeper into the barons’ lives, was used to extort cash and as an instrument of royal control, rather than to ensure ‘justice’.
What lay behind such unsustainable public finances?
First, and most obviously, the need to pay for constant military protection for the Normandy estates created what modern-day macroeconomists would think of as an enormous structural deficit. If John had let his expulsion from the continent be the end of the matter this financial burden would have extinguished itself. But he did not. His folly was a series of vain attempts to re-conquer Normandy, efforts which finally ended on the eve of Magna Carta.[2]
Second, the monarchic finances had taken a colossal hit in 1193 because of the need to fund a gigantic public sector bailout. Richard I had managed to get himself caught in Germany on his way back from the Holy Land and was held to ransom for £66,000 in silver. Being ‘Too Big To Jail’, the equivalent of two to three times annual crown income was needed to bail him out. In comparison, the government’s peak cash support to UK banks in 2007-2010 amounted to a trifling one-quarter of annual UK government
revenues[3]
Third, the need to raise additional cash for the public finances was made much more problematic by the strain of inflation, which accelerated in the early years of the 13th century.[4] The problem was that a large proportion of regular crown income came in the form of ‘farms’, which were fixed rental payments for leases to use the King’s land for agriculture. These farms were fixed by custom in nominal terms, whereas the King’s expenditures were not. The King’s finances were unhedged.
In fairness to the monarchy, there was not an enormous amount that could be done about this. There was obviously no CPI(H) to which the leasehold rents could be indexed. The UK’s statistical challenges have a long history.
The preferred way of hedging the risk was to kick the leaseholders off the land, and bring it into direct demesne management.[5] This is what the barons themselves had been doing with their own land holdings. By taking it into demesne control, instead of receiving a fixed nominal rent, the lord of the manor could take receipt of the real output of the land, which could be consumed, traded, or sold for silver at the going spot price. The consequence was that the richer the baron, the more land he had to exploit, and the greater his potential profits.
The effect was to create a massively wealthy elite of oligarchs, now breaking free both of the middling ranks of the gentry at one end, and of the hard-pressed King (or public sector) at the other. In all of this, the option of demesne management was infeasible for the King, likely because it would have involved destabilising relations with the administrative class of ‘sheriffs’ and other royal officials upon whom the King’s political stability depended.[6]
Causes of the inflation
Forget royal infighting, wars or the whiff of revolution, it is inflation that really sets the pulses of central bankers racing. And for good reason because closer inspection suggests that inflation may have been a significant catalyst to Magna Carta.
Historians estimate that prices were rising sharply in the early 1200s. The prices of agricultural goods, including wheat and oxen, probably doubled in that period.[7] Evidence suggests that prices of linen, wax, lead and even palfreys – the Toyota Prius of medieval horses – were also rising rapidly.
Wages were rising as well – and to a greater extent than could have just been the consequence of medieval real-wage resistance. King John was paying his knights almost three times as much as Henry II (even though they weren’t as productive on the battlefield).[8] The daily rate for foot-soldiers had doubled. And limited evidence suggests the wages of skilled labourers on the crown estates probably increased by a similar proportion.[9]
With pay growth approaching 20% a year, wages really were fizzing![10]
The underlying causes of this inflation are debated among historians, but the most convincing argument is that the inflation was a monetary one, albeit with a twist. Not surprisingly, the quantitative information on the thirteenth century money supply is of very poor quality, imputed, as it has been, from archaeological finds of cash hoards.[11]
Latimer notes that “…between the middle of the twelfth century and the middle of the thirteenth century there was an enormous increase in the quantity of silver coins in England.” As well as the possibility of a general increase in the European silver supply (especially with the opening up of the Harz silver mines in eastern Germany), it is likely that silver inflows to England in particular were boosted as the counterpart to a sizeable private trade surplus – probably resulting, especially, from the success of the wool trade with Flanders. Over several decades, these silver inflows were likely to have much more than offset the ‘public sector deficit’ as silver leaked out to pay for the protection of Normandy as well as the occasional trip to the Holy Land. As a result, the balance of payments was probably in surplus for years, with the consequent increase in the silver money supply going unsterilised. Even to a thirteenth century Englishman, global monetary conditions mattered.
Would Britain’s constitutional history have been different had King John lamented: A Central Bank! A Central Bank! My Kingdom for a Central Bank!?
He needed one because other factors reinforced monetary developments, including the usual suspect - financial innovation. Specifically, developments in the common law made land an increasingly liquid asset, and therefore one capable for the first time of being used as a store of wealth.[12]
This set a medieval financial accelerator in train (about 750 years before Ben Bernanke coined the term)[13] by providing an alternative to storing one’s wealth in silver coin (prone to being whisked away by the King). This led to a reduction in the demand for silver money balances. An increase in money velocity would have followed and with it, all else being equal, price inflation until the transactions demand for silver had risen sufficiently to equal its supply. At the very least, the existence of an alternative store of wealth provided an environment in which money velocity could take off, were it to be nudged in that direction.
One possible nudge was the anticipation of the re-coinage of 1204.[14] Re-coinages were good for the King because he benefitted from the seigniorage of the re-minting fee. They were bad for cash holders both because of the re-minting fee and because they had to exchange their clipped coins for what they were actually worth, rather than their face value (a medieval haircut – some of which were appalling). Consequently, there was a strong incentive not to be the one holding the old-issue coins when the music stopped.[15]
So to sum up: a fiscal squeeze exacerbated by accelerating inflation, combined with monarchical ambition and incompetence to stretch and then break relations with the barons.
2. Constitutional significance
In that context, Magna Carta was a desperate (and probably disingenuous) attempt at a peace treaty that failed almost immediately.
Brokered by the Church, and issued by King John in June 1215, the Charter sought to placate the disgruntled barons. It is doubtful that John ever intended to uphold his side of the bargain, with all the constraints on his authority that this implied. Indeed, within a few months of its agreement, by the end of August 1215, John had convinced Pope Innocent III to annul the Charter on the grounds that it had been issued under duress.[16] The 1215 Magna Carta was never enacted, and England slipped into the First Barons’ War.
Charters of this type were not uncommon at that time. It had been fairly routine, in fact, for English kings to attempt to curry favour with the nobles upon whom the stability of their realm depended by rubbishing the reputations of their predecessors and issuing ‘coronation charters’ that demonstrated how virtuous and peace-loving they were by comparison. It was also fairly routine for kings to renege on the promises in those charters, creating fertile ground to begin the cycle anew.[17]
What was novel about Magna Carta was that: (a) it was longer and more detailed than its predecessors; and (b) it was issued not at John’s coronation, but under compulsion from a true political opposition, sixteen years into his reign and evidentially too late to serve its purpose.[18]
This brings a second observation. Obnoxious and tyrannical as he might have been, King John was not solely to blame for the aristocratic discontent that led to Magna Carta. His predecessors had reneged on their promises, mismanaged the realm and imperilled its finances. John’s administrative and military incompetence were merely the straws that broke the camel’s back.
If Magna Carta was such a product of its time, how did it become to be so venerated? And once we cut through the legend, what is its significance for economic governance today?
The revisionist interpretation of Magna Carta as a timeless statement of natural rights and liberties became imprinted onto the minds of the English-speaking world only in the 17th century. In large part, this was due to the work of Edward Coke. As well as being an enormously influential jurist, Coke was also the author of popular English legal textbooks that exported his views around the world. Coke resurrected the long-forgotten Magna Carta from 400 years of obscurity by appealing to its spirit in order to resist the absolutist tendencies of the Stuart Kings James I and his son Charles I – themselves inspired by the continental European model of monarchic divine-right. The Charter, Coke argued, could trace its lineage from an ancient constitution that harked back not just to the time of pre-Norman King Edward the Confessor, but to King Arthur himself (!): an ancient constitution that was now being imperilled – and with it the Englishman’s rightful way of life – by the tyrannical behaviour of the Stuarts.
Despite the efforts of Coke and others, Charles I’s rejection of all enterprise to constrain his authority led to the English Civil War and to the king’s beheading in 1649. Meanwhile, Coke’s unstoppable Magna Carta redux had been set in motion.
In contradiction to their behaviour at home, James and Charles had been busily granting royal charters promising the liberties of Englishmen to the American colonists. Coke himself had been involved in the drafting of the first charter of the Virginia Company in 1606, and similar English liberties were extended in the charters of Massachusetts, Maryland, Connecticut, Rhode Island and Carolina over the next sixty years.
Some have argued that references to Magna Carta, however irrelevant its provisions might by then have been, were used as a way of ‘drumming up’ New World settlers. To this day, 25 US States have extracts from Magna Carta on their statute books; a further 17 have the full text. Goodness knows how the latter intend to enforce the removal of “[a]ll fish-weirs … from the Thames, the Medway, and throughout the whole of England, except on the sea coast” (Clause 33). Of course, sometimes American extraterritoriality literally knows no bounds.
Coke’s romantic resurrection of Magna Carta transformed it into part of the backdrop to the American Revolution, with his influence clearly evident in the drafting of the US Constitution.
***
We have seen how the economic forces and political developments of the time played a crucial part in the mounting hostilities between King John and the barons that led to Magna Carta and First Barons’ War. Given that background, it is not as shocking as it first seems that Magna Carta is very largely taken up with the parochial interests of the rich. It is dominated by three basic themes: taxes; abuses of the ‘judicial system’ with the aim of raising revenue; and the protection of the barons’ mercantile interests.
Given how irrelevant those specific concerns now seem, it is hardly surprising that almost all of the Charter’s clauses that survived the 1225 re-issue (and therefore made it into the law in the first place) have since been repealed. In fact, only four clauses of the original 66 remain. These stand out as different in character from the others. They are much more general, universal and timeless. They are:
Clause 1: Freedom for the Church.
Clause 13: Protection for the ‘ancient liberties’ of the City of London.
Clause 39: No wrongful imprisonment. Perhaps the most famous clause. “No free man shall be seized or imprisoned, or stripped of his rights or possessions, or outlawed or exiled, or deprived of his standing in any way, nor will we proceed with force against him, or send others to do so, except by the lawful judgment of his equals or by the law of the land.”
Clause 40: Justice is not for sale.
Added to that, the spirit of Clause 12 of the 1215 Magna Carta (dropped from all later reissues), that “no ‘scutage’ or ‘aid’ may be levied in our kingdom without its general consent…”, is clearly what would later become ‘no taxation without representation’: to establish a council (the embryonic embodiment of what would later become Parliament) to agree whatever new taxes the King might demand.
Whatever their purpose at the time, the more universal clauses that remain on the statute book certainly resonate today. They in effect encompass the idea of the rule of law and of due process as a means to ensure justice. It is tempting, therefore, to think of these clauses as being the enduring legacy of Magna Carta, while at the same time allowing ourselves to patronise the juxtaposition of these apparently fundamental principles alongside so much antiquated gibberish about fish-weirs, the obligation to construct bridges, and the theft of wood for building castles.
This would, I think, be a mistake. The specificity of the clauses animates the general principles. It is because they are detailed and targeted at the concerns of the time that they are a genuine attempt to place a boundary on the authority of the King, rather than relying on vague platitudes.[19]
Magna Carta was nowhere near the first attempt to encapsulate ideas of justice and good government, nor was it the last. Indeed, it was a spectacularly unsuccessful attempt – and it was anyway concerned only with the interests of a very small segment of society. But, largely because King John’s heirs were forced into a tight corner and therefore obliged to reissue the charter again and again after 1215 (in 1216, 1217, 1225, 1234, 1253, 1265, 1297 and 1300, to cite only the more famous reissues), it is Magna Carta that has become the icon of the principle that the exercise of authority requires permission from those subject to that authority – and that, once granted, this permission can just as easily be withdrawn.
At its most idealised, Magna Carta makes clear that power derives from the people and constrains the authority of the state. The state can in turn devolve power – to regions – and to independent bodies. But these bodies can never forget from where their power came or to whom they are responsible. Their authority is constrained to that necessary to pursue specific objectives and they are accountable to the people for their performance.
3. Monetary policy outlook
The Bank’s current Monetary Policy framework embodies these principles.
It wasn’t always the case. The Bank of England was brought into public ownership in 1946. As former Governor Eddie George remarked, for the half century that followed “the Bank operated under legislation which, remarkably, did not attempt to define our objectives or functions.” They were, instead, “assumed to carry over from [the Bank’s] earlier long history.”[20] In that regard, the Bank’s ‘constitution’ resembled that of the United Kingdom more broadly, comprising a rich history of law, principle and convention.
All changed with the passing of the Bank of England Act in 1998, which made specific “provision about the constitution, regulation, financial arrangements and functions of the Bank.” The Act brought great clarity to the Bank’s responsibilities and granted independence to the Bank for the operation of monetary policy. In delegating authority to an independent body in this way, the Act ensured the Bank would operate under what Mervyn King described as ‘constrained’ rather than ‘unfettered’ discretion. The Bank would be accountable to Parliament for operating the instruments of monetary policy to achieve the objectives of monetary policy, which would be determined by the Government.[21]
The operational independence of the Bank of England is an example of power flowing from the people via Parliament within carefully circumscribed limits. Independence in turn demands accountability in order that the Bank commands the legitimacy it needs to fulfil its mission. By publishing its analysis, giving testimony, and delivering speeches, the Bank explains how it is exercising its powers to achieve its clearly defined policy Remits.
To illustrate these points, I will conclude with some reflections on monetary policy. Our objective, given to us by Parliament, is to maintain price stability and, subject to that, to support the economic policy of Her Majesty’s Government, including its objectives for growth and employment. Our Remit builds in important accountability and transparency mechanisms. One of which is the requirement for the Governor to write an open letter to the Chancellor if inflation moves away from its 2 per cent target by more than one percentage point.
Inflation developments
I am in the middle of a likely sequence of such open letters – I have another one due next month – on account of the record low inflation the UK is experiencing this year, currently at zero per cent. Such letters must explain, among other things, why inflation has deviated from target and what policy actions the Monetary Policy Committee (MPC) is taking in response.
The ‘why’ is straightforward. The bulk of the shortfall of inflation below target can be explained by the sharp fall in the prices of commodities and other imported goods since last year.
Of these, the single most important factor has been the steep drop in energy prices globally. The rise in the value of sterling has also played an important role in lowering non-energy import prices, which have fallen over the past twelve months. The sum total of these effects has been to drag inflation below target by around 1½ percentage points. This temporary period of below-target inflation has provided a welcome boost to real household income.
Inflation looking ahead
The MPC’s intention is to return inflation to target in a sustainable manner within two years. That means setting Bank Rate to eliminate the remaining slack in the economy, bringing about the sustained increase in costs necessary to achieve overall inflation of 2%.
I expect that this will involve raising Bank Rate over the next three years from its current all-time low of ½ per cent. The need for Bank Rate to rise reflects the momentum in the economy and a gradual firming of underlying inflationary pressures – a firming that will become more apparent as the effects of past commodity price falls drop out of the annual inflation rate around the end of the year. It also reflects the lags in monetary policy, given that the peak impact on inflation of a given adjustment in interest rates is likely to materialise around 18-24 months after the change.
As the economy evolves, different factors will become worthy of particular attention in informing the timing, pace and degree of likely Bank Rate increases. At the current juncture, three stand out.
First are the prospects that sustained momentum in economic activity will wring out any remaining slack. This will require sustained growth above its past average of around 0.6 per cent per quarter. [22]
Even though the current recovery has been the slowest since the Great Depression, taking around 1½ years longer to regain lost ground than it did following the recession of the 1930s, the signs are encouraging. Looking through the blip in the first quarter, the economy has now been growing above trend for a year and unemployment has fallen sharply over the past two. Consumer confidence is around its highest level for over a decade. Businesses investment intentions are solid. Momentum in the housing market is showing signs of returning.[23] Survey data point to continued momentum in real activity over the remainder of this year.
To be sure, the international risks to the growth outlook remain. The situation in Greece is fluid, and the on-going slowdown in China could prove more significant. But on balance we can expect the global economy to proceed at a solid, not spectacular, pace.[24]
Second, domestic costs need to continue to firm. After a period of particularly weak wage growth, which reflected a marked expansion in labour supply that is now largely absorbed, wage growth is picking up.[25] The recent growth in wages has been stronger than we had expected in May, though most of the upside news was in bonuses, which are a less reliable guide to firms’ future labour costs.[26]
At a minimum, when taken together with survey indicators that continue to point to solid pay growth for new recruits, recent data give welcome reassurance that the risks associated with a deflationary mindset in the labour market have likely fallen significantly.
Further positive wage developments should be supported by a continued tightening in the labour market. Job-to-job flows remain around post-crisis highs and the ratio of vacancies to unemployment is now back to its pre-crisis average.
However, what matters for inflation is not wage growth in isolation but wage growth relative to productivity. Put simply, firms are less likely to raise their prices if higher wages reflect more output per hour worked. Along with faster wage growth, there have been signs of faster productivity growth since the turn of the year. This may well mean firms’ unit labour costs have not picked up quite to the degree we had expected in our May Inflation Report. It’s too early to be definitive. Weighing past disappointments and recent indications of a pick-up, it is prudent to recognise that two-sided risks to productivity growth remain.
What is clear is that to return inflation to target, growth in labour costs must pick up further from their current rate of less than one per cent. The extent needed depends on what is happening to other costs. In the decade prior to the crisis, labour costs grew by around 2½ per cent each year on average, with wages and salaries growing at around 4¾ per cent and productivity at 2¼ per cent. Inflation averaged 2 per cent,[27] however, in part because import prices rose only by around ¼ per cent each year at the same time.
The possibility that history might repeat itself points to a third important consideration: the need to monitor developments in firms’ costs other than labour. The sum of these is evident in so-called ‘core’ inflation, which are measures of prices that strip out the most volatile determinants of inflation, like energy prices, revealing more persistent trends. In an open economy like the United Kingdom’s, those factors include import prices, which are affected by movements in the value of sterling, and which, on past experience, can take a considerable time to pass through to core inflation.[28]
Over the past few years, core inflation has been particularly subdued, and it remains less than one per cent. We need to see increases in core inflation to have a reasonable expectation that, in the absence of further shocks, overall CPI inflation will return to 2 per cent within the MPC’s stated objective of two years.
Policy strategy
Delivering the growth in activity, the rise in domestic costs and the firming in core inflation measures necessary to return inflation to target requires monetary policy to be set appropriately both now and prospectively. In this regard, one concern has been the constraint imposed on monetary policy by the effective lower bound on policy rates.
In my view, with the healing of the financial sector and the lessening of some of the headwinds facing the economy, that concern has become less pressing with the passage of time. As I made clear in my first open letter in February, were downside risks to inflation to materialise the MPC could decide either to expand the Asset Purchase Facility or to cut Bank Rate further towards zero from its current level of ½ per cent.[29] In the current circumstances there is no need to wait to raise rates because of a risk management approach and run the risk of inflation overshooting target.
At the same time, the timing and pace of prospective interest rate increases need to be put into perspective. Headwinds to growth and inflation remain. Growth in the parts of the global economy that matter most to the UK is running ¾ percentage points below its historic average. Sterling has appreciated around 18 per cent over the past two years and around 7 per cent since the turn of the year. This will exert a drag on inflation both through lowering import costs and by lowering world demand for UK goods. UK fiscal policy is about to tighten significantly. The average annual reduction in the cyclically-adjusted budget deficit is projected by the OBR to increase from around ½ per cent of GDP over the past two years to around 1 per cent of GDP over the next two – and the IMF expects the UK to undergo the largest fiscal adjustment of any major advanced economy over the next five years.[30]
Taken together, these factors suggest that the ‘equilibrium’ real rate of interest – the rate needed to keep the economy operating at potential and inflation on target – which was sharply negative during the crisis, will continue to be lower than on average in the past. It also seems likely that the equilibrium interest rate will move only slowly back up towards historically more ‘normal’ levels. Everything else equal, that suggests a prospective tightening cycle that, once it starts, will be longer and shallower than those of the past. In other words, we expect Bank Rate increases to be gradual, and limited to a level below past averages.
What does that actually mean?
The Bank of England is around half a millennium younger than Magna Carta. To put the limited and gradual expectation in historical context, short term interest rates have averaged around 4½ per cent since around the Bank’s inception three centuries ago,[31] the same average as during the pre-crisis period when inflation was at target. The average pace of tightening since the adoption of inflation targeting in 1992 was around 50 basis points per quarter.
It would not seem unreasonable to me to expect that once normalisation begins, interest rate increases would proceed slowly and rise to a level in the medium term that is perhaps about half as high as historical averages. In my view, the decision as to when to start such a process of adjustment will likely come into sharper relief around the turn of this year.
That said, the path is much more important than the precise timing of the first rate increase. And I am conscious of several important considerations which mean the actual path almost certainly will not be mechanical, linear or pre-determined. First and foremost, shocks to the economy could easily adjust the timing and magnitude of interest rate increases. Second, the largest cumulative tightening in the UK since inflation targeting was adopted was 1 ½ percentage points, compared to an average cycle of 3 percentage points for the US Federal Reserve over the same period. This likely reflects in part the greater sensitivity of UK household balances sheets in the medium term to floating interest rates, something that could be particularly relevant in our still heavily indebted post-crisis economy. Over a half of UK mortgagors would pay higher rates in a year’s time, and close to three-quarters of mortgagors in two years’ time, were interest rates to evolve according to current market rate expectations. That is in stark contrast to the US, where even over a two-year period, less than 10 per cent mortgages would be affected directly by a change in rates. We will learn more about the importance of these sensitivities as interest rates increase. Third, developments in the exchange rate have been important for UK inflation and activity, and in particular we have experienced persistent exchange rate pass-through to headline inflation.[32] This risk is particularly relevant at present when the monetary policy stance of our largest trading partner is diverging with ours.
Most fundamentally, there are broader macroeconomic considerations, particularly the UK’s large external imbalances. With the largest current account deficit in the advanced world, the right policy mix leans towards tighter fiscal, more accommodative monetary and tighter macroprudential policies.[33]
Given these considerations, the MPC will have to feel its way as it goes, monitoring a wide range of indicators and adjusting the pace and degree of Bank Rate as it learns about the effects of higher interest rates on the economy. There is, in fact, a wide distribution of possible outcomes around any expected path for Bank Rate, reflecting the inevitability that the economy will be buffeted by shocks and that monetary policy will have to adjust accordingly.
After all, as the story of Magna Carta shows, history rarely proceeds in a straight line… why should monetary policy?
Federal Reserve Chair Janet L. Yellen Presents Semiannual Monetary Policy Report to the Congress
Chairman Hensarling, Ranking Member Waters, and members of the Committee, I am pleased to present the Federal Reserve’s semiannual Monetary Policy Report to the Congress. In my remarks today, I will discuss the current economic situation and outlook before turning to monetary policy.
Current Economic Situation and Outlook
Since my appearance before this Committee in February, the economy has made further progress toward the Federal Reserve’s objective of maximum employment, while inflation has continued to run below the level that the Federal Open Market Committee (FOMC) judges to be most consistent over the longer run with the Federal Reserve’s statutory mandate to promote maximum employment and price stability.
In the labor market, the unemployment rate now stands at 5.3 percent, slightly below its level at the end of last year and down more than 4-1/2 percentage points from its 10 percent peak in late 2009. Meanwhile, monthly gains in nonfarm payroll employment averaged about 210,000 over the first half of this year, somewhat less than the robust 260,000 average seen in 2014 but still sufficient to bring the total increase in employment since its trough to more than 12 million jobs. Other measures of job market health are also trending in the right direction, with noticeable declines over the past year in the number of people suffering long-term unemployment and in the numbers working part time who would prefer full-time employment. However, these measures–as well as the unemployment rate–continue to indicate that there is still some slack in labor markets. For example, too many people are not searching for a job but would likely do so if the labor market was stronger. And, although there are tentative signs that wage growth has picked up, it continues to be relatively subdued, consistent with other indications of slack. Thus, while labor market conditions have improved substantially, they are, in the FOMC’s judgment, not yet consistent with maximum employment.
Even as the labor market was improving, domestic spending and production softened notably during the first half of this year. Real gross domestic product (GDP) is now estimated to have been little changed in the first quarter after having risen at an average annual rate of 3-1/2 percent over the second half of last year, and industrial production has declined a bit, on balance, since the turn of the year. While these developments bear watching, some of this sluggishness seems to be the result of transitory factors, including unusually severe winter weather, labor disruptions at West Coast ports, and statistical noise. The available data suggest a moderate pace of GDP growth in the second quarter as these influences dissipate. Notably, consumer spending has picked up, and sales of motor vehicles in May and June were strong, suggesting that many households have both the wherewithal and the confidence to purchase big-ticket items. In addition, homebuilding has picked up somewhat lately, although the demand for housing is still being restrained by limited availability of mortgage loans to many potential homebuyers. Business investment has been soft this year, partly reflecting the plunge in oil drilling. And net exports are being held down by weak economic growth in several of our major trading partners and the appreciation of the dollar.
Looking forward, prospects are favorable for further improvement in the U.S. labor market and the economy more broadly. Low oil prices and ongoing employment gains should continue to bolster consumer spending, financial conditions generally remain supportive of growth, and the highly accommodative monetary policies abroad should work to strengthen global growth. In addition, some of the headwinds restraining economic growth, including the effects of dollar appreciation on net exports and the effect of lower oil prices on capital spending, should diminish over time. As a result, the FOMC expects U.S. GDP growth to strengthen over the remainder of this year and the unemployment rate to decline gradually.
As always, however, there are some uncertainties in the economic outlook. Foreign developments, in particular, pose some risks to U.S. growth. Most notably, although the recovery in the euro area appears to have gained a firmer footing, the situation in Greece remains difficult. And China continues to grapple with the challenges posed by high debt, weak property markets, and volatile financial conditions. But economic growth abroad could also pick up more quickly than observers generally anticipate, providing additional support for U.S. economic activity. The U.S. economy also might snap back more quickly as the transitory influences holding down first-half growth fade and the boost to consumer spending from low oil prices shows through more definitively.
As I noted earlier, inflation continues to run below the Committee’s 2 percent objective, with the personal consumption expenditures (PCE) price index up only 1/4 percent over the 12 months ending in May and the core index, which excludes the volatile food and energy components, up only 1-1/4 percent over the same period. To a significant extent, the recent low readings on total PCE inflation reflect influences that are likely to be transitory, particularly the earlier steep declines in oil prices and in the prices of non-energy imported goods. Indeed, energy prices appear to have stabilized recently.
Although monthly inflation readings have firmed lately, the 12-month change in the PCE price index is likely to remain near its recent low level in the near term. My colleagues and I continue to expect that as the effects of these transitory factors dissipate and as the labor market improves further, inflation will move gradually back toward our 2 percent objective over the medium term. Market-based measures of inflation compensation remain low–although they have risen some from their levels earlier this year–and survey-based measures of longer-term inflation expectations have remained stable. The Committee will continue to monitor inflation developments carefully.
Monetary Policy
Regarding monetary policy, the FOMC conducts policy to promote maximum employment and price stability, as required by our statutory mandate from the Congress. Given the economic situation that I just described, the Committee has judged that a high degree of monetary policy accommodation remains appropriate. Consistent with that assessment, we have continued to maintain the target range for the federal funds rate at 0 to 1/4 percent and have kept the Federal Reserve’s holdings of longer-term securities at their current elevated level to help maintain accommodative financial conditions.
In its most recent statement, the FOMC again noted that it judged it would be appropriate to raise the target range for the federal funds rate when it has seen further improvement in the labor market and is reasonably confident that inflation will move back to its 2 percent objective over the medium term. The Committee will determine the timing of the initial increase in the federal funds rate on a meeting-by-meeting basis, depending on its assessment of realized and expected progress toward its objectives of maximum employment and 2 percent inflation. If the economy evolves as we expect, economic conditions likely would make it appropriate at some point this year to raise the federal funds rate target, thereby beginning to normalize the stance of monetary policy. Indeed, most participants in June projected that an increase in the federal funds target range would likely become appropriate before year-end. But let me emphasize again that these are projections based on the anticipated path of the economy, not statements of intent to raise rates at any particular time.
A decision by the Committee to raise its target range for the federal funds rate will signal how much progress the economy has made in healing from the trauma of the financial crisis. That said, the importance of the initial step to raise the federal funds rate target should not be overemphasized. What matters for financial conditions and the broader economy is the entire expected path of interest rates, not any particular move, including the initial increase, in the federal funds rate. Indeed, the stance of monetary policy will likely remain highly accommodative for quite some time after the first increase in the federal funds rate in order to support continued progress toward our objectives of maximum employment and 2 percent inflation. In the projections prepared for our June meeting, most FOMC participants anticipated that economic conditions would evolve over time in a way that will warrant gradual increases in the federal funds rate as the headwinds that still restrain real activity continue to diminish and inflation rises. Of course, if the expansion proves to be more vigorous than currently anticipated and inflation moves higher than expected, then the appropriate path would likely follow a higher and steeper trajectory; conversely, if conditions were to prove weaker, then the appropriate trajectory would be lower and less steep than currently projected. As always, we will regularly reassess what level of the federal funds rate is consistent with achieving and maintaining the Committee’s dual mandate.
I would also like to note that the Federal Reserve has continued to refine its operational plans pertaining to the deployment of our various policy tools when the Committee judges it appropriate to begin normalizing the stance of policy. Last fall, the Committee issued a detailed statement concerning its plans for policy normalization and, over the past few months, we have announced a number of additional details regarding the approach the Committee intends to use when it decides to raise the target range for the federal funds rate.
Federal Reserve Transparency and Accountability
These statements pertaining to policy normalization constitute recent examples of the many steps the Federal Reserve has taken over the years to improve our public communications concerning monetary policy. As this Committee well knows, the Board has for many years delivered an extensive report on monetary policy and economic developments at semiannual hearings such as this one. And the FOMC has long announced its monetary policy decisions by issuing statements shortly after its meetings, followed by minutes of its meetings with a full account of policy discussions and, with an appropriate lag, complete meeting transcripts. Innovations in recent years have included quarterly press conferences and the quarterly release of FOMC participants’ projections for economic growth, unemployment, inflation, and the appropriate path for the Committee’s interest rate target. In addition, the Committee adopted a statement in 2012 concerning its longer-run goals and monetary policy strategy that included a specific 2 percent longer-run objective for inflation and a commitment to follow a balanced approach in pursuing our mandated goals.
Transparency concerning the Federal Reserve’s conduct of monetary policy is desirable because better public understanding enhances the effectiveness of policy. More important, however, is that transparent communications reflect the Federal Reserve’s commitment to accountability within our democratic system of government. Our various communications tools are important means of implementing monetary policy and have many technical elements. Each step forward in our communications practices has been taken with the goal of enhancing the effectiveness of monetary policy and avoiding unintended consequences. Effective communication is also crucial to ensuring that the Federal Reserve remains accountable, but measures that affect the ability of policymakers to make decisions about monetary policy free of short-term political pressure, in the name of transparency, should be avoided.
The Federal Reserve ranks among the most transparent central banks. We publish a summary of our balance sheet every week. Our financial statements are audited annually by an outside auditor and made public. Every security we hold is listed on the website of the Federal Reserve Bank of New York. And, in conformance with the Dodd-Frank Act, transaction-level data on all of our lending–including the identity of borrowers and the amounts borrowed–are published with a two-year lag. Efforts to further increase transparency, no matter how well intentioned, must avoid unintended consequences that could undermine the Federal Reserve’s ability to make policy in the long-run best interest of American families and businesses.
Summary
In sum, since the February 2015 Monetary Policy Report, we have seen, despite the soft patch in economic activity in the first quarter, that the labor market has continued to show progress toward our objective of maximum employment. Inflation has continued to run below our longer-run objective, but we believe transitory factors have played a major role. We continue to anticipate that it will be appropriate to raise the target range for the federal funds rate when the Committee has seen further improvement in the labor market and is reasonably confident that inflation will move back to its 2 percent objective over the medium term. As always, the Federal Reserve remains committed to employing its tools to best promote the attainment of its dual mandate.
Thank you.
International Financial Institutions Announce $400 Billion to Achieve Sustainable Development Goals
WASHINGTON, —The multilateral development banks (MDBs) and IMF today signaled plans to extend more than $400 billion in financing over the next three years and vowed to work more closely with private and public sector partners to help mobilize the resources needed to meet the historic challenge of achieving the Sustainable Development Goals (SDGs).
The institutions—the African Development Bank, Asian Development Bank, European Bank for Reconstruction and Development, European Investment Bank, Inter-American Development Bank, World Bank Group (referred to as the MDBs), and the International Monetary Fund—announced their plans in the lead-up to the Third International Conference on Financing for Development in Addis Ababa, July 13-16.
The SDGs are ambitious and demand equal ambition in using the “billions” of dollars in current flows of official development assistance (ODA) and all available resources to attract, leverage and mobilize “trillions” in investments of all kinds—public and private, national and global.
ODA, estimated at $135 billion a year, provides a fundamental source of financing, especially in the poorest and most fragile countries. But more is needed. Investment needs in infrastructure alone reach up to $1.5 trillion a year in emerging and developing countries. Meeting the staggering but achievable needs of the SDG agenda requires everyone to make the best use of each dollar from every source, and draw in and increase public and private investment. The MDBs—the engines of development finance—are looking to a range of options for scaling up.
MDB development finance has grown from $50 billion in 2001 to $127 billion in 2015. For each dollar invested by its shareholders, MDBs are able to commit $2-5 in new financing each year. The MDBs’ own direct private sector investments have increased fourfold over this period. They mobilize an additional $2-5 in private investment for every dollar they invest directly in private sector operations. The vow to increase their contribution to more than $400 billion over the next three years reflects in part efforts to make even better use of their balance sheets.
Additional steps to leverage more resources include the development of new approaches and tools to help developing countries play a stronger role in harnessing national resources. The MDBs and the IMF are partnering with countries on, for example, the introduction of a new toolkit to assess and improve tax policies and expanding instruments such as e-procurement to achieve better government spending.
Increasing external resource flows to developing countries for investment is essential to achieving the SDGs—but these flows can be expected to materialize only in circumstances where countries have coherent development strategies consistent with maintaining macroeconomic stability while also ensuring the delivery of key public sector services and a business environment supportive of growth.
Through their policy advice and technical assistance, the MDBs and IMF support countries in designing economic policies to achieve these objectives; through MDB policy support loans and IMF-supported programs, these institutions provide general financial support towards meeting budgetary and balance of payments needs.
The private sector is playing an increasing role in financing goods, services and infrastructure. The MDBs are committed to engaging differently with private sector partners on a wide range of interventions, including connecting investors with opportunities, helping countries make investments more attractive, and building local financial markets.
The MDBs are also partnering with others to develop innovative financing approaches to support global needs, such as health and climate, building on extensive work already underway.
Quotes from Heads of Multilateral Development Banks
Donald Kaberuka, President, AfDB
“2015 is a critical year in charting the development future of Africa – the continent that still has the greatest development needs, and the continent that presents the greatest opportunity – for itself and for the world. The level of collaboration among the MDBs in preparing the Financing for Development conference has been unprecedented, in coming up with innovative solutions to scale up development financing. One such is sovereign exposure exchange, where the African Development Bank is working closely with the World Bank and the Inter-American Development Bank to stretch our balance sheet so that we can scale up lending to our clients in North Africa.”
Takehiko Nakao, President, ADB
“This is a critical time for governments, the private sector and MDBs to come together to tackle the fundamental development challenges of our time. For its part, ADB has already taken the groundbreaking step to strengthen its lending capacity. By merging concessional and non-concessional lending windows ADB will be able to increase its financing to member countries by 50 percent. With its support to the private sector, including the recent establishment of the Office of Public-Private Partnerships, ADB will intensify its efforts to unlock the enormous private resources available in the Asia and Pacific region for development financing.”
Werner Hoyer, President, EIB
“Sharing technical and financial experience is crucial to successfully tackle climate change and ensure that sustainable development can benefit future generations. The European Investment Bank has worked closely with the other MDBs for many years to strengthen climate action, infrastructure and private sector investment that improves lives around the world. We share the firm commitment of the world’s public banks to further support investment in the years ahead that contributes to achieving the SDG’s by unlocking green growth, supporting transition to cleaner energy and fostering innovation.”
Suma Chakrabarti, President, EBRD
“Scaling up our impact and investment from all sources for sustainable development means we must marshal policy advice and knowledge along with financing. At EBRD we aim to galvanise private finance to support investments, especially in infrastructure, including sustainable energy and the fight against climate change. Crucially, in order to successfully attract private investment to serve these public goals we also advise on policies that improve the regulatory framework and strengthen institutions.”
Luis Alberto Moreno, President, IDB
“It’s essential for multilateral banks and the IMF to work closely with each other, as well as with governments and the private sector to mobilize the additional resources needed to achieve the Sustainable Development Goals. We all share the same goals, which include reducing poverty and inequality, promoting economic growth and productivity that creates well-paid jobs, improving social and physical infrastructure, pursuing sustainable energy policies, ensuring food security and protecting biodiversity, among other pressing challenges. The IDB’s recent decision to create a separate entity to deal exclusively with our private sector portfolio shows our commitment to tapping all possible sources of development funding.”
Christine Lagarde, Managing Director, IMF
“This year marks a once-in-a-generation opportunity for global development. The only way to seize it is through partnership. To go far, we must go together. The IMF—with its global membership and mandate to promote economic growth and stability—is a committed partner. In this pivotal year, we have targeted areas where providing additional support will have strong payoffs: we have just increased access to all our concessional loan facilities by a full 50 percent; we are set to expand our large program of support to developing countries in mobilizing domestic tax revenues; and we will deepen our policy engagement with countries on key development issues such as addressing infrastructure needs and promoting equity and inclusion.
Jim Yong Kim, President, World Bank Group
“We must cast away the stereotypes of aid and think about development differently. It’s about creating opportunity for all, giving people an equal chance to succeed in life, and preparing the world to deal with the challenges of climate change and the next pandemic. We need trillions, not billions, of dollars to accomplish these goals, and the money will come from many sources: developing countries, private sector investment, donors, and international financial institutions. By working together, we can help people build better lives with good education, quality health care, clean water, and proper sanitation. Those investments in people will help end extreme poverty in just 15 years.”
World Bank and the IMF Launch Joint Initiative to Support Developing Countries in Strengthening Tax Systems
WASHINGTON, – The World Bank and IMF are launching a new initiative to help developing countries strengthen their tax systems. Analysis suggests that many lower-income countries have the potential to increase their tax ratios by at least 2–4 percent of GDP, without compromising fairness or growth. Raising additional revenues will allow developing countries to fill financing gaps and to promote development.
The announcement comes ahead of the “Financing for Development” conference in Addis, Ethiopia next week, at which heads of state, CSOs, multilateral institutions and private sector representatives will discuss how to scale up finances to meet the Sustainable Development Goals (SDGs).
“A strong revenue base is imperative if developing countries are to be able to finance the spending they need on public services, social support and infrastructure,” said IMF Managing Director Christine Lagarde. “But experience shows that with well-targeted external technical support and sufficient political will, it can be done.”
“We very much want to help developing countries raise more revenues through taxes because this can lead to more children receiving a good education and more families having access to quality health care,” said World Bank Group President Jim Yong Kim. “If everyone pays their fair share developing countries can close their financing gaps and promote inclusive growth.”
Responding to country demands, the IMF/World Bank initiative has two pillars: deepening the dialogue with developing countries on international tax issues, aiming to help increase their voice in the international debate on tax rules and cooperation; and developing improved diagnostic tools to help member countries evaluate and strengthen their tax policies. This builds on the Bank’s current tax programs in over 48 developing countries and the Fund’s tax related technical assistance projects in over 120 countries.
By further leveraging their collective expertise, the Bank and Fund aim to play a fuller role in helping all of their member countries achieve the ambitious goals that the world will be setting for itself later this year in New York.
Bringing the voice and interests of developing countries, particularly those too small to play a role at the G-20 level, more fully into the debate on international tax policy issues is a key priority for the Bank and the Fund. The initiative will deepen the institutions’ ongoing collaboration with developing countries to identify key international tax policy concerns and potential solutions, both at the country level and in the context of the continuing international dialogue.
The institutions also plan to strengthen their diagnostic tools, developing new methodologies where needed, to enable member countries to identify priority tax reforms and design the requisite support for their implementation. This effort would complement the launch of the Tax Administration Diagnostic Assessment Tool (TADAT) in November.
The Bank and the Fund will continue to work in close collaboration with other development partners, including the OECD, in expanding their work in the tax area.
Eurozone Summit Strikes Deal Over Greece Debt Crisis After Seventeen Hours of Marathon Talks
The Euro Summit stresses the crucial need to rebuild trust with the Greek authorities as a prerequisite for a possible future agreement on a new ESM programme. In this context, the ownership by the Greek authorities is key, and successful implementation should follow policy commitments.
A euro area Member State requesting financial assistance from the ESM is expected to address, wherever possible, a similar request to the IMF1
. This is a precondition for the Eurogroup to agree on a new ESM programme. Therefore Greece will request continued IMF support (monitoring and financing) from March 2016. Given the need to rebuild trust with Greece, the Euro Summit welcomes the commitments of the Greek authorities to legislate without delay a first set of measures. These measures, taken in full prior agreement with the Institutions, will include:
by 15 July
• the streamlining of the VAT system and the broadening of the tax base to increase revenue;
• upfront measures to improve long-term sustainability of the pension system as part of a
comprehensive pension reform programme;
• the safeguarding of the full legal independence of ELSTAT;
• full implementation of the relevant provisions of the Treaty on Stability, Coordination and Governance in the Economic and Monetary Union, in particular by making the Fiscal Council operational before finalizing the MoU and introducing quasi-automatic spending cuts in case of deviations from ambitious primary surplus targets after seeking advice from the Fiscal Council and subject to prior approval of the Institutions; by 22 July
• the adoption of the Code of Civil Procedure, which is a major overhaul of procedures and arrangements for the civil justice system and can significantly accelerate the judicial process and reduce costs;
• the transposition of the BRRD with support from the European Commission. Immediately, and only subsequent to legal implementation of the first four above-mentioned
measures as well as endorsement of all the commitments included in this document by the Greek Parliament, verified by the Institutions and the Eurogroup, may a decision to mandate the Institutions to negotiate a Memorandum of Understanding (MoU) be taken. This decision would be taken subject to national procedures having been completed and if the preconditions of Article 13 of the ESM Treaty are met on the basis of the assessment referred to in Article 13.1.
In order to form the basis for a successful conclusion of the MoU, the Greek offer of reform measures needs to be seriously strengthened to take into account the strongly deteriorated economic and fiscal position of the country during the last year. The Greek government needs to formally commit to strengthening their proposals in a number of areas identified by the Institutions, with a satisfactory clear timetable for legislation and implementation, including structural benchmarks, milestones and quantitative benchmarks, to have clarity on the direction of policies over the medium-run. They notably need, in agreement with the Institutions, to:
• carry out ambitious pension reforms and specify policies to fully compensate for the fiscal impact of the Constitutional Court ruling on the 2012 pension reform and to implement the zero deficit clause or mutually agreeable alternative measures by October 2015;
• adopt more ambitious product market reforms with a clear timetable for implementation of all OECD toolkit I recommendations, including Sunday trade, sales periods, pharmacy ownership, milk and bakeries, except over-the-counter pharmaceutical products, which will be implemented in a next step, as well as for the opening of macro-critical closed professions (e.g. ferry transportation). On the follow-up of the OECD toolkit-II, manufacturing needs to be included in the prior action;
• on energy markets, proceed with the privatisation of the electricity transmission network operator (ADMIE), unless replacement measures can be found that have equivalent effect on competition, as agreed by the Institutions;
• on labour markets, undertake rigorous reviews and modernisation of collective bargaining, industrial action and, in line with the relevant EU directive and best practice, collective dismissals, along the timetable and the approach agreed with the Institutions. On the basis of these reviews, labour market policies should be aligned with international and European best practices, and should not involve a return to past policy settings which are not compatible with the goals of promoting sustainable and inclusive growth;
* adopt the necessary steps to strengthen the financial sector, including decisive action on non-performing loans and measures to strengthen governance of the HFSF and the banks, in particular by eliminating any possibility for political interference especially in appointment processes.
On top of that, the Greek authorities shall take the following actions:
• to develop a significantly scaled up privatisation programme with improved governance; valuable Greek assets will be transferred to an independent fund that will monetize the assets through privatisations and other means. The monetization of the assets will be one source to make the scheduled repayment of the new loan of ESM and generate over the life of the new loan a targeted total of EUR 50bn of which EUR 25bn will be used for the repayment of recapitalization of banks and other assets and 50 % of every remaining euro (i.e. 50% of EUR 25bn) will be used for decreasing the debt to GDP ratio and the remaining 50 % will be used for investments. This fund would be established in Greece and be managed by the Greek authorities under the supervision of the relevant European Institutions. In agreement with Institutions and building on best international practices, a legislative framework should be adopted to ensure transparent procedures and adequate asset sale pricing, according to OECD principles and standards on the management of State Owned Enterprises (SOEs);
• in line with the Greek government ambitions, to modernise and significantly strengthen the Greek administration, and to put in place a programme, under the auspices of the European Commission, for capacity-building and de-politicizing the Greek administration. A first proposal should be provided by 20 July after discussions with the Institutions. The Greek government commits to reduce further the costs of the Greek administration, in line with a schedule agreed with the Institutions;
• to fully normalize working methods with the Institutions, including the necessary work on the ground in Athens, to improve programme implementation and monitoring. The
government needs to consult and agree with the Institutions on all draft legislation in relevant areas with adequate time before submitting it for public consultation or to Parliament. The Euro Summit stresses again that implementation is key, and in that context welcomes the intention of the Greek authorities to request by 20 July support from the Institutions and Member States for technical assistance, and asks the European Commission to coordinate this support from Europe;
• With the exception of the humanitarian crisis bill, the Greek government will reexamine with a view to amending legislations that were introduced counter to the February 20 agreement by backtracking on previous programme commitments or identify clear compensatory equivalents for the vested rights that were subsequently created.
The above-listed commitments are minimum requirements to start the negotiations with the Greek authorities. However, the Euro Summit made it clear that the start of negotiations does not preclude any final possible agreement on a new ESM programme, which will have to be based on a decision on the whole package (including financing needs, debt sustainability and possible bridge financing).
The Euro Summit takes note of the possible programme financing needs of between EUR 82 and 86bn, as assessed by the Institutions. It invites the Institutions to explore possibilities to reduce the financing envelope, through an alternative fiscal path or higher privatisation proceeds. Restoring market access, which is an objective of any financial assistance programme, lowers the need to draw on the total financing envelope. The Euro Summit takes note of the urgent financing needs of Greece which underline the need for very swift progress in reaching a decision on a new MoU: these are estimated to amount to EUR 7bn by 20 July and an additional EUR 5bn by mid August.
The Euro Summit acknowledges the importance of ensuring that the Greek sovereign can clear its arrears to the IMF and to the Bank of Greece and honour its debt obligations in the coming weeks to create conditions which allow for an orderly conclusion of the negotiations. The risks of not concluding swiftly the negotiations remain fully with Greece. The Euro Summit invites the Eurogroup to discuss these issues as a matter of urgency.
Given the acute challenges of the Greek financial sector, the total envelope of a possible new ESM programme would have to include the establishment of a buffer of EUR 10 to 25bn for the banking sector in order to address potential bank recapitalisation needs and resolution costs, of which EUR 10bn would be made available immediately in a segregated account at the ESM.
The Euro Summit is aware that a rapid decision on a new programme is a condition to allow banks to reopen, thus avoiding an increase in the total financing envelope. The ECB/SSM will conduct a comprehensive assessment after the summer. The overall buffer will cater for possible capital shortfalls following the comprehensive assessment after the legal framework is applied.
There are serious concerns regarding the sustainability of Greek debt. This is due to the easing of policies during the last twelve months, which resulted in the recent deterioration in the domestic macroeconomic and financial environment. The Euro Summit recalls that the euro area Member States have, throughout the last few years, adopted a remarkable set of measures supporting Greece’s debt sustainability, which have smoothed Greece’s debt servicing path and reduced costs significantly.
Against this background, in the context of a possible future ESM programme, and in line with the spirit of the Eurogroup statement of November 2012, the Eurogroup stands ready to consider, if necessary, possible additional measures (possible longer grace and payment periods) aiming at ensuring that gross financing needs remain at a sustainable level. These measures will be conditional upon full implementation of the measures to be agreed in a possible new programme and will be considered after the first positive completion of a review.
The Euro Summit stresses that nominal haircuts on the debt cannot be undertaken. The Greek authorities reiterate their unequivocal commitment to honour their financial obligations to all their creditors fully and in a timely manner
Provided that all the necessary conditions contained in this document are fulfilled, the Eurogroup and ESM Board of Governors may, in accordance with Article 13.2 of the ESM Treaty, mandate the Institutions to negotiate a new ESM programme, if the preconditions of Article 13 of the ESM Treaty are met on the basis of the assessment referred to in Article 13.1.
To help support growth and job creation in Greece (in the next 3-5 years) the Commission will work closely with the Greek authorities to mobilise up to EUR 35bn (under various EU programmes) to fund investment and economic activity, including in SMEs. As an exceptional measure and given the unique situation of Greece the Commission will propose to increase the level of pre-financing by EUR 1bn to give an immediate boost to investment to be dealt with by the EU co-legislators. The Investment Plan for Europe will also provide funding opportunities for Greece.
Greek Prime Minister Alexis Tsipras Discuss the Solutions for Greece Debt Crisis, TTIP, Emissions Trading Scheme
The Greece debt crisis took centre stage during July’s plenary session, as Greek Prime Minister Alexis Tsipras came to Strasbourg to discuss the search for solutions. MEPs also adopted their recommendations for Transatlantic Trade and Investment Partnership (TTIP) and approved a reform of the EU’s emissions trading scheme that should boost incentives for green investments. Read on for our summary of what happened in Strasbourg in a busy summer week.
MEPs held a heated debate with Tsipras, European Council President Donald Tusk and Commission President Jean-Claude Juncker on the search for an agreement between Greece and international creditors. Check out our detailed debate coverage on Storify.
MEPs approved Parliament’s position on the negotiations for EU-US trade agreement TTIP, insisting on a new system of settling disputes between investors and states that should be run by publicly appointed judges instead of private arbitration.
As Luxembourg took over the rotating presidency of the EU Council from Latvia at the start of the month, MEPs discussed with the prime ministers of both countries the challenges facing Europe, most noticeably the situation in Greece.
MEPs voted to reform the EU’s emissions trading scheme aiming at a gradual reduction of surplus emission allowances to support their prices. Following a deal with the Council, the new market stability reserve will start operating in 2019, two years earlier than initially foreseen.
Parliament called for ways to improve access to online content across borders in a resolution on copyright. The interests of both creators and consumers should be protected, MEPs insisted.
Large firms and listed companies have to provide country-by-country information on profits made, tax paid and public subsidies received, Parliament said. EP negotiators will now seek an agreement with EU governments.
Travellers crossing borders and using more than one mode of transport should be able to book their journey with a single ticket, MEPs said.
MEPs also voted on resolutions concerning the challenges in the dairy sector and in fruit and vegetable production, calling for more EU action to help farmers deal with market disturbances and external shocks, such as the Russian import ban.
MEPs condemned the genocide in the Bosnian town of Srebrenica 20 years ago, when more than 8,000 Muslim men and boys were killed by Bosnian Serb forces and paramilitary units.
The EU needs to use resources more efficiently, MEPs said in a resolution on moving towards a circular economy based on reuse, repair and recycling. The approved text calls for binding waste-reduction targets and updated rules for ecodesign.