

Startup Accelerator – URBAN-X By MINI And Urban US – Launches Sixth Cohort
BROOKLYN, NY – June 6, 2019 – URBAN-X, a leading accelerator for startups reimagining city life, today announced its sixth cohort of companies. URBAN-X is part of the Innovation and Brand Strategy practice at MINI and partners with venture firm, Urban Us. The seven startups were selected from a competitive group of hundreds of applicants from across the globe and are building solutions to some of our cities most pressing issues.
Each company selected will participate in a 20-week intensive accelerator program to help develop hardware, software or IoT products and successful go-to-market strategies. Companies have access to hands-on assistance from URBAN-X’s expansive network of global experts – including world-class engineers and designers from BMW, software developers, policy experts, marketing and sales leaders, UX/UI designers and communications experts. Cohort 06 is also the first class to receive a $150,000 investment per company, up from $100,000 in previous cohorts.
The program will culminate in a Demo Day during Climate Week NYC in September 2019, where teams will present their solutions to an audience of investors, policymakers, customers and more. Following demo day, the companies are introduced to investors at investor days beginning in New York and the Bay Area.
Cohort 06 includes the following startups:
3AM Innovation: Situational tracking during emergencies to improve on-scene awareness for first responders
Cove.Tool: Automated building performance modeling to save time and money for early stage design
Evolve Energy: Reducing carbon emissions while saving costs via renewable energy, real time pricing and home IOT
Food For All: Tackling food waste by partnering with popular restaurants and offering quality meals for as little as $4
Hubbster: Building stronger communities by transforming public spaces into social experiences
Pi Variables: Enhancing road safety and traffic guidance via innovative hardware, software and design-focused solutions
Varuna: A cloud-based platform that provides analytics and insights to improve water quality by optimizing utility operations
MINI launched URBAN-X in 2016 as part of their Innovation and Brand Strategy practice focused on improving city life. URBAN-X engages with the brightest minds solving some of the most complex issues people living in cities face today, like mobility, energy consumption, infrastructure, housing, food waste, water and more. The accelerator now has 44 companies in the portfolio, with 85% of companies having gone on to raise their next round of capital.
“Cohort 06 is working on solutions to some of the most critical issues impacting our cities today,” said Esther Bahne, MINI Head of Brand Strategy & Innovation. “Through URBAN-X, MINI is making an investment that inspires entrepreneurship, design and collaboration with creative thinkers to develop sustainable solutions to real problems.”
“Cities and emerging technology companies are powerful partners in helping to tackle our cities biggest challenges,” said URBAN-X Managing Director, Micah Kotch. “We look forward to working with Cohort 06 and bringing their solutions to scale across a diverse set of industries that impact city living.”
In 2017, Urban Us partnered with URBAN-X to help fund and develop the accelerator’s next generation of human-focused city innovation.
“Urban Us and MINI share a deep commitment to advancing the future of our cities through technology, investment and mentorship,” said Shaun Abrahamson, URBAN-X Investment Committee and Managing Partner at Urban Us. “Since partnering with MINI, we’ve seen incredible results from URBAN-X startups. We are ready to get started to help Cohort 06 startup founders achieve long-lasting results.”
Applications for URBAN-X’s next cohort of startups, Cohort 07 are open. Interested early-stage companies can apply at www.urban-x.com/apply through October 1, 2019.
About URBAN-X
URBAN-X is a leading accelerator for startups reimagining city life. Founded by MINI and run in partnership with Urban Us, URBAN-X helps early-stage companies work with and in cities. URBAN-X has a global reach unparalleled by any other urbantech accelerator. Startups have access to a network of over 2,000 partners around the world, including entrepreneurs, investors, and public-sector leaders, who support founders through the URBAN-X program.
During the year, URBAN-X leadership visits cities worldwide—in the US, Europe, Asia and beyond—to meet entrepreneurs and individuals shaping the future of urban life. URBAN-X is based in Greenpoint, Brooklyn at A/D/O, a creative space founded by MINI and dedicated to exploring the boundaries of design. Applications for Cohort 06 are currently open at www.URBAN-X.com. Find URBAN-X on Twitter & Instagram at @urbanxaccel and on Facebook at facebook.com/urbanxaccel.
About MINI Innovation
MINI is an independent brand of the BMW Group. As an iconic and emotional urban brand, MINI has taken a unique approach to innovation, carrying forward its roots as an innovator of efficient urban mobility while maximizing creative use of space. Although MINI benefits from BMW Group technological advancements, including those in autonomous, connected, electrified and shared segments, MINI has evolved its thinking and product development across a unique range of areas that interest with mobility and extend beyond the car. MINI Innovation is focused on the future of electrified mobility, impactful design, urban living and the important interplay between these areas. The practice includes: A/D/O, URBAN-X, MINI Living and MINI Fashion.
Urban Us
Urban Us is the leading early stage investor for startups re-imagining cities. Cities will soon be home to 70% of the global population, who now face unprecedented risk from climate change. Our 2014 and 2016 funds achieve top quartile performance for investors while also generating substantial public benefits. Urban Us recently launched our third fund to continue our focus on founders reimagining cities as well as a new non-equity fund focused on areas like project and asset finance.
The Urban Us platform includes the Urban Us network, a resource for urbantech focused founders, investors, partners and customers. URBAN-X, in partnership with MINI, supports early stage teams with company building and fundraising. Perl Street serves teams needing access to non-equity capital for project finance, asset finance and inventory finance. Our newest partnerships will help startups access partners and customers in Asia.
Before Urban Us, the Urban Us team had three exits and ran a VC fund and municipal finance for Citi. Notable investments before Urban Us include Trialpay, Blue Bottle Coffee, Refinery29 and ZocDoc. The Urban Us portfolio includes 53 investments across real estate, infrastructure, energy, water, waste, food, transportation and public administration including health and security. Notable investments include, Bowery Farming, Starcity, Mark43, One Concern, Future Motion, Skycatch, BRCK and Rachio.
Marsh & McLennan Completes Acquisition of Jardine Lloyd Thompson
NEW YORK — Marsh & McLennan Companies, Inc. (NYSE:MMC) today completed the acquisition of Jardine Lloyd Thompson Group plc (JLT) for $5.6 billion in fully diluted equity value, furthering its role as the world’s preeminent professional services firm in the areas of risk, strategy and people.
“Today marks the beginning of a new era with Marsh & McLennan and JLT coming together. This is a combination of strength and strength, and the primary focus is growth – in talent, capabilities, revenue and earnings,” said Dan Glaser, President and Chief Executive Officer, Marsh & McLennan Companies.
Market Leader in Risk, Strategy & People
The acquisition advances Marsh & McLennan’s leadership position in insurance and reinsurance brokerage, health and retirement. Its global reach spans more than 130 countries. Marsh & McLennan Companies advises 95 percent of the Fortune 1000®1 and has significantly expanded its presence in the middle market and small commercial segments. The combined company provides advice and solutions for more than $100 billion of annual property/casualty insurance and reinsurance premiums placed globally.
Formidable Collection of Talent
JLT brings Marsh & McLennan a significant influx of talent – more than 10,000 colleagues – providing deeper industry expertise in almost every part of the organization. The combination will create more opportunities for colleagues. Many of JLT’s top executives have been named to leadership positions at Marsh & McLennan, Marsh, Guy Carpenter and Mercer including former JLT CEO Dominic Burke, who joins Marsh & McLennan as Vice Chairman and a member of the Executive Committee. Mr. Glaser said, “Our aspiration is to shape our industries and be the employer of choice.”
Enhancing Capabilities, Growth & Investment in Data & Analytics
The acquisition builds on Marsh & McLennan’s efforts to expand in faster-growing geographies and market segments and invest in data and analytics while enhancing its capabilities across insurance brokerage, retirement and benefits.
Financially Attractive for Shareholders
As previously announced, the transaction is expected to be immediately accretive to adjusted cash EPS and, as modeled, will produce a double-digit internal rate of return. On an adjusted GAAP EPS basis, the deal is expected to be modestly dilutive in year one, neutral in year two, and accretive in year three.
About Marsh & McLennan Companies
Marsh & McLennan (NYSE: MMC) is the world’s leading professional services firm in the areas of risk, strategy and people. The company’s 75,000 colleagues advise clients in over 130 countries. With 2018 revenue of $15 billion, Marsh & McLennan helps clients navigate an increasingly dynamic and complex environment through four market-leading firms. Marsh advises individual and commercial clients of all sizes on insurance broking and innovative risk management solutions. Guy Carpenter develops advanced risk, reinsurance and capital strategies that help clients grow profitably and pursue emerging opportunities. Mercer delivers advice and technology-driven solutions that help organizations meet the health, wealth and career needs of a changing workforce. Oliver Wyman serves as a critical strategic, economic and brand advisor to private sector and governmental clients. For more information, visit mmc.com, follow us on LinkedIn and Twitter @mmc_global or subscribe to BRINK.
ManpowerGroup Named a Top Workplace by Employees for Job Satisfaction for the Second Consecutive Year
MILWAUKEE — ManpowerGroup (NYSE:MAN) has been named a 2019 Top Workplace in Southeast Wisconsin by The Milwaukee Journal Sentinel. The award is based solely on employee feedback and recognizes ManpowerGroup for the second year for the strength of its workplace culture including its commitment to diversity and inclusion, attracting and developing talent and employee engagement.
“Putting hundreds of thousands of people to work every year across Wisconsin and the U.S. is only possible because we are committed to cultivating a work environment where people can be their true selves and feel empowered to reach their potential,” said Becky Frankiewicz, President, ManpowerGroup North America. “It’s important to us that we take responsibility to broaden the capabilities of our people, nurture a culture of learnability and develop the skills needed for jobs today and tomorrow. That’s why this award is even more of an honor because our own people are telling us ManpowerGroup is a place they want to work, feel supported and can thrive.”
The Milwaukee Journal Sentinel Top Workplace Awards facilitated by research firm Energage survey Southeast Wisconsin’s leading small, medium and large employers to measure work environments.
To learn more about ManpowerGroup’s commitment to connecting people to meaningful and sustainable employment, visit https://doingwellbydoinggood.manpowergroup.com/.
ABOUT MANPOWERGROUP
ManpowerGroup® (NYSE: MAN), the leading global workforce solutions company, helps organizations transform in a fast-changing world of work by sourcing, assessing, developing and managing the talent that enables them to win. We develop innovative solutions for hundreds of thousands of organizations every year, providing them with skilled talent while finding meaningful, sustainable employment for millions of people across a wide range of industries and skills. Our expert family of brands – Manpower®, Experis®, Right Management® and ManpowerGroup® Solutions – creates substantially more value for candidates and clients across 80 countries and territories and has done so for over 70 years. In 2019, ManpowerGroup was named one of Fortune’s Most Admired Companies for the seventeenth year and one of the World’s Most Ethical Companies for the tenth year, confirming our position as the most trusted brand in the industry. See how ManpowerGroup is powering the future of work: www.manpowergroup.com.
ABOUT ENERGAGE, LLC
Headquartered in Exton, Pa., Energage (formerly known as WorkplaceDynamics) is a leading provider of technology-based employee engagement tools that help leaders to unlock potential, inspire performance, and achieve amazing results within their organizations. The research partner behind the Top Workplaces program, Energage has surveyed more than 47,000 organizations representing well over 16 million employees in the United States.
Ethiopian Airlines Wins the Prestigious ‘African Champion of the Year’ Award
Ethiopian Airlines, the largest Aviation Group in Africa and SKYTRAX certified Four Star Global Airline, wins the prestigious African Champion of the Year Award on March 26,2019 at the ongoing Africa CEO Forum in Kigali which is being attended by more than 1,800 delegates.
The AFRICA CEO FORUM is the leading international conference dedicated to the private sector in Africa and hosts the continent’s top CEOs, international investors, experts and high-level policy makers every year.
Every year, the AFRICA CEO FORUM AWARDS recognize the companies and investors that have shaped the year in Africa, during the AFRICA CEO FORUM Gala Dinner.
While receiving the awards, Group Chief Executive Officer of Ethiopian Airlines, Mr. Tewolde GebreMariam said, “We are honored to be awarded as African champion. Thank you very much for the strong vote of confidence that Africa has given us even at the most challenging time in our history. We are still mourning for the loss of the lives of our esteemed passengers and colleagues at the tragic accident on ET 302 on 10 March 2019. My sincere sympathy and heartfelt condolences for the families of the victims, the country and the continent of Africa.
But we are very grateful to the traveling public which have stood with us in such difficult time. The vote of confidence is unbelievable. We have never seen such kind of large number of vote of confidence for one of the strongest brands in Africa. Thank you all for all the support you have given us and continue to give us. Together, we will make Africa great and we will put our continent in its right place in the global stage.”
Ethiopian is a multi-award winning airline. On November 8, 2017, SKYTRAX, the most prestigious international air transport standards and quality rating organization, has certified Ethiopian as Four Star Airline. SKYTRAX has also awarded Ethiopian as SKYTRAX World Airline Award for Best Airline Staff in Africa, two times, and earlier in 2017 Ethiopian has received SKYTRAX World Airline Award for Best Airline in Africa.
About Ethiopian
Ethiopian Airlines (Ethiopian) is the fastest growing Airline in Africa. In its seventy plus years of operation, Ethiopian has become one of the continent’s leading carriers, unrivalled in efficiency and operational success.
Ethiopian commands the lion’s share of the Pan-African passenger and cargo network operating the youngest and most modern fleet to more than 119 international passenger and cargo destinations across five continents. Ethiopian fleet includes ultra-modern and environmentally friendly aircraft such as Airbus A350, Boeing 787-8, Boeing 787-9, Boeing 777-300ER, Boeing 777-200LR, Boeing 777-200 Freighter, Bombardier Q-400 double cabin with an average fleet age of five years. In fact, Ethiopian is the first airline in Africa to own and operate these aircraft. Ethiopian is currently implementing a 15-year strategic plan called Vision 2025 that will see it become the leading aviation group in Africa with Six business centers: Ethiopian International Services; Ethiopian Cargo & Logistics Services; Ethiopian MRO Services; Ethiopian Aviation Academy; Ethiopian ADD Hub Ground Services and Ethiopian Airports Services. Ethiopian is a multi-award winning airline registering an average growth of 25% in the past seven years.
Competition for Skilled Talent Set to Grow as U.S. Employers Continue to Report Upbeat Hiring in the Second Quarter
MILWAUKEE — Demand for skilled talent continues to grow as employers across the U.S. are reporting positive hiring intentions nationwide (+19%) across all 50 states, according to the Q2 2019 ManpowerGroup (NYSE: MAN) Employment Outlook Survey. This is the seventh consecutive year of double-digit hiring Outlooks in the U.S., according to the survey of more than 11,500 U.S. employers. The Q2 2019 employment Outlook comes after the Bureau of Labor Statistics’ January jobs report marked 100 months of consecutive job growth in America with approximately 19M gains since October 2010.
Employers in all 13 industry sectors report optimistic hiring plans with the strongest Outlooks reported in Leisure & Hospitality, Transportation & Utilities (both +25%) and Wholesale & Retail Trade (+24%) as consumers dine out and demand immediate delivery from groceries to fast fashion. Employers in Professional & Business Services have a +23% employment Outlook fueled by growing demand for knowledge workers with the right balance of human strengths including communication and collaboration and technical capabilities from coding to data analytics.
“As U.S. employers continue to report double-digit hiring Outlooks, demand for talent is growing across the board from cyber security experts and data analysts to delivery drivers needed to keep up with 24/7 online retail,” said Becky Frankiewicz, President of ManpowerGroup North America. “It’s a skilled worker’s market. The best employers are reviewing the difference between what is desired in a role and what is required for a job. In the tech sector, we see a higher number of Java openings requiring computer science degrees than there are graduates. The most successful employers are re-evaluating the precise experience and education truly required to get the job done and as a result they’re attracting the best, and often more diverse, talent to the organization.”
View complete Q2 2019 survey results for the U.S: ManpowerGroup.US/MEOS.
Region
Q2 2019
Quarter-over-Quarter Variation
Year-over-Year Variation
West
20%
0%
+1%
Midwest
19%
+1%
-1%
South
20%
-1%
+2%
Northeast
18%
-2%
+1%
U.S. Hiring Plans by Industry Sectors, Regions and Metro Areas/States
Nationwide, employers in all 13 industry sectors expect to add staff in Q2 2019. The strongest Outlooks are reported in Transportation & Utilities (+25%), Leisure & Hospitality (+25%), Wholesale & Retail Trade (+24%) and Professional & Business Services (+23%) followed by Mining (+19%), Construction (+19%), Durable Goods Manufacturing (+19%) and Non-Durable Goods Manufacturing (+17%).
Both the South and the West have the highest regional Outlooks (+20%) in the country. Hiring prospects in the Midwest (+19%) are a close second with employers in the Northeast (+18%) not far behind. In the Midwest (+20%), Northeast (+18%) and West, the Outlook is up a percentage point (+20%) year-over-year and up two percentage points in the South.
Employers in Indiana (+33%), Maine (+33%), Alaska (+28%), Colorado (+27%), Kansas (+26%), North Carolina (+26%) and Oregon (+26%) report the strongest Outlooks nationwide. Of the 100 largest metropolitan statistical areas, the strongest job gains are expected in Greensboro, N.C. (+35%), Denver, Col. (+34%), Indianapolis, Ind. (+33%), Sacramento, Cal. (+32%), Albany, N.Y. (+31%), Deltona, Fla. (+31%) and Madison, Wis. (31%).
Complete results for the ManpowerGroup Employment Outlook Survey are available for download at ManpowerGroup.US/MEOS. The Q3 2019 survey will be released June 11, 2019.
*The Net Employment Outlook is derived by taking the percentage of employers anticipating an increase in hiring activity and subtracting from this the percentage of employers expecting a decrease in hiring activity.
About ManpowerGroup
ManpowerGroup® (NYSE: MAN), the leading global workforce solutions company, helps organizations transform in a fast-changing world of work by sourcing, assessing, developing and managing the talent that enables them to win. We develop innovative solutions for hundreds of thousands of organizations every year, providing them with skilled talent while finding meaningful, sustainable employment for millions of people across a wide range of industries and skills. Our expert family of brands – Manpower®, Experis®, Right Management® and ManpowerGroup® Solutions – creates substantially more value for candidates and clients across 80 countries and territories and has done so for 70 years. In 2019, ManpowerGroup was named one of Fortune’s Most Admired Companies for the seventeenth year and one of the World’s Most Ethical Companies for the tenth year, confirming our position as the most trusted brand in the industry. See how ManpowerGroup is powering the future of work: www.manpowergroup.com.
ManpowerGroup Solutions Total Workforce Index* Ranks Ireland, Norway and UK as Top Spots for Talent
MILWAUKEE — The ManpowerGroup (NYSE: MAN) Solutions Total Workforce Index™ 2019 reveals Ireland, Norway and the UK as top labor markets across the globe for sourcing, hiring and retaining workforce skills. In an increasingly complex global market, access to skilled talent is a priority for organizations looking to build or grow their business. The Total Workforce Index™ is the only tool of its kind to use Big Data combined with expert insight to compare workforce potential across markets by evaluating the skills availability, cost efficiency and workforce productivity of both permanent and contingent labor sources.
The Index uses a proprietary formula that can be customized to respond specifically to an organization’s most pressing workforce priorities. These can range from sector specific skills challenges and the impact of shifting regulations to flexible scheduling and changing wages by location across sectors from oil and gas to IT and manufacturing.
“The emergence of new skills and new talent pools, together with fresh ways to work and get work done, mean companies have more options than ever when identifying where to locate or expand their operations,” said Becky Frankiewicz, President of ManpowerGroup North America. “Whether the priority is a specific tech skilled workforce or setting up a new call center, we can use the index to provide companies with data that helps them to make better and faster strategic decisions. With this right combination of data and insights, organizations can execute a precise talent strategy to meet their unique business needs.”
View the full Total Workforce Index™ 2018 report at https://www.manpowergroupsolutions.com/twi for the full rankings on markets most favorable to conduct business.
REGIONAL RANKINGS
APAC – Hong Kong, New Zealand, Singapore are the top markets for business development in the APAC region and globally. Hong Kong and Singapore rank highly for larger talent pools and support of flexible working conditions versus markets with new tax policies and labor laws.
AMERICAS – The United States and Canada claim the top two rankings in the Americas region due to their mature workforces, followed by Chile, Mexico and Puerto Rico. Across South and Central America, micro market shifts and significant legislative changes can increase hiring complexity. The lowest ranked countries across the TWI globally are also in the Americas: Brazil, Honduras, Bolivia and Venezuela. Only the U.S. and Canada rank in the global top 10 – at 4th and 6th respectively.
EMEA – The top five ranked countries in the region are the UK, Ireland, Estonia, United Arab Emirates and Israel. All of these countries bar Israel rank in the top 10 globally. Increasing access to education and investment in skills development have contributed to the workforce potential across the region.
About the Total Workforce Index™
The Total Workforce Index™ (TWI) uses a proprietary formula to measure the relative ease of sourcing, hiring and retaining a workforce in competing labor markets around the world. The TWI compiles more than 90 key factors which relate to the Availability, Cost Efficiency, Regulation and Productivity of the workforce of each country. Unlike any other Workforce Index, the Total Workforce Index™ considers the entire workforce and not a single segment of the workforce in each country. The inclusion of the complete workforce allows for segmentation to review and analyze the contingent and permanent workforce considerations, in addition to the sum of these two workforce segments.
About ManpowerGroup SolutionsManpowerGroup Solutions provides clients with outsourcing services related to human resources functions, primarily in the areas of large-scale recruiting and workforce-intensive initiatives that are outcome-based, thereby sharing in the risk and reward with our clients. Our solutions offerings include TAPFIN-Managed Service Provider, Strategic Workforce Consulting, Borderless Talent Solutions, Talent Based Outsourcing and Recruitment Process Outsourcing, where we are one of the largest providers of permanent and contingent recruitment in the world. ManpowerGroup Solutions is part of the ManpowerGroup family of companies, which also includes Manpower, Experis, and Right Management. More information at www.manpowergroupsolutions.com.
About ManpowerGroup
ManpowerGroup® (NYSE: MAN), the leading global workforce solutions company, helps organizations transform in a fast-changing world of work by sourcing, assessing, developing and managing the talent that enables them to win. We develop innovative solutions for hundreds of thousands of organizations every year, providing them with skilled talent while finding meaningful, sustainable employment for millions of people across a wide range of industries and skills. Our expert family of brands – Manpower®, Experis®, Right Management® and ManpowerGroup® Solutions – creates substantially more value for candidates and clients across 80 countries and territories and has done so for 70 years. In 2019, ManpowerGroup was named one of Fortune’s Most Admired Companies for the seventeenth year and one of the World’s Most Ethical Companies for the ninth year in 2018, confirming our position as the most trusted and admired brand in the industry. See how ManpowerGroup is powering the future of work: www.manpowergroup.com
Record Number of U.S. Employers Plan to Upskill their Workforce as Automation Creates New Jobs
MILWAUKEE — Robot workers replacing human jobs – the debate of the decade. In reality, robots require human skills. ManpowerGroup’s (NYSE:MAN) report Humans Wanted: Robots Need You found that 91% of U.S. employers plan to increase or maintain headcount as a result of automation for the third consecutive year. Just 4% predicted job losses due to automation, according to the more than 1,500 U.S. employers ManpowerGroup surveyed on the impact of automation on job growth in the next two years. For the full findings click here: https://www.manpowergroup.us/campaigns/manpower/skills-revolution-4/
Companies that are digitizing are growing, and that growth is producing more and new kinds of jobs. Organizations that are already automating tasks and progressing their digital transformation are most confident of increasing headcount – 34% of U.S. employers that have started their digital transformation are expecting to create more jobs in the next two years.
The U.S. is facing low unemployment, acute talent shortages and increasing talent demand as new skills appear as fast as others disappear, prompting companies to build talent like never before. Seventy-six percent of employers plan to upskill their workforce by 2020, compared with 28% in 2011 and a 21% increase from last year.
“Today marks 100 months of consecutive jobs gains in the U.S. and despite the humans versus robots debate, employers are telling us they intend to add to their workforce as they digitize and require uniquely human skills to complement the machines,” said Becky Frankiewicz, President of ManpowerGroup North America. “Organizations automating at a faster pace plan to create the most jobs, yet skilled talent is in short supply across the country. We need to move past our fear of tech eliminating jobs and take action to reskill the workforce to ensure no one is left behind. From digital manufacturing to IT, we’re working with companies to develop targeted training programs to upskill people at speed and at scale. This is how organizations will stay competitive and people will remain relevant in the digital age.”
The Humans Wanted report found that demand for IT skills is growing significantly and with speed; 16% of companies expect to increase headcount in IT, double those expecting a decrease. Production and manufacturing employers anticipate the most churn as new skills are created while others become outdated leading to a net headcount increase of 7% [19% say they will employ more people in the next year, while 12% say they will employ less]. Job growth will come in frontline and customer-facing engineering and management roles – all of which require human skills such as communication, negotiation leadership, management and adaptability.
Humans Wanted: Robots Need You provides practical recommendations and best practice examples from around the world to help organizations upskill their people and become more agile with the right combination of building, buying, borrowing and bridging talent.
About ManpowerGroup
ManpowerGroup® (NYSE: MAN), the leading global workforce solutions company, helps organizations transform in a fast-changing world of work by sourcing, assessing, developing and managing the talent that enables them to win. We develop innovative solutions for hundreds of thousands of organizations every year, providing them with skilled talent while finding meaningful, sustainable employment for millions of people across a wide range of industries and skills. Our expert family of brands – Manpower®, Experis®, Right Management® and ManpowerGroup® Solutions – creates substantially more value for candidates and clients across 80 countries and territories and has done so for 70 years. In 2018, ManpowerGroup was named one of the World’s Most Ethical Companies for the ninth year and one of Fortune’s Most Admired Companies for the seventeenth year, confirming our position as the most trusted and admired brand in the industry. See how ManpowerGroup is powering the future of work: www.manpowergroup.com
US Department of Labor: 304,000 New Jobs Were Created In January
WASHINGTON, DC – U.S. Secretary of Labor Alexander Acosta today issued the following statement regarding the January 2019 Employment Situation report:
“January’s Job Report demonstrated the strength of the American economy, with 304,000 jobs added as private sector job creation continued to surge despite the partial government shutdown. Significant growth in the mining, construction, and transportation and warehousing sectors led the report.
“The unemployment rate ticked up 0.1 percentage point to 4.0%, largely as a result of the temporary lapse in federal government funding, yet this is the 11th consecutive month that the unemployment rate has been at or below 4.0%.
“Average hourly earnings rose by 3.2%, marking the sixth straight month in which year over year hourly earnings have been growing at or above 3%. Average weekly earnings rose at an even more robust 3.5%, year over year.
“Another key indicator in the report pointed to the increase of the labor force participation rate to 63.2%, the highest rate since August 2013.
“As the jobs and employment data normalizes over the coming months, we are confident the nation’s economy will continue to build on the strength seen in 2018 and the first report of 2019.”
IMF World Economic Outlook Update, January 2019: A Weakening Global Expansion
The global expansion has weakened. Global growth for 2018 is estimated at 3.7 percent, as in the October 2018 World Economic Outlook (WEO) forecast, despite weaker performance in some economies, notably Europe and Asia. The global economy is projected to grow at 3.5 percent in 2019 and 3.6 percent in 2020, 0.2 and 0.1 percentage point below last October’s projections.
The global growth forecast for 2019 and 2020 had already been revised downward in the last WEO, partly because of the negative effects of tariff increases enacted in the United States and China earlier that year. The further downward revision since October in part reflects carry over from softer momentum in the second half of 2018—including in Germany following the introduction of new automobile fuel emission standards and in Italy where concerns about sovereign and financial risks have weighed on domestic demand—but also weakening financial market sentiment as well as a contraction in Turkey now projected to be deeper than anticipated.
Risks to global growth tilt to the downside. An escalation of trade tensions beyond those already incorporated in the forecast remains a key source of risk to the outlook. Financial conditions have already tightened since the fall. A range of triggers beyond escalating trade tensions could spark a further deterioration in risk sentiment with adverse growth implications, especially given the high levels of public and private debt. These potential triggers include a “no-deal” withdrawal of the United Kingdom from the European Union and a greater-than-envisaged slowdown in China.
The main shared policy priority is for countries to resolve cooperatively and quickly their trade disagreements and the resulting policy uncertainty, rather than raising harmful barriers further and destabilizing an already slowing global economy. Across all economies, measures to boost potential output growth, enhance inclusiveness, and strengthen fiscal and financial buffers in an environment of high debt burdens and tighter financial conditions are imperatives.
Softening Momentum, High Uncertainty
The global economy continues to expand, but third-quarter growth has disappointed in some economies. Idiosyncratic factors (new fuel emission standards in Germany, natural disasters in Japan) weighed on activity in large economies. But these developments occurred against a backdrop of weakening financial market sentiment, trade policy uncertainty, and concerns about China’s outlook. While the December 1 announcement that tariff hikes have been put on hold for 90 days in the US-China trade dispute is welcome, the possibility of tensions resurfacing in the spring casts a shadow over global economic prospects.
High-frequency data signal subdued momentum in the fourth quarter. Outside the United States, industrial production has decelerated, particularly of capital goods. Global trade growth has slowed to well below 2017 averages. The true underlying impetus could be even weaker than the data indicate, as the headline numbers may have been lifted by import front-loading ahead of tariff hikes, as well as by an uptick in tech exports with the launch of new products. Consistent with this interpretation, purchasing managers’ indices, notably in the category of new orders, point to less buoyant expectations of future activity.
Commodities and inflation. Crude oil prices have been volatile since August, reflecting supply influences, including US policy on Iranian oil exports and, more recently, fears of softening global demand. As of early January, crude oil prices stood at around $55 a barrel, and markets expected prices to remain broadly at that level over the next 4–5 years. Prices of metals and agricultural commodities have softened slightly since August, in part due to subdued demand from China. Consumer price inflation has generally remained contained in recent months in advanced economies but has inched up in the United States, where above-trend growth continues. Among emerging market economies, inflationary pressures are easing with the drop in oil prices. For some, this easing has been partially offset by the passthrough of currency depreciations to domestic prices.
Financial conditions in advanced economies have tightened since the fall. Equity valuations—which were stretched in some countries—have been pared back with diminished optimism about earnings prospects amid escalating trade tensions and expectations of slower global growth. Concerns over a US government shutdown further weighed on financial sector sentiment toward year-end. Major central banks also appear to be adopting a more cautious approach. While the US Federal Reserve raised the target range for the federal funds rate to 2.25–2.50 percent in December, it signaled a more gradual pace of rate hikes in 2019 and 2020. In line with earlier communication, the European Central Bank ended its net asset purchases in December. However, it also confirmed that monetary policy would remain amply accommodative, with no increase in policy rates until at least summer 2019, and full reinvestment of maturing securities continuing well past the first rate hike. Increasing risk aversion, together with deteriorating sentiment about growth prospects and shifts in policy expectations, have contributed to a drop in sovereign yields—notably for US Treasuries, German bunds, and UK gilts. Among euro area economies, Italian sovereign spreads have declined from their peak in mid-October on a resolution of the budget standoff with the European Commission, but remain elevated at 270 basis points as of January 7. Spreads for other euro area economies have remained largely unchanged over this period. Beyond sovereign securities, credit spreads widened for US corporate bonds, reflecting lessened optimism and energy sector concerns owing to lower oil prices.
Financial conditions in emerging markets have tightened modestly since the fall, with notable differentiation based on country-specific factors. Emerging market equity indices have sold off over this period, in a context of rising trade tensions and higher risk aversion. Concerns about inflationary effects from earlier oil price increases and, in some cases, closing output gaps or passthrough from currency depreciation have led central banks in many emerging market economies (Chile, Indonesia, Mexico, Philippines, Russia, South Africa, Thailand) to raise policy rates since the fall. By contrast, central banks in China and India maintained policy rates on hold and acted to ease domestic funding conditions (by lowering reserve requirements for banks and providing liquidity to non-bank financial companies, respectively). As of early January, with some notable exceptions (e.g., Mexico, Pakistan), emerging market governments generally face lower domestic-currency long-term yields than in August-September. Foreign-currency sovereign credit spreads have edged up for most countries and risen substantially for some frontier markets.
Capital flows and exchange rates. With investors generally lowering exposure to riskier assets, emerging market economies experienced net capital outflows in the third quarter of 2018. As of early January, the US dollar remains broadly unchanged in real effective terms relative to September, the euro has weakened by about 2 percent amid slower growth and concerns about Italy, and the pound has depreciated about 2 percent as Brexit-related uncertainty increased. In contrast, the Japanese yen has appreciated by about 3 percent, on higher risk aversion. Several emerging market currencies—including the Turkish lira, the Argentine peso, the Brazilian real, the South African rand, the Indian rupee, and the Indonesian rupiah—have staged recoveries from their 2018 valuation lows last August-September.
Forecast Assumptions
The assumptions about tariffs, policy stances, and financial conditions underpinning the forecast are broadly similar to those in the last WEO.
The baseline forecast incorporates the US tariffs announced through September 2018 and retaliatory measures. For the United States, these include tariffs on solar panels, washing machines, aluminum, and steel announced in the first half of 2018; a 25 percent tariff on $50 billion worth of imports from China, and a 10 percent tariff on an additional $200 billion of imports from China, with the latter rising to 25 percent after the current 90-day “truce” ends on March 1, 2019. For China, the forecast incorporates tariffs ranging from 5 to 10 percent on $60 billion of imports from the United States.[1]
Average oil prices are projected at just below $60 per barrel in 2019 and 2020 (down from about $69 and $66, respectively, in the last WEO). Metals prices are expected to decrease 7.4 percent year-over-year in 2019 (a deeper decline than anticipated last October), and to remain roughly unchanged in 2020. Price forecasts for most major agricultural commodities have been revised modestly downwards.
Global Growth to Slow in 2019
Global growth in 2018 is estimated to be 3.7 percent, as it was last fall, but signs of a slowdown in the second half of 2018 have led to downward revisions for several economies.
Weakness in the second half of 2018 will carry over to coming quarters, with global growth projected to decline to 3.5 percent in 2019 before picking up slightly to 3.6 percent in 2020 (0.2 percentage point and 0.1 percentage point lower, respectively, than in the previous WEO). This growth pattern reflects a persistent decline in the growth rate of advanced economies from above-trend levels—occurring more rapidly than previously anticipated—together with a temporary decline in the growth rate for emerging market and developing economies in 2019, reflecting contractions in Argentina and Turkey, as well as the impact of trade actions on China and other Asian economies.
Specifically, growth in advanced economies is projected to slow from an estimated 2.3 percent in 2018 to 2.0 percent in 2019 and 1.7 percent in 2020. This estimated growth rate for 2018 and the projection for 2019 are 0.1 percentage point lower than in the October 2018 WEO, mostly due to downward revisions for the euro area.
Growth in the euro area is set to moderate from 1.8 percent in 2018 to 1.6 percent in 2019 (0.3 lower than projected last fall) and 1.7 percent in 2020. Growth rates have been marked down for many economies, notably Germany (due to soft private consumption, weak industrial production following the introduction of revised auto emission standards, and subdued foreign demand); Italy (due to weak domestic demand and higher borrowing costs as sovereign yields remain elevated); and France (due to the negative impact of street protests and industrial action).
There is substantial uncertainty around the baseline projection of about 1.5 percent growth in the United Kingdom in 2019-20. The unchanged projection relative to the October 2018 WEO reflects the offsetting negative effect of prolonged uncertainty about the Brexit outcome and the positive impact from fiscal stimulus announced in the 2019 budget. This baseline projection assumes that a Brexit deal is reached in 2019 and that the UK transitions gradually to the new regime. However, as of mid-January, the shape that Brexit will ultimately take remains highly uncertain.
The growth forecast for the United States also remains unchanged. Growth is expected to decline to 2.5 percent in 2019 and soften further to 1.8 percent in 2020 with the unwinding of fiscal stimulus and as the federal funds rate temporarily overshoots the neutral rate of interest. Nevertheless, the projected pace of expansion is above the US economy’s estimated potential growth rate in both years. Strong domestic demand growth will support rising imports and contribute to a widening of the US current account deficit.
Japan’s economy is set to grow by 1.1 percent in 2019 (0.2 percentage point higher than in the October WEO). This revision mainly reflects additional fiscal support to the economy this year, including measures to mitigate the effects of the planned consumption tax rate increase in October 2019. Growth is projected to moderate to 0.5 percent in 2020 (0.2 percentage point higher than in the October 2018 WEO) following the implementation of the mitigating measures.
For the emerging market and developing economy group, growth is expected to tick down to 4.5 percent in 2019 (from 4.6 percent in 2018), before improving to 4.9 percent in 2020. The projection for 2019 is 0.2 percentage point lower than in the October 2018 WEO.
Growth in emerging and developing Asia will dip from 6.5 percent in 2018 to 6.3 percent in 2019 and 6.4 percent in 2020. Despite fiscal stimulus that offsets some of the impact of higher US tariffs, China’s economy will slow due to the combined influence of needed financial regulatory tightening and trade tensions with the United States. India’s economy is poised to pick up in 2019, benefiting from lower oil prices and a slower pace of monetary tightening than previously expected, as inflation pressures ease.
Growth in emerging and developing Europe in 2019 is now expected to weaken more than previously anticipated, to 0.7 percent (from 3.8 percent in 2018) despite generally buoyant growth in Central and Eastern Europe, before recovering to 2.4 percent in 2020. The revisions (1.3 percentage point in 2019 and 0.4 percentage point in 2020) are due to a large projected contraction in 2019 and a slower recovery in 2020 in Turkey, amid policy tightening and adjustment to more restrictive external financing conditions.
In Latin America, growth is projected to recover over the next two years, from 1.1 percent in 2018 to 2.0 percent in 2019 and 2.5 percent in 2020 (0.2 percentage point weaker for both years than previously expected). The revisions are due to a downgrade in Mexico’s growth prospects in 2019–20, reflecting lower private investment, and an even more severe contraction in Venezuela than previously anticipated. The downgrades are only partially offset by an upward revision to the 2019 forecast for Brazil, where the gradual recovery from the 2015–16 recession is expected to continue. Argentina’s economy will contract in 2019 as tighter policies aimed at reducing imbalances slow domestic demand, before returning to growth in 2020.
Growth in the Middle East, North Africa, Afghanistan, and Pakistan region is expected to remain subdued at 2.4 percent in 2019 before recovering to about 3 percent in 2020. Multiple factors weigh on the region’s outlook, including weak oil output growth, which offsets an expected pickup in non-oil activity (Saudi Arabia); tightening financing conditions (Pakistan); US sanctions (Iran); and, across several economies, geopolitical tensions.
In sub-Saharan Africa, growth is expected to pick up from 2.9 percent in 2018 to 3.5 percent in 2019, and 3.6 percent in 2020. For both years the projection is 0.3 percentage point lower than last October’s projection, as softening oil prices have caused downward revisions for Angola and Nigeria. The headline numbers for the region mask significant variation in performance, with over one-third of sub-Saharan economies expected to grow above 5 percent in 2019–20.
Activity in the Commonwealth of Independent States is projected to expand by about 2¼ percent in 2019–20, slightly lower than projected in the October 2018 WEO due to the drag on Russia’s growth prospects from the weaker near-term oil-price outlook.
Risks to the Outlook
Key sources of risk to the global outlook are the outcome of trade negotiations and the direction financial conditions will take in months ahead. If countries resolve their differences without raising distortive trade barriers further and market sentiment recovers, then improved confidence and easier financial conditions could reinforce each other to lift growth above the baseline forecast. However, the balance of risks remains skewed to the downside, as in the October WEO.
Trade tensions. The November 30 signing of the US-Mexico-Canada free trade agreement (USMCA) to replace NAFTA, the December 1 US-China announcement of a 90-day “truce” on tariff increases, and the announced reduction in Chinese tariffs on US car imports are welcome steps toward de-escalating trade frictions. Final outcomes remain, however, subject to a possibly difficult negotiation process in the case of the US-China dispute and domestic ratification processes for the USMCA. Thus, global trade, investment, and output remain under threat from policy uncertainty, as well as from other ongoing trade tensions. Failure to resolve differences and a resulting increase in tariff barriers would lead to higher costs of imported intermediate and capital goods and higher final goods prices for consumers. Beyond these direct impacts, higher trade policy uncertainty and concerns over escalation and retaliation would lower business investment, disrupt supply chains, and slow productivity growth. The resulting depressed outlook for corporate profitability could dent financial market sentiment and further dampen growth (Scenario Box 1, October 2018 WEO).
Financial market sentiment. Escalating trade tensions, together with concerns about Italian fiscal policy, worries regarding several emerging markets, and, toward the end of the year, about a US government shutdown, contributed to equity price declines during the second half of 2018. A range of catalyzing events in key systemic economies could spark a broader deterioration in investor sentiment and a sudden, sharp repricing of assets amid elevated debt burdens. Global growth would likely fall short of the baseline projection if any such events were to materialize and trigger a generalized risk-off episode:
Italian spreads have narrowed from their October–November peaks but remain high. A protracted period of elevated yields would put further stress on Italian banks, weigh on economic activity, and worsen debt dynamics. Other Europe-specific factors that could give rise to broader risk aversion include the rising possibility of a disruptive, no-deal Brexit with negative cross-border spillovers and increased euro-skepticism affecting European parliamentary election outcomes.
A second source of systemic financial stability risk is a deeper-than-envisaged slowdown in China, with negative implications for trading partners and global commodity prices. China’s economy slowed in 2018 mainly due to financial regulatory tightening to rein in shadow banking activity and off-budget local government investment, and as a result of the widening trade dispute with the United States, which intensified the slowdown toward the end of the year. Further deceleration is projected for 2019. The authorities have responded to the slowdown by limiting their financial regulatory tightening, injecting liquidity through cuts in bank reserve requirements, and applying fiscal stimulus, by resuming public investment. Nevertheless, activity may fall short of expectations, especially if trade tensions fail to ease. As seen in 2015–16, concerns about the health of China’s economy can trigger abrupt, wide-reaching sell-offs in financial and commodity markets that place its trading partners, commodity exporters, and other emerging markets under pressure.
Beyond the possibility of escalating trade tensions and a broader turn in financial market sentiment, other factors adding downside risk to global investment and growth include uncertainty about the policy agenda of new administrations, a protracted US federal government shutdown, as well as geopolitical tensions in the Middle East and East Asia. Risks of a somewhat slower-moving nature include pervasive effects of climate change and ongoing declines in trust of established institutions and political parties.
Policy Priorities
With momentum past its peak, risks to global growth skewed to the downside, and policy space limited in many countries, multilateral and domestic policies urgently need to focus on preventing additional deceleration and strengthening resilience. A shared priority is to raise medium-term growth prospects while enhancing economic inclusion.
Multilateral cooperation. Building on the recent favorable developments noted above, policymakers should cooperate to address sources of dissatisfaction with the rules-based trading system, reduce trade costs, and resolve disagreements without raising tariff and non-tariff barriers. Failure to do so would further destabilize a slowing global economy. Beyond trade, fostering closer cooperation on a range of issues would help broaden the gains from global economic integration, including: financial regulatory reforms; international taxation and minimizing cross-border avenues for tax evasion; reducing corruption; and strengthening the global financial safety net to reduce the need for countries to self-insure against external shocks. An overarching challenge for the global community is mitigating and adapting to climate change to lower the likelihood of devastating humanitarian and economic effects from extremes in high temperatures, precipitation, and drought (Chapter 3, October 2017 WEO).[2] In a growing and ever more complex world economy featuring new and bigger risks, adequate IMF resources will continue to be a key stabilizing factor in global capital markets.
Domestic policies. The policy priorities across advanced economies, emerging markets, and low-income developing countries remain broadly the same as discussed in the October 2018 WEO.
Across advanced economies, above-trend growth is set to moderate to its modest potential (in some cases, earlier than previously anticipated). All countries should emphasize measures that boost productivity, raise labor force participation, particularly of women and, in some cases, youth, and ensure adequate social insurance, including for those vulnerable to structural transformation. Monetary policy should ensure inflation expectations remain anchored, while fiscal policy should build buffers where needed to replenish limited policy space for combating downturns.
Emerging market and developing economies have been tested by difficult external conditions over the past few months amid trade tensions, rising US interest rates, dollar appreciation, capital outflows, and volatile oil prices. In some economies, addressing high private debt burdens and balance-sheet currency and maturity mismatches will require strengthening macroprudential frameworks. Exchange rate flexibility can complement these policies by helping to buffer external shocks. Where inflation expectations are well anchored, monetary policy can provide support to domestic activity as needed (Chapter 3, October 2018 WEO). Fiscal policy should ensure debt ratios remain sustainable under the more challenging external financial conditions. Improving the targeting of subsidies and rationalizing recurrent expenditures can help preserve capital outlays needed to boost potential growth and social spending to enhance inclusion. For low-income developing countries, concerted efforts in these areas would also help diversify production structures (a pressing imperative for commodity-dependent economies), and their progress toward the UN Sustainable Development Goals.
[1] Scenario Box 1 of the October 2018 WEO estimates possible impacts of further increases in trade barriers, including via worsening business confidence and market sentiment.
[2] The Intergovernmental Panel on Climate Change (IPCC) reported in October that, at current rates of increase, average surface temperatures could reach 1.5°C above pre-industrial levels between 2030 and 2052.
UK Guidance: Trading with the EU if there’s no Brexit deal
Delivering the deal negotiated with the EU remains the government’s top priority. This has not changed.
However, the government must prepare for every eventuality, including a no deal scenario. For 2 years, the government has been implementing a significant programme of work to ensure that the UK is prepared to leave the EU on 29 March 2019.
It has always been the case that as we get nearer to that date, preparations for a no deal scenario would have to be accelerated. We must ensure plans are in place should they need to be relied upon.
In the summer, the government published a series of 106 technical notices setting out information to allow businesses and citizens to understand what they would need to do in a no deal scenario so they can make informed plans and preparations.
This technical notice offers guidance for continued planning in the event of no deal.
Also included is an overarching framing notice explaining the government’s approach to preparing the UK for this outcome in order to minimise disruption and ensure a smooth and orderly exit.
We are working with the devolved administrations on technical notices and we will continue to do so as plans develop.
Purpose
The purpose of this notice is to inform businesses of the implications for the trade in goods between the UK and EU countries and the actions they may want to now consider taking to mitigate the potential impacts in the event that the UK leaves the EU on 29 March 2019 with no agreement in place.
While the UK government is confident that it will agree a deal, as a responsible government it will continue to prepare for all scenarios, including if the UK leaves the EU on 29 March 2019 without a deal.
This is contingency planning for a scenario that the UK government does not expect to happen, but people should be reassured that the government is taking a responsible approach.
At the heart of government’s approach to preparing for a ‘no deal’ scenario is a commitment to prioritise stability for citizens, consumers and business. This is equally true in our approach to customs as elsewhere. We will continue to apply highly automated, risk based and intelligence targeted customs controls when the UK leaves the EU. As they do today, HM Revenue and Customs (HMRC) will work closely with industry to ensure its interventions are conducted in a way which minimises delays and additional burdens for legitimate trade, while robustly ensuring compliance. The approach of continuity does not mean that everything will stay the same, but the priority is maximising stability at the point of departure through the government’s action.
Businesses should consider how a ‘no deal’ scenario could affect them, and may want to begin taking steps to mitigate against such a risk. This technical notice provides further details to support early planning on customs and excise to help businesses understand the potential impacts, and the UK government will provide further details, including specific actions that businesses should take, in due course.
In summary, actions businesses can take now to prepare include the following:
Understand what the likely changes to customs and excise procedures will be to their businesses in light of this technical notice
take account of the volume of their trade with the EU and any potential supply chain impacts such as engaging with the other businesses in the supply chain to ensure that the necessary Planning is taking place at all levels
Businesses should consider the impact on their role in supply chains with EU partners. In the event that the UK and the EU does not have a Free Trade Agreement (FTA) in place in a ‘no deal’ scenario, trade with the EU will be on non-preferential, World Trade Organisation terms. This means that Most Favoured Nation (MFN) tariffs and non-preferential rules of origin would apply to consignments between the UK and EU. Further information on preferential trade under the UK’s existing trade agreements will be captured in the ‘Trade Agreement Continuity’ technical notice
If necessary, put steps in place to renegotiate commercial terms to reflect any changes in customs and excise procedures, and any new tariffs that may apply to UK-EU trade, and familiarise themselves with the key processes of importing and exporting outside of the EU
Consider how they will submit customs declarations for EU trade in a ‘no deal’ scenario, including whether they should engage the services of a customs broker, freight forwarder or logistics provider to help, or alternatively secure the appropriate software and authorisations
register to get EU Exit updates from HMRC
Before 29 March 2019
Businesses can currently move goods freely between EU member states. For customs, this means that businesses trading with the rest of EU do not have to make any customs import or export declarations, and their trade with the EU is not subject to import duty.
Certain goods are subject to excise duty. This is a tax charged on the importation and manufacture of alcohol, tobacco and oils. These goods are currently free to move between the UK and the rest of the EU with excise duty suspended.
What would happen to customs and excise procedures in a 29 March 2019 ‘no deal’ scenario?
If the UK left the EU on 29 March 2019 without a deal there would be immediate changes to the procedures that apply to businesses trading with the EU. It would mean that the free circulation of goods between the UK and EU would cease.
For businesses trading with the EU, the impacts would include:
businesses having to apply the same customs and excise rules to goods moving between the UK and the EU as currently apply in cases where goods move between the UK and a country outside of the EU (customs duty may also become due on imports from the EU – see the separate ‘Classifying your goods in the UK Trade Tariff if there’s a no Brexit deal’ technical notice). This means customs declarations would be needed when goods enter the UK (an import declaration), or when they leave the UK (an export declaration). Separate safety and security declarations would also need to be made by the carrier of the goods (this is usually the haulier, airline or shipping line, depending on the mode of transport used to import or export goods). More detail is provided below
the EU applying customs and excise rules to goods it receives from the UK, in the same way it does for goods it receives from outside of the EU. This means that the EU would require customs declarations on goods coming from, or going to, the UK, as well as requiring safety and security declarations
for movements of excise goods, the Excise Movement Control System (EMCS) would no longer be used to control suspended movements between the EU and the UK. However, EMCS would continue to be used to control the movement of duty suspended excise goods within the UK, including movements to and from UK ports, airports and the Channel tunnel. This will mean that immediately on Importation to the UK, businesses moving excise goods within the EU, including in duty suspension, will have to place those goods into UK excise duty suspension, otherwise duty will become payable
What businesses trading with the EU need to know
This section describes the implications for businesses importing from, or exporting to, the EU, and for UK carriers, for example haulage firms who are transporting the goods.
This technical notice takes each of these groups in turn.
Businesses importing from the EU in a 29 March 2019 ‘no deal’ scenario
After the UK leaves the EU, in the event of a ‘no deal’ scenario, businesses importing goods from the EU will be required to follow customs procedures in the same way that they currently do when importing goods from a country outside the EU. This means that for goods entering the UK from the EU an import declaration will be required, customs checks may be carried out and any customs duties must be paid.
Before importing goods from the EU, a business will need to:
Register for an UK Economic Operator Registration and Identification (EORI) number. Businesses do not need to do anything now. There will be further information available later in the year.
For those businesses that sign up for the EU Email updates, they will be contacted when this service becomes available
Ensure their contracts and International Terms and Conditions of Service (INCOTERMS) reflect that they are now an importer
Consider how they will submit import declarations, including whether to engage a customs broker, freight forwarder or logistics provider (businesses that want to do this themselves will need to acquire the appropriate software and secure the necessary authorisations from HMRC). Engaging a customs broker or acquiring the appropriate software and authorisations form HMRC will come at a cost
Decide the correct classification and value of their goods and enter this on the customs declaration. To help classify the goods correctly, the following may be useful:
HMRC publishes tariff information and guidance alongside the list of commodity codes needed to classify goods together with all the tariff rates, and measures
When importing goods from the EU, a business will need to:
Have a valid EORI number
Make sure that their carrier has submitted an Entry Summary Declaration at the appropriate time (see section 3)
Submit an import declaration to HMRC using their software, or get their customs broker, freight forwarder or logistics provider to do this for them
Pay Value Added Tax (VAT) and import duties including excise duty on excise goods unless the goods are entered into duty suspension (for example a customs or excise warehouse – a financial security will be required to cover the duty liability of the goods whilst they are being moved to the warehouse). Import VAT may also be due and more information regarding paying import VAT can be found in the ‘VAT for businesses if there’s no Brexit deal’ technical notice
Once excise goods leave a customs suspensive arrangement, they may be immediately entered into an excise duty suspension regime. A business will need to declare the goods on EMCS for onward movement via a Registered Consignor. Further information on how to do this can be found in Public Notice 197.
Businesses may also need to apply for an import licence or provide supporting documentation to import specific types of goods into the UK, or to meet the conditions of the relevant customs import procedure. Find out more about importing and licencing requirements – see also other technical notices covering importing goods.
Get more information about VAT for UK businesses importing goods from the EU if there’s no Brexit deal.
Businesses exporting to the EU in a 29 March 2019 ‘no deal’ scenario
After the UK leaves the EU, in the event of a ‘no deal’ scenario, businesses exporting goods to the EU will be required to follow customs procedures in the same way that they currently do when exporting goods to a non-EU country.
Before exporting goods to the EU, a business will need to:
register for an UK EORI number. You do not need to take action now but you will want to familiarise yourself with this process
ensure their contracts and International Terms and Conditions of Service (INCOTERMS) reflect that they are now an exporter
consider how they will submit export declarations, including whether to engage a customs broker, freight forwarder or logistics provider (businesses that want to do this themselves will need to acquire the appropriate software and secure the necessary authorisations from HMRC). Engaging a customs broker or acquiring the appropriate software and authorisations from HMRC will come at a cost.
When exporting goods to the EU, a business will need to:
have a valid EORI number
submit an export declaration to HMRC using their software or on-line, or get their customs broker, freight forwarder, or logistics provider to do this for them. The export declaration may need to be lodged in advance so that permission to export is granted before the goods leave the UK (the export declaration also counts as an Exit Summary Declaration – see section 3)
businesses may also need to apply for an export licence or provide supporting documentation to export specific types of goods from the UK, or to meet the conditions of the relevant customs export procedure.
When exporting duty suspended excise goods to the EU, a business will need to continue to use EMCS to record the duty suspended movement from a UK warehouse or premises to the port of export. Find out more about how to move, store and trade duty-suspended and duty-paid excise goods.
Get more information about VAT for UK businesses exporting goods to the EU if there’s no Brexit deal.
Carriers moving goods between the UK and the EU – Safety and Security Declarations
After the UK leaves the EU, in the event of a ‘no deal’ scenario carriers (for example hauliers, and train, vessel or aircraft operators) will need to make a Safety and Security Declaration for goods moving between the UK and EU. There are two types of Safety and Security Declarations: an Exit Summary Declaration (EXS) and an Entry Summary Declaration (ENS).
A carrier is generally required to submit an EXS to the customs authority of the country from which the consignment is being exported. For consignments exported from the UK the EXS generally forms part of the Export Declaration (a customs declaration).
A carrier is required to submit an ENS to the customs authority of the country that the consignment is entering.
Get more information about ENS declarations.
Mitigations businesses may consider in a March 2019 ‘no deal’ scenario
Businesses should now consider the impacts on them in a ‘no deal’ scenario, which would mean a requirement to apply the same customs and excise rules to goods traded with the EU that apply for goods traded outside of the EU, including the requirement to submit customs declarations. Businesses should consider whether it is appropriate for them to acquire software and/or engage a customs broker, freight forwarder or logistics provider to support them with these new requirements.
Businesses may want to consider whether using customs procedures would be beneficial. These allow businesses to delay or relieve the payment of customs duty for goods they import into the EU until goods are ready to be released into free circulation. A customs broker, freight forwarder or logistics provider can advise in the event of a ‘no deal’ scenario whether one of these procedures would be suitable for your business. Customs procedures include the following:
Customs warehousing: this allows businesses to store goods with duty or import VAT payments suspended. Once goods leave the warehouse, duty must be paid unless the business is re-exporting, or moving goods to another customs procedure. The warehouse must be authorised by HMRC
Inward processing: this allows businesses to import goods from non-EU countries for work or modification in the EU. Once this has been completed, any customs duty and VAT due must be paid, unless goods are re-exported or moved to another customs procedure, or released to free circulation temporary admission: this allows business to temporarily import and or/export goods such as samples, professional equipment or items for auction, exhibition or demonstration into the UK or EU. As long as the goods are not modified or altered while they are within the EU, the business will not have to pay duty or import VAT authorised use: this allows a reduced or zero rate of customs duty on some goods when used for specific purposes and within a set time period.
For excise duty purposes, goods are not regarded as imported if they are immediately placed under one of these customs procedures. Businesses need to pay excise duty when these goods are released for free circulation, unless they are immediately placed in excise duty suspension.
As part of considering the potential impacts, businesses should take account of the volume of their trade with the EU and any potential supply chain impacts.
Businesses should now begin to look at the guidance for importing and exporting outside of the EU to familiarise themselves with the key processes. The UK government will provide further information on action to take to prepare for this scenario over the coming months.
As part of the government’s own preparations, the UK has applied to re-join to the Common Transit Convention (CTC) when it leaves the EU. The CTC facilitates cross border movements of goods between contracting parties to the Convention, by enabling any charges due on those goods to be paid only in their country of destination. The negotiations on the UK’s membership of the CTC are ongoing.
The UK government is committed to deliver a functioning customs, VAT and excise system that enables trade to flow, revenues to be collected and for the UK to have a secure border following the UK’s exit from the EU.
Businesses in Northern Ireland importing and exporting to Ireland
The UK government is clear that in a ‘no deal’ scenario we must respect our unique relationship with Ireland, with whom we share a land border and who are co-signatories of the Belfast Agreement. The UK government has consistently placed upholding the Agreement and its successors at the heart of our approach. We recognise the basis it has provided for the deep economic and social cooperation on the island of Ireland.
It is the responsibility of the UK government to continue preparations for the full range of potential outcomes, including ‘no deal’. In such a scenario, the UK would stand ready to engage constructively to meet our commitments and act in the best interests of the people of Northern Ireland, recognising the very significant challenges that the lack of a UK-EU legal agreement would pose in this unique and highly sensitive context. This would include engagement on arrangements for land border trade. We will provide more information in due course.
The Irish government have indicated they would need to discuss arrangements in the event of no deal with the European Commission and EU member states. We would recommend that, if you trade across the land border, you should consider whether you will need advice from the Irish government about preparations you need to make.
More information
The steps and obligations businesses will need to take to continue to trade with the EU if the UK leaves without a deal are broadly the same as those that apply to businesses that trade with countries outside of the EU. Get more information on customs procedures, excise rules and VAT for:
importing from non-EU countries
exporting goods outside the EU
Further information and instructions specifically tailored to cover the actions that businesses would need to take in a ‘no deal’ scenario will be published in the coming months.
This notice is meant for guidance only. You should consider whether you need separate professional advice before making specific preparations.
It is part of the government’s ongoing programme of planning for all possible outcomes. We expect to negotiate a successful deal with the EU.
Norway, Iceland and Liechtenstein are party to the Agreement on the European Economic Area and participate in other EU arrangements. As such, in many areas, these countries adopt EU rules. Where this is the case, these technical notices may also apply to them, and EEA businesses and citizens should consider whether they need to take any steps to prepare for a ‘no deal’ scenario.
Right Management to Expand its Presence in the U.S. and Canada to Provide Anywhere Access for Clients and Candidates
MILWAUKEE, — Right Management, the career and talent development expert within ManpowerGroup (NYSE: MAN), today announces it will significantly increase its presence in the U.S and Canada in 2019 and invest in new digital tools. Right Management will increase the number of locations where it hosts clients and individuals including flexible workspaces, offices and pop-up locations and enhance its digital offerings to enable on-demand access to its talent management, career development and outplacement tools. New hub locations in key cities will host clients in contemporary workspaces that curate the best of ManpowerGroup’s workforce technology so clients can experience the latest high-tech innovations for talent development, management, assessment and outplacement.
“We know individuals and clients want to meet us in locations and spaces that are most convenient to them,” said Ian Symes Executive Vice President Right Management Europe and North America. “With that in mind, we are changing the way we do business in the U.S and Canada – investing in new high-tech workspaces and expanding our portfolio of digital tools with anywhere access. We know this model works – this is the latest phase in our global transformation, which begun three years ago. With this approach, we can meet our clients and candidates wherever they want to be, showcase our industry-leading technology, and enable our consultants to deliver the expert coaching we know is valuable to employers and employees alike. I’m delighted Right Management’s expanded presence, combined with our digital platforms and new digital event series for clients, will bring true “anywhere access” to even more businesses and individuals across the U.S and Canada.”
This is the next step in Right Management’s global transformation, which began in Europe to deliver a personalized yet high-tech experience for clients and candidates. The European flagship location opened in London in 2016 and welcomes over 5000 visitors a year.
Right Management’s expert coaching and in-person workforce development consultancy will be strengthened by new U.S. and Canadian locations and technology enabled offerings including the RightEverywhere® executive career portal – a customizable platform for leaders in transition, ManpowerGroup’s Digital Room, which assesses digital fluency, hosted by the company’s newest addition, Zara the avatar, and E•series Executive Transition Services, the latest addition to Right Management’s suite of offerings to help organizations develop transformation ready leadership teams. Employers and executives will also benefit from industry leading assessment capabilities including the DigiQuotient which helps leaders assess readiness to lead in the Digital Age based on Industrial and Organizational Psychology, the scientific study of human behavior in the workplace.
For more information about Right Management’s innovative technology and increased presence in North America visit https://www.right.com/northamerica2019.
About Right Management
Right Management is the global career and talent development expert within ManpowerGroup®. We help organizations become more agile, attractive and innovative by creating a culture of career management and learning that nurtures future talent, motivates and engages people, and provides individuals with opportunities to increase their value throughout their careers. We improve time to value through our expertise in organizational effectiveness, career management and individual development. Our approach is centered on the fact that organizations thrive when individuals are successful in their careers. We’ve spent the last 35+ years identifying workforce challenges and developing innovative solutions, enabling our globally informed methods to be time-tested across more than 50 countries. For more information about Right Management, visit: www.right.com.
About ManpowerGroup
ManpowerGroup® (NYSE: MAN), the leading global workforce solutions company, helps organizations transform in a fast-changing world of work by sourcing, assessing, developing and managing the talent that enables them to win. We develop innovative solutions for hundreds of thousands of organizations every year, providing them with skilled talent while finding meaningful, sustainable employment for millions of people across a wide range of industries and skills. Our expert family of brands – Manpower®, Experis®, Right Management® and ManpowerGroup® Solutions – creates substantially more value for candidates and clients across 80 countries and territories and has done so for 70 years. In 2018, ManpowerGroup was named one of the World’s Most Ethical Companies for the ninth year and one of Fortune’s Most Admired Companies for the sixteenth year, confirming our position as the most trusted and admired brand in the industry. See how ManpowerGroup is powering the future of work: www.manpowergroup.com
U.S. Secretary of Labor Acosta on December 312,000 Jobs Added
WASHINGTON, DC – U.S. Secretary of Labor Alexander Acosta today issued the following statement regarding the December 2018 Employment Situation report:
“With more than 5,000,000 jobs added since the 2016 election, the American economy surpassed 150,000,000 jobs for the first time ever.
“This month’s strong jobs report exceeded expectations, with 312,000 jobs added in December and, adding upward revisions from October and November, saw a total of 370,000 jobs added to the economy. Significant job gains were widespread including the construction, manufacturing, retail trade, education and health services and leisure and hospitality sectors.
“The labor force added 419,000 individuals and saw a 0.2% increase to 63.1%. Labor force participation for women 25-54 was particularly strong, rising by 0.3%, returning to 2009 levels.
“Average hourly earnings rose by 3.2% over the past 12 months and this is the third straight month that the year-over-year wage gains exceeded 3%. Prior to October 2018, the last time average hourly wage gains exceeded 3% was April 2009.
“As more people moved into the labor force, the unemployment rate moved up to 3.9%. More individuals moving into the labor force is welcomed news as job creators look to fill seven million open jobs.
“This closes a very strong 2018. Positive news was widespread: 2.6 million new jobs created in the past twelve months, America’s average wage earnings are on the rise, 8 months of unemployment below 4%, and series low unemployment rates this year for African-Americans, Asian-Americans, Hispanic-Americans, and those without a high school degree.
“While job growth remains strong, it is important that policymakers continue to foster an environment that promotes job creation and wage growth. This Administration will keep working to grow our economy and create family-sustaining careers for America’s workers.”
U.S. Hiring Intentions at 12 Year High as Demand for Workers is Set to Grow in 2019
MILWAUKEE, — The competition for skilled talent is set to rise in the first quarter of 2019 as employers across the U.S. are reporting the strongest hiring intentions in 12 years, according to the latest ManpowerGroup (NYSE: MAN) Employment Outlook Survey.* More than 12,500 U.S. employers report double-digit Outlooks across all four regions indicating continued employer optimism.
All 13 industry sectors forecast optimistic hiring plans with the strongest hiring Outlook in Transportation & Utilities as consumer expectations for on-demand delivery grows. Hiring intentions remain robust in Leisure & Hospitality (+27%) with more Americans spending on travel and tourism indicative of strong consumer confidence in a healthy economy. Professional & Business Services has the third strongest Outlook (+25%), driving the need for a breadth of workers from insurance to information technology.
“Increased employer optimism tells us employers have jobs to fill, yet we know they are struggling to find the talent they need from production line workers to IT professionals,” said Becky Frankiewicz, President of ManpowerGroup North America. “With so many U.S. organizations set to hire in an already tight labor market, skilled workers can call the shots. For some workers benefits including childcare facilities, free transportation, or the offer of certification and career progression are key. We’ve seen large organizations increase wages and add new perks and benefits like unlimited paid-time-off to compete for talent. Employers can increase their offer, yet ultimately there is a finite supply of skilled talent, unless we’re investing in development and giving employees the chance to upskill, move up and earn more. That’s why we’re working with companies from transportation to high-tech IT to implement accelerated upskilling programs to help people learn skills to do the jobs open today and those created tomorrow.”
The South has the highest regional Outlook (+21%) as manufacturing continues to grow with a +22% Outlook in Nondurable Goods Manufacturing, the highest since 2005. Hiring prospects in the Northeast (+20%) are the strongest in more than 12 years driven in part by an uptick in Wholesale & Retail Trade (+24%) and Durable Goods Manufacturing (21%). Employers in the West (+20%) and Midwest (+20%) report sustained hiring momentum in Q1 2019.
View complete Q1 2019 survey results for the U.S: ManpowerGroup.US/MEOS.
Region
Q1 2019
Quarter-over-Quarter Variation
Year-over-Year Variation
West
20%
0%
+1%
Midwest
20%
+2%
0%
South
21%
+1%
+3%
Northeast
20%
+2%
+3%
U.S. Hiring Plans by Regions, Industry Sectors and Metro Areas/States
Nationwide, employers in all 13 industry sectors expect to add staff in Q1 2019. The strongest Outlooks are reported in Transportation & Utilities (+28%), Leisure & Hospitality (+27%), Professional & Business Services (+25%), Mining (+24%) Wholesale & Retail Trade (+24%), Construction (+23%), Non-Durable Goods Manufacturing (+20%) and Durable Goods Manufacturing (+19%).
Employers in all four regions in the U.S. plan to add staff in Q1 2019. Employers in the South (+21%) and Northeast (+20%) report a three percent increase year-over year and in the West the Outlook is up a percentage point (+20%). The Outlook in the Midwest (+20%) is up 2 percentage points quarter-over-quarter.
Employers in Delaware (+30%), Idaho (+28%), Hawaii (+27%), New Hampshire (+27%) and Florida (+26%) report the strongest Outlooks. Of the 100 largest metropolitan statistical areas, the strongest job prospects are expected in Daytona Beach, FL (+37%), Cape Coral, FL (+32%), Tampa, FL (+31%), Jacksonville, FL (+29%) and Raleigh, NC (+29%).
Complete results for the ManpowerGroup Employment Outlook Survey are available for download at ManpowerGroup.US/MEOS. The Q2 2019 survey will be released March 12, 2019.
*The Net Employment Outlook is derived by taking the percentage of employers anticipating an increase in hiring activity and subtracting from this the percentage of employers expecting a decrease in hiring activity.
About ManpowerGroup ManpowerGroup® (NYSE: MAN), the leading global workforce solutions company, helps organizations transform in a fast-changing world of work by sourcing, assessing, developing and managing the talent that enables them to win. We develop innovative solutions for hundreds of thousands of organizations every year, providing them with skilled talent while finding meaningful, sustainable employment for millions of people across a wide range of industries and skills. Our expert family of brands – Manpower®, Experis®, Right Management® and ManpowerGroup® Solutions – creates substantially more value for candidates and clients across 80 countries and territories and has done so for 70 years. In 2018, ManpowerGroup was named one of the World’s Most Ethical Companies for the ninth year and one of Fortune’s Most Admired Companies for the sixteenth year, confirming our position as the most trusted and admired brand in the industry. See how ManpowerGroup is powering the future of work: www.manpowergroup.com
Generations Global – World Economic Forum Looks to Add New Voices to Shape 2019 Annual Meeting
Geneva, Switzerland – The World Economic Forum announced today the Co-Chairs of its Annual Meeting, which will take place on 22-25 January 2019 in Davos-Klosters, Switzerland.
Over 3,000 global leaders from politics, government, civil society, academia, the arts and media will convene under the theme Globalization 4.0: Shaping a Global Architecture in the Age of the Fourth Industrial Revolution, where participants will focus on defining new models for building sustainable and inclusive societies in a plurilateral world.
“Globalization as we know it may have peaked, but global integration will continue. It is fueled by the technologies of the Fourth Industrial Revolution and the urgent need to address challenges such as climate change and biodiversity, job loss through automation and a threatening breakdown in global collaboration. All those changes will particularly affect the next generation. For this reason, it is essential to integrate their voice prominently in building a new sustainable and inclusive global architecture,” said Klaus Schwab, Founder and Executive Chairman of the World Economic Forum.
Every year, Annual Meeting Co-Chairs take a principal role in help shape the discussion. This year’s Co-Chairs are:
– Basima Abdulrahman, Founder, KESK Green Building Consulting, Iraq, and World Economic Forum Global Shaper (Ebril Hub), is a structural engineer by training who has built a business constructing sustainable buildings. Through the Forum’s Global Shapers network in her country, she also works to promote social cohesion in fragile communities.
– Juan David Aristizábal, Co-Founder, Todos por la Educación, Colombia, and World Economic Forum Global Shaper (Bogota Hub), is an author, broadcaster and social entrepreneur. He leads a grassroots movement through Los Zúper, a platform that prepares youth and educators with leadership skills for the 21st century.
– Noura Berrouba, Member of the Governing Body, European Youth Parliament, Sweden, and World Economic Forum Global Shaper (Stockholm Hub), is a member of the Governing Body of the European Youth Parliament and National Council of Swedish Youth Organizations. She has dedicated her life to advocating open-minded, tolerant and active citizenship.
– Jim Yong Kim, President, World Bank Group, Washington DC, has been a leading force for change in driving inclusive growth and developing human capital with the goal of ending extreme poverty by 2030.
– Julia Luscombe, Director of Strategic Initiatives, Feeding America, USA, and World Economic Forum Global Shaper (Chicago Hub), is helping to end hunger in the US through her work building a charitable food system for the future.
– Mohammed Hassan Mohamud, Zonal Chairman, Kakuma Refugee Camp, Kenya, and World Economic Forum Global Shaper (Kakuma Hub), who spent the last 20 years living in displacement, is dedicated to championing the rights of refugees and conflict prevention.
– Satya Nadella, Chief Executive Officer, Microsoft Corp: CEO of Microsoft since 2014, Nadella defines his mission and that of the company he leads as empowering every person and every organization on the planet to achieve more.
– Akira Sakano, Co-Founder and Communication Director, RDND, Japan, and World Economic Forum Global Shaper (Osaka Hub), is helping create the world’s first zero-waste city in Japan.
Extending the discussion about the new global architecture, the Forum is inviting the public to share their thoughts and perspectives via the Globalization 4.0 video campaign, which will feature short videos (60-90 seconds long) that answer one or more of the following questions:
1) How do we save the planet without killing economic growth?
2) Can you be a patriot and a global citizen?
3) What should work look like in the future?
4) How do we make sure technology makes life better not worse?
5) How do we create a fairer economy?
6) How do we get countries working together better?
The best responses will be featured on www.weforum.org/globalization4 starting January 2019, in the lead-up to the Annual Meeting 2019. During the meeting, the Forum will also record selected constituents in Davos addressing the same key questions. Best submitted videos will be featured on the Forum’s Instagram, Twitter, Facebook, and LinkedIn channels. The hashtag for the project is #globalization4.
The World Economic Forum will work with UNICEF and Generation Unlimited to address the critical challenges young people face in education, skills and empowerment. The collaboration aims to accelerate progress at global, regional and local levels, through Global Shaper hubs in 162 countries, more than 190 UNICEF offices and the growing partner network of Generation Unlimited.
The World Economic Forum’s Global Shapers Community is a network of more than 7,000 young people in 370 cities working together to address the world’s biggest challenges. The community provides a platform to amplify the voices of young people and equips them with the tools to self-organize and create lasting local impact (read some of their blogs here)..
Christine Lagarde On G20: Step Up to Boost Inclusive Growth
As G20 leaders gather in Argentina, the global economy faces a critical juncture. We have had a good stretch of solid growth by historical standards, but now we are facing a period where significant risks are materializing and darker clouds are looming.
As the most recent economic data have been disappointing, we must not allow ourselves to be held back. Rather, we must be ambitious, including by implementing a multilayered set of reforms which could potentially add an additional 4 percent boost to the GDP of the G20 countries.
Success here depends on us acting swiftly—and acting together.
Signs of moderating growth
The IMF’s World Economic Outlook, published in October, forecast global growth of 3.7 percent for 2018 and 2019. These estimates were 0.2 percentage points below our July estimates—a downgrade due largely to rising external and financial pressures on emerging markets and a tangible increase in trade tensions.
Implementing a multilayered set of reforms could potentially add a 4 percent boost to the GDP of the G20 countries.
Recent data suggest that these headwinds could have slowed momentum even more than we had expected. For example, third-quarter growth has been surprisingly low in emerging market economies such as China, and in the euro area. A no-deal Brexit could further dent confidence.
Over the medium term, particularly in advanced economies, we see growth moderating because of adverse demographics and slow productivity. This includes the United States, once the recent fiscal stimulus ends.
In addition, in too many countries, excessive inequality is hurting many people—and it also risks undermining public support for reforms that would enhance productivity.
What can be done to address these challenges? Let me highlight three priorities.
First, strengthen our defenses
Policymakers can start by creating more fiscal room for maneuver, so that they have the resources needed to increase support to the economy should growth weaken significantly. This implies undertaking meaningful fiscal consolidation now—especially in high-debt countries such as Italy and in several emerging economies.
In terms of monetary policy, the ongoing process of normalization of interest rates in many advanced economies should continue to follow a gradual, well-communicated, and data-dependent path. This is not only in their own interest, but also helps to avoid unnecessary turbulence for others.
The good news is that monetary policy normalization indicates relatively strong growth in the advanced economies. In recent months, however, monetary tightening—combined with rising trade tensions—has heightened external pressures for some emerging economies. How can they respond?
Those with well-anchored inflation targets should rely on exchange rate flexibility to mitigate external pressures. Where these pressures threaten to be disruptive, capital flow management measures could also play a role as part of a broader policy package.
Second, teamwork is the winning tactic
We know that rising trade barriers are ultimately self-defeating for all involved. Thus, it is imperative that all countries steer clear of new trade barriers, while reversing recent tariffs.
We have a unique opportunity to improve the global trade system. IMF research suggests that liberalizing trade in services could add about ½ percent, or $350 billion, to G20 GDP in the long run.
At the same time, concerted actions by individual countries can strengthen their own economies, reduce global imbalances, and boost the global economy. Some examples: Germany could use its fiscal space to strengthen its growth potential, by increasing investment and incentivizing labor force participation; the US could help by lowering its fiscal deficit; and China could help by pressing ahead with its economic rebalancing.
After a decade of relatively easy financial conditions, many countries also need to address record levels of debt—altogether $182 trillion globally by IMF estimates. In addition, increasing the transparency of the scale and terms of borrowing, especially in low-income countries, is an imperative.
More broadly, financial sector risks require action, including by avoiding a rollback of post-crisis advances in financial sector regulation.
Third, pick up the pace
The theme of Argentina’s G20 presidency—Building Consensus for Fair and Sustainable Development—is a critical priority. Yet at present, progress is too slow. How can it be accelerated?
Most G20 advanced economies could benefit from relaxing product market restrictions to spur innovation and lower prices. Easing access to professional services would be especially important, for example in Japan and many euro area countries. Increasing support for research would be vital in Canada, Germany, and the United Kingdom, among others.
Most G20 emerging market countries, too, would benefit from product and labor market reforms. Economies such as Brazil, China, India, and Russia would gain by moving away from distortionary taxes.
And virtually everywhere, raising women’s participation in the workforce would not only boost growth, but also help to make societies fairer and more inclusive.
These are just some of the measures which, if jointly implemented, could by our calculations increase G20 GDP by 4 percent.
Conclusion
During the ten years since the first G20 Leaders’ Summit, the G20’s efforts have been crucial in helping the global economy recover.
Yet darker clouds are now returning to the horizon.
Tackling this challenge means implementing policies that make sense both nationally and internationally. It also means strengthening the global financial safety net, with a well-equipped and well-resourced IMF at its center, to ensure that we can play our role in helping countries prevent and deal with future crises.
As the G20 meets in Buenos Aires, let us act swiftly and act together
Azevêdo Urges G20 Leaders’ Commitment To Improve The Functioning Of The WTO
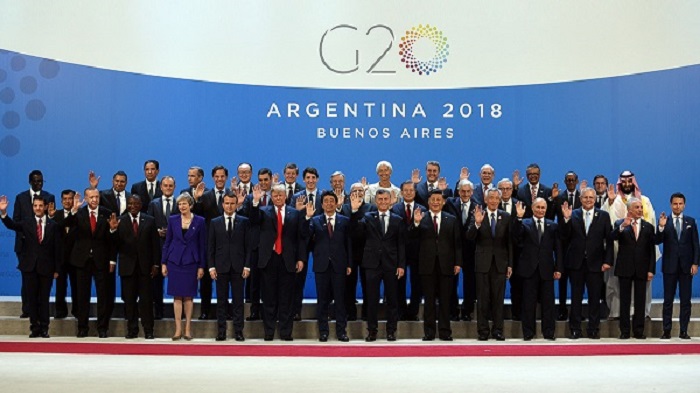
Director-General Roberto Azevêdo strongly welcomed the communiqué agreed by G20 leaders at the summit in Buenos Aires, Argentina, on 1 December and said he would work with all WTO members to improve and strengthen the trading system. The Director-General also called on the leaders to act urgently to address the blockage in the WTO dispute settlement system.
Speaking in Buenos Aires at the close of the summit, the Director-General said:
“This has been a very productive G20 summit. I have heard firm support for trade and the WTO throughout my meetings with leaders in Buenos Aires and heard a range of ideas about strengthening our work. This is reflected in the leaders’ declaration, which I strongly welcome. The declaration represents a very important moment in tackling the current challenges in global trade. With this statement, the leaders underline the vital importance of trade and of the multilateral trading system in supporting growth, productivity, innovation, job creation and development. They call for improvements and “necessary reforms” to the functioning of the WTO to ensure that it can continue playing this essential role. I will work with WTO members to take this forward in the interests of all.”
“International trade and investment are important engines of growth, productivity, innovation, job creation and development. We recognize the contribution that the multilateral trading system has made to that end. The system is currently falling short of its objectives and there is room for improvement. We therefore support the necessary reform of the WTO to improve its functioning. We will review progress at our next Summit.”
On Trend Hiring: Research Reveals How Retailers Can Attract In-Demand Talent This Holiday Season
MILWAUKEE, As the holiday season fast approaches, employers in the retail sector need to work even harder to attract workers to meet growing consumer demand. In online retail or in-store, U.S. retail candidates value flexibility and place greater emphasis on brand reputation when choosing where to work, according to a new report from ManpowerGroup Solutions (NYSE: MAN) and the Retail Industry Leaders Association (RILA), the trade association for America’s retailers.
“Retail jobseekers are looking to fit a job into their lives and not their lives into their job,” said Melissa Hassett, Vice President of Client Delivery at ManpowerGroup Solutions. “Sales representatives are in the top five hardest roles to fill in the U.S. That means that in this competitive labor market, employers should understand that candidates are consumers too and need to work hard to attract people using a strong employee value proposition. What’s bringing retail workers into the role is the need for flexibility, an attractive benefits package and opportunities to upskill and earn more.”
The report, What Retail Employers Need to Know about Candidate Preferences, provides retail insights and practical tips on how to attract and retain workers. ManpowerGroup Solutions surveyed nearly 2,500 retail workers across the U.S. to understand how they want to work. Benefits from healthcare to travel subsidies, childcare or gym memberships matter more for retail workers – more than half (52%) say benefits are a top factor when making career decisions, up 5% from the last year. Ninety-two percent of retail workers rank employer-employee trust as the number one factor in deciding where to work, versus 83% across all industries.
“As one of the nation’s largest employers providing careers and opportunities to over 42 million Americans, the retail industry must continue to adopt hiring practices that offer employees the benefits and flexibility they crave,” said Evan Armstrong, Vice President of Government Affairs at Retail Industry Leaders Association (RILA). “Whether it’s Starbucks offering hourly workers paid-time off to care for sick family members to Amazon offering full tuition reimbursement, we see employers turning to new strategies to recruit, retain and develop a workforce in an omnichannel marketplace. We are pleased to partner with ManpowerGroup Solutions to help the industry cultivate a workforce in a tech-forward industry by prioritizing the preferences of job-seekers.”
To learn more about ManpowerGroup Solutions’ candidate preferences research and practical strategies to close the retail talent gap, download What Retail Employers Need to Know about Candidate Preferences, visit https://www.manpowergroup.us/campaigns/manpowergroup-solutions/retail/.
About ManpowerGroup Solutions
ManpowerGroup Solutions provides clients with outsourcing services related to human resources functions, primarily in the areas of large-scale recruiting and workforce-intensive initiatives that are outcome-based, thereby sharing in the risk and reward with our clients. Our solutions offerings include TAPFIN-Managed Service Provider, Strategic Workforce Consulting, Borderless Talent Solutions, Talent Based Outsourcing and Recruitment Process Outsourcing, where we are one of the largest providers of permanent and contingent recruitment in the world. ManpowerGroup Solutions is part of the ManpowerGroup family of companies, which also includes Manpower, Experis, and Right Management. More information at www.manpowergroupsolutions.com.
About ManpowerGroup
ManpowerGroup® (NYSE: MAN), the leading global workforce solutions company, helps organizations transform in a fast-changing world of work by sourcing, assessing, developing and managing the talent that enables them to win. We develop innovative solutions for hundreds of thousands of organizations every year, providing them with skilled talent while finding meaningful, sustainable employment for millions of people across a wide range of industries and skills. Our expert family of brands – Manpower®, Experis®, Right Management® and ManpowerGroup® Solutions – creates substantially more value for candidates and clients across 80 countries and territories and has done so for 70 years. In 2018, ManpowerGroup was named one of the World’s Most Ethical Companies for the ninth year and one of Fortune’s Most Admired Companies for the sixteenth year, confirming our position as the most trusted and admired brand in the industry. See how ManpowerGroup is powering the future of work: www.manpowergroup.com
About RILA
The Retail Industry Leaders Association (RILA) is the trade association for the world’s largest and most innovative retail companies. RILA members include more than 200 retailers, product manufacturers, and service suppliers, which together account for more than $1.5 trillion in annual sales, millions of American jobs, and more than 100,000 stores, manufacturing facilities, and distribution centers domestically and abroad.
IMF: Botswana Mining a New Growth Model
The IMF’s latest assessment of Botswana’s economy says that while the near- and medium-term prospects look reasonably good, a much less favorable scenario looms if the development model is not revamped and certain reforms are not implemented. Enrique Gelbard, who heads the IMF team for Botswana, sat down with Country Focus to discuss the report’s findings.
Botswana is commonly seen as a model economy in Africa. Why the success? Any lessons for other countries?
Botswana’s performance has been remarkable in the half century since independence, transforming itself from a severely impoverished nation to a high-middle-income country and achieving substantial reductions in poverty and rapid improvements in living standards. Its recipe for success has three main ingredients.
First, it has managed its diamond revenues in a prudent and transparent manner (Botswana has been consistently ranked among the top 50 countries in terms of governance in the world), contributing to sizable savings that can be used to stabilize the economy in case of a downturn and save for investments and future generations.
Second, it has allocated a good share of government spending to health, education, social assistance, and investment in public infrastructure.
Third, it built a tradition of democratic values which helped maintain political and social stability. That said, the country faces two important challenges: how to reduce its unemployment rate of nearly 18 percent and how to diversify its economic structure, considering that diamonds account for 90 percent of export receipts.
Talking about diversification, the report emphasizes the need to “mine a new growth model” for Botswana. Could you tell us more about that?
Yes, diamond production may only extend for another 30 years and mining activities do not create enough jobs. In addition, Botswana has a small domestic market, which constrains the long-term success of a development strategy based on diamonds and the expansion of the public sector. So, in the period ahead it will be essential to foster the development of the private sector and diversify exports.
To this end, Botswana needs to improve its business environment and the quality of the labor force to attract more private investors.
The first goal requires the removal of bureaucratic regulations and impediments, the adoption of policies that promote competition, and the privatization of inefficient state-owned companies.
The second goal requires improved policies to build skills and work ethic in the labor force together with removal of restrictions on visas and permits for skilled workers.
Beyond mining, Botswana also has significant potential in tourism given its natural wonders (such as the Okavango delta), and in the production of high-quality, free-range beef with quota and duty-free access to the EU market (the country has more cattle than people).
As the private sector develops, the public sector will need to focus on improving its efficiency and enabling financial development. For instance, the public sector can play a significant role in prioritizing public projects that have economy-wide benefits. Such projects include air transportation and internet connectivity. Reforms that encourage higher levels of lending by banks and access to credit will also support growth.
Finally, the merger of several inefficient government-funded enterprises known as parastatals would also improve efficiency.
The report looks at the impact of social spending and taxes in Botswana. Have policies helped reduce poverty and inequality?
The analysis shows that Botswana’s fiscal policy did contribute to lower poverty and inequality, mostly through social spending. More specifically, high spending in primary and secondary education has had an equalizing effect on income distribution. Still, we found that there is room to further reduce inequality through better targeting of social programs and education bursaries, as well as increasing the rate and coverage of property taxes.
Lastly, streamlining VAT exemptions could generate additional resources to fund future social spending and public investment, although the most vulnerable should be compensated with cash transfers.
To conclude, one of the key messages of the report is to accelerate implementation of reforms. What should be done to overcome implementation challenges?
Botswana’s medium-term economic prospects depend on the successful implementation of key reforms, some of which have been part of the agenda for some time. Recent announcements by President Masisi of the government’s intentions to remove burdensome regulations, proceed with privatizations, and relax restrictions on permits and visas for foreign workers are encouraging.
To be successful, these and other reforms now need to move forward, which will include making clear who is responsible for their implementation, setting up a timetable, and ensuring accountability through high-level monitoring.
Machines Will Do More Tasks Than Humans by 2025 but Robot Revolution Will Still Create 58 Million Net New Jobs in Next Five Years
Tianjin, People’s Republic of China, 17 September 2018 – The world is going through a workplace revolution that will bring a seismic shift in the way humans work alongside machines and algorithms, according to new research by the World Economic Forum. By 2025 more than half of all current workplace tasks will be performed by machines as opposed to 29% today. Such a transformation will have a profound effect on the global labour force, however in terms of overall numbers of new jobs the outlook is positive, with 133 million new jobs expected to be created by 2022 compared to 75 million that will be displaced.
The research, published today in The Future of Jobs 2018, is an attempt to understand the potential of new technologies to disrupt and create jobs. It is also seeks to provide guidance on how to improve the quality and productivity of the current work being done by humans and how to prepare people for emerging roles.
Based on a survey of chief human resources officers and top strategy executives from companies across 12 industries and 20 developed and emerging economies (which collectively account for 70% of global GDP), the report finds that 54% of employees of large companies would need significant re- and up-skilling in order to fully harness the growth opportunities offered by the Fourth Industrial Revolution. At the same time, just over half of the companies surveyed said they planned to reskill only those employees that are in key roles while only one third planned to reskill at-risk workers.
While nearly 50% of all companies expect their full-time workforce to shrink by 2022 as a result of automation, almost 40% expect to extend their workforce generally and more than a quarter expect automation to create new roles in their enterprise.
The report presents a vision of a future global workforce that provides grounds for both optimism and caution. Compared to a similar study by the Forum in 2016 to understand the impact of the Fourth Industrial Revolution on jobs, the outlook for job creation today is much more positive as businesses have a much greater understanding of the opportunities made available by technology. At the same time, the huge disruption automation will bring to the global labour force is almost certain to bring with it significant shifts in the quality, location, format and permanency of roles that will require close attention from leaders in the public and private sector.
“It is critical that business take an active role in supporting their existing workforces through reskilling and upskilling, that individuals take a proactive approach to their own lifelong learning, and that governments create an enabling environment to facilitate this workforce transformation. This is the key challenge of our time,” said Klaus Schwab, Founder and Executive Chairman of the World Economic Forum.
Among the set of roles set to experience increasing demand across all industries are data analysts and scientists, software and applications developers, and ecommerce and social media specialists, all of which roles that are significantly based on or enhanced by technology. Roles that leverage distinctly ‘human skills,’ such as sales and marketing professions, innovation managers and customer service workers, are also set to experience increasing demand. Jobs expected to become redundant include routine-based white-collar roles, such as data entry clerks, accounting and payroll clerks.
Jobs Outlook 2022
Within the set of companies surveyed, respondents predicted a decline of 984,000 jobs and a gain of 1.74 million jobs between now and 2022. Extrapolating these trends across those employed by large firms in the non-agricultural workforce of the 20 economies covered by the report suggests that 75 million jobs may be displaced by a shift in the division of labour between humans, machines and algorithms, while 133 million new roles may emerge that are more adapted to this new division of labour.
While we expect net positive job growth, there will be a significant shift in the quality, location, format and permanency of new roles. In fact, businesses are set to expand their use of contractors doing task-specialized work, engage workers in more flexible arrangements, utilize remote staffing, and modify the locations where their organization operates to ensure access to talent.
Workers will require new sets of skills as the division of labour between humans and machines continues to evolve. Surveyed companies report that today, 71% of total current task hours are performed by humans, compared to 29% by machines. By 2022, this average is expected to shift to 58% task hours performed by humans, 42% by machines.
Change Management Strategies
All industries expect to have sizeable skills gaps, with average skills instability of 42%, highlighting the scale of the challenge in preparing today’s workers for changes within their current roles and the emerging jobs of the future. Technology proficiency, such as technology design and programming, and distinctly human skills, such as creativity, critical thinking and persuasion, are among the competences that will be sharply increasing in importance.
“Companies need to complement their automation plans with comprehensive augmentation strategies. For businesses to remain dynamic, differentiated and competitive in an age of machines, they must in fact invest in their human capital. There is both a moral and economic imperative to do so. Without proactive approaches, businesses and workers may lose out on the economic potential of the Fourth Industrial Revolution,” said Saadia Zahidi, Head of the Centre for the New Economy and Society at the World Economic Forum.
An augmentation strategy takes into account the broader spectrum of value-creating activities that can be accomplished by workers, machines and algorithms in tandem. Fulfilling this potential will require workers to have the appropriate skills for the workplace of the future, and will require business and policymakers to lead complementary and coordinated efforts to invest in human capital.
Respondents reported three main strategies for coping with the challenges of the new world of work: hire wholly new permanent staff with the skills relevant to new technologies; automate work tasks completely; and retrain existing employees. A smaller but significant number of companies expect to allocate the work to specialist contractors, freelancers and temporary workers.
While large-scale, multistakeholder action will be needed to tackle existing and impending skills needs, 85% of companies reported that they plan to rely mainly on internal specialized departments within their organization to provide reskilling opportunities, compared to half expecting to work with public education institutions. Only 34% of the training to be delivered directly by employers is expected to result in an accreditation recognized outside of the company in question.These findings highlight both the future role of companies as learning organizations and the range of untapped reskilling and upskilling collaboration opportunities.
The Future of Jobs Across Industries
The future of jobs is not singular, and disparate impacts will be felt across industries depending on initial starting conditions, skills availability, technology adoption and adaptability of the workforce.
While there is an overall net positive outlook on the future job market, the balance of workforce expansion and contraction looks different across industries. The level of displacement is expected to vary considerably. For example the share of companies projecting jobs losses in the mining and metals, consumer and information and technology industries is higher than companies in professional services. Declining roles and skills in one industry are growing in other industries. These findings point to potential opportunities for coordinated job transition strategies across industries.
All industries expect to have sizable skills gaps, with the Aviation, Travel & Tourism industry projected to have the highest reskilling needs in the 2018-2022 timeframe. Skills gaps are also a particular concern in the Information & Communication Technology, Financial Services & Investors, and Mining & Metals industries. The broad mobility sector is least likely to look to reskill their current employees, while business leaders in the Global Health & Healthcare, Chemistry, Advanced Materials & Biotechnology sectors are most likely to retrain their workers.
“Knowing which occupations are growing and declining globally is a starting place for policymakers, educators, and employers to start conversations on how to transition the global workforce to the jobs and skills of tomorrow,” says Allen Blue, Co-founder of LinkedIn. “To help people connect to economic opportunity on the individual level, it’s important to map and understand today’s labor market dynamics at scale.”
If managed well, a combination of reskilling and the augmentation of a range of tasks today can create the opportunity for new, higher productivity growth. For example, administering and physical tasks are projected to be significantly replaced by mechanized labour, leaving room for humans to focus on higher productivity tasks.
The Future of Jobs Across Regions
The impact of automation on jobs will also vary across countries and regions, especially as global companies consider a number of strategic factors in choosing where to locate specific job roles and economic activities. 74% of companies cited the availability of skilled local talent as their foremost consideration in determining job locations. More than half of companies surveyed for this report expect that by 2022, they would consider adjusting the composition of their value chains in response to the adoption of new technologies, and just under half expect to target new talent by modifying the location of their operations. These findings point to the potential impact of workforce management strategies on the geography of jobs across the global economy.
The report finds variation among the demand for roles across regions. Region-specific roles expected to be in growing demand include Financial and Investment Advisors in East Asia and the Pacific and Western Europe; Assembly and Factory Workers in Latin America and the Caribbean, Middle East and North Africa, South Asia and Sub-Saharan Africa; and Electrotechnology Engineers in North America. Across all countries and regions, employers expect that significant reskilling will be needed by a large share of the global workforce over the 2018-2022 period. Remaining competitive in a global context and taking advantage of emerging job creation opportunities will require a well-skilled local workforce bolstered by national lifelong learning ecosystems.
Shaping a Human-Centered Future of Jobs
Harnessing the transformative potential of the Fourth Industrial Revolution will require coordinated efforts among stakeholders in all industries and regions to formulate a comprehensive workforce augmentation strategy ready to meet the challenges of this new era of change and innovation. Business, government and workers must proactively plan and implement a new vision for the global labour market.
For governments, there is an urgent need to address the impact of new technologies on labour markets through upgraded education systems aimed at raising both technical and soft skills among the future workforce; social policies aimed at supporting an ecosystem of lifelong learners; safety nets for managing the social impact of workforce transformations; and stimulating job creation taking into account local and global demand for emerging roles and skills. For industries, it will pay to support the upskilling of their current workforce toward new and higher-skilled roles as competition for skilled talent intensifies and becomes more costly over the coming years. Industries will also need to consider how these efforts may also apply to the gig, temporary and online workforces they increasingly plan to rely on. For workers, there is a need to take personal responsibility for their learning trajectory through the current transition and developing a higher degree of comfort with the concept of lifelong learning.
Methodology
The latest edition of the Future of Jobs Report aims to support individual workers, businesses, and policymakers understand the impact of automation on talent gaps, skills churn, job displacement and change management strategies for navigating the new world of work. The 2018 employer survey that formed the basis of the report gathered the views of business executives at the frontlines of the changing workforce, especially Chief Human Resource Officers, Chief Strategy Officers and Chief Executives. It covers over 300 global companies from a wide range of industry sectors. Survey responses represent more than 15 million employees, and 20 developed and emerging economies which collectively represent about 70% of global GDP. In addition to the aggregate analysis, the report contains 12 industry profiles and 29 country or regional profiles, providing detailed information for projections through to 2022. The Report also included a unique data contribution from LinkedIn, showing the key emerging and declining roles in the recent past across several industries and geographies.
Centre for the New Economy and Society
The World Economic Forum’s Centre for the New Economy and Society provides a platform for leaders to build transformative public-private partnerships and shape a future in which people are at the heart of economic and social progress. A significant portion of its work focuses on the future of jobs. The Centre is working across multiple industries to design sector-specific roadmaps to respond to the new opportunities and challenges of managing workforce disruptions. The Centre is also supporting developed and emerging economies in setting up public-private collaborations to close skills gaps and prepare for the future of work. Finally, the Centre acts as a test bed for early-stage work at the frontier of managing the future of work, ranging from the development of new principles for the gig economy to the adoption of common skills taxonomies across business and education.
Annual Meeting of the New Champions
The World Economic Forum’s 12th Annual Meeting of the New Champions is taking place on 18-20 September in Tianjin, People’s Republic of China. Convening under the theme, Shaping Innovative Societies in the Fourth Industrial Revolution, more than 2,000 business leaders, policy-makers and experts from over 80 countries will participate and explore more than 200 sessions over the three days of the meeting.
Oliver Cann, Public Engagement, World Economic Forum
IMF: No-deal Brexit Would Impact UK Economy
Despite strong policy frameworks and implementation, growth has moderated since the European Union referendum in June 2016. Uncertainty over the terms of the EU withdrawal has weighed on private sector activity. Above-target inflation following the sharp post-referendum sterling depreciation has slowed real income and consumption growth. Business investment has been lower than would be expected in the context of robust global growth and favorable financing conditions. The softening of domestic demand was partially offset by a higher contribution from net exports, supported by weaker sterling and strong external demand. Overall, growth fell to about 1¾ percent in 2016-17, moving the United Kingdom from the top to near the bottom of the G7 growth tables. The employment rate, however, continues to reach record highs.
The UK is set to exit the EU in March 2019 and aims to reach a broad agreement with the EU on their future relations by the end of 2018. Our projections assume timely agreement on a broad trade pact covering goods and some services, and a relatively smooth Brexit process thereafter. Growth is expected to remain moderate in the near term under this baseline, averaging about 1½ percent this year and next. With the economy operating at very low unemployment and household saving already at a very low rate, consumption growth will be broadly in line with subdued real income growth. Investment is also likely to remain constrained as long as Brexit uncertainty weighs on firms. A more disruptive departure from the EU could lead to a significantly worse outcome, especially if it were to occur without an implementation period. By contrast, an agreement featuring fewer impediments to trade than currently expected could buoy business and consumer confidence, leading to faster growth.
Brexit negotiations have yielded agreement in principle on a 21-month implementation period. If ratified, this would allow important additional time to prepare for the new relationship between the UK and EU. However, fundamental questions—such as the future economic relationship between the two and the closely-related question of the status of the land border with Ireland—remain unanswered. Resolving these issues is critical to avoid a “no deal” Brexit on WTO terms that would entail substantial costs for the UK economy—and to a lesser extent the EU economies—particularly if it were to occur in a disorderly fashion. While all likely Brexit outcomes will entail costs for the UK economy by departing from the frictionless single market that now prevails, an agreement that minimizes the introduction of new tariff and nontariff barriers would best protect growth and incomes in the UK and EU. Over time, new trade agreements with countries outside the EU could eventually pare some of these losses for the UK. However, such agreements are unlikely to bring sufficient benefits to offset the costs imposed by leaving the EU.
The UK government has taken a number of steps to prepare for the administrative and legislative changes that Brexit will require. The government has committed to act in several areas to provide continuity at the moment of departure from the EU. Parliament is in the process of transposing into UK law the legislative framework currently encompassed in EU laws, and the government has guaranteed EU program funding committed to projects in the UK before the end of 2020 and is working to ensure that the UK maintains access to critical items like medicines. A budgetary allocation of £3 billion has been established to help fund the costs of Brexit preparation, and thousands of civil servants have been hired to help shoulder the workload. Brexit preparations are a shared responsibility of the public and private sectors. The government has begun publishing technical notices setting out information to allow private stakeholders to understand what they would need to do in a “no deal” scenario, so they can make informed plans and preparations.
Nevertheless, the range of remaining issues to prepare for Brexit is daunting, underscoring the importance of securing an implementation period. The UK will have to bolster human, physical, and IT resources in customs and other services, and establish domestic agencies to replace EU ones. In addition, the government will need to renegotiate the hundreds of bilateral and multilateral international agreements to which it is now party via its EU membership. Many of the required tasks cannot be initiated until there is greater clarity on the future trade relationship with the EU or even until Brexit occurs. The massive scope of work that remains and the limited time before the UK exits the EU would likely leave preparations incomplete on departure day despite even the most determined efforts. This risks serious disruptions without an implementation period in place. Coordination and cooperation between the EU and UK on priority issues, such as ensuring air traffic continues to flow, would be to the benefit of both parties. Joint technical discussions between UK and EU experts could facilitate this process.
Beyond Brexit, the UK faces a range of other economic challenges. These include persistently lackluster productivity growth, large public debt, and the wide current account deficit. The UK’s sound macroeconomic framework, regulatory environment, and deep capital and flexible labor markets will be advantages in implementing reforms to address them.
Monetary and Fiscal Policies
After a cumulative 50 basis point increase in Bank Rate over the last 12 months, further withdrawal of monetary stimulus should await clear confirmation of a durable rise in domestic cost pressures. The inflationary impact of the post-referendum depreciation of sterling should continue to fade. At the same time, domestic inflation is likely to firm as the tight labor market pushes real wage growth above productivity growth. If excess demand pressures persist after domestic inflation has approached a level consistent with the 2-percent target, further gradual tightening of monetary policy would be warranted. However, policymakers should respond flexibly to data developments in an environment of greater-than-usual uncertainty. If negative surprises depress domestic demand, accommodative conditions should be maintained for longer. The scaling down of the Bank of England’s balance sheet should await the return of Bank Rate to a level from which it could be cut materially in the event of a demand slowdown, consistent with the Monetary Policy Committee’s current plans. Transparent and timely communication to guide market expectations continues to be essential.
Steady fiscal consolidation remains critical to comply with the government’s fiscal framework and to put debt firmly on a downward path. Fiscal consolidation over the last decade has substantially reduced deficits, but public debt remains relatively high from a cross-country perspective. Bringing the debt ratio down is important to create buffers that will allow the public finances to weather future shocks, as noted in the authorities’ welcome report on Managing Fiscal Risks . Accordingly, the recently-announced increase in public health spending should be financed from new revenue sources and/or offsetting spending cuts elsewhere in the budget. In the absence of offsetting measures, the margin against the cyclically adjusted deficit ceiling of 2 percent in 2020/21 would be significantly reduced, and the debt ratio would not decline in the medium term.
Brexit-related effects could exacerbate existing fiscal challenges. Each 1 percentage point decline of GDP leads to about a 0.4 percentage point increase in the budget deficit. Most analysts project output costs relative to a no Brexit scenario to be well above this. If Brexit disproportionately affects relatively tax-rich sectors like finance, the revenue impact could be even larger. Reduced migration will also have a negative budgetary impact, as EU migrants tend to be both younger and better skilled than average, making them net contributors to the fiscal accounts. These factors exceed any savings from lower net EU contributions and will come on top of longer-term budget pressures that pre-date Brexit.
As in many advanced economies, population aging is likely to put considerable pressure on the budget over the longer term. The Office for Budget Responsibility estimates that public spending on health care and pension benefits will increase by a cumulative four percentage points of GDP between 2023 and 2043. Opportunities for further efficiency gains in the NHS should be explored, and the elimination of the “triple lock” could lead to important savings over time on pensions. While the government should continue to seek the best value for money in public spending, after several years of primarily expenditure-based consolidation identifying further efficiency gains could become difficult. Absent a fundamental rethinking of the size and role of the public sector, revenue measures will therefore need to occupy a more prominent place in deficit reduction efforts going forward.
More broadly, tax reforms can reduce economic distortions and increase fiscal space. Scaling back preferential VAT rates would increase tax neutrality. Better aligning the tax treatment of employees and the self-employed would improve fairness and bring the tax system in line with evolving employment practices. Financial stability could be enhanced by reducing the tax code’s bias toward debt, for example by adopting a tax allowance for corporate equity. Rebalancing property taxation away from transactions and toward values would boost labor force mobility and encourage more efficient use of the housing stock.
Contingency Planning
Under a disorderly Brexit scenario, policies should seek to safeguard macroeconomic and financial stability. In the event of sharp declines in sterling and other asset prices, the Bank of England would need to ensure that the financial system has adequate liquidity. The implications of Brexit for monetary and fiscal policy are uncertain: the response will depend on the relative shifts of supply and demand, as well as the extent of sterling depreciation. The fiscal framework provides flexibility to support the economy, for example through bringing forward infrastructure spending. However, the space to respond could narrow if the shock were to significantly raise interest rates on public debt. Any easing of fiscal policy should therefore be temporary and embedded in a credible medium-term fiscal consolidation plan. A permanent shock to output would require an eventual adjustment of revenues or spending.
Financial Sector Policies
Bank balance sheets have continued to improve. Capital, leverage, and liquidity positions are strong. The countercyclical capital buffer requirement will increase to 1 percent in November, reflecting the Financial Policy Committee’s view that apart from Brexit-related risks the financial sector is operating in a standard risk environment. The Bank of England’s 2017 stress tests indicate that the major UK banks are all sufficiently well-capitalized to withstand simultaneous UK and global recessions, large falls in asset prices, and stressed misconduct costs. Banks subject to the ringfencing requirements are on track to meet the January 2019 deadline. With the recent adoption of the MiFID II framework, investor protection has been strengthened and transparency increased.
Without continued supervisory vigilance, relatively easy financing conditions could lead to increasing prudential risk. Household and corporate leverage have started to edge up, although they remain below pre-crisis levels. Total lending is growing broadly in line with GDP. However, consumer credit—the quality of which is more sensitive to income and interest rate shocks—continues to rise much faster than income, despite recent tightening of underwriting standards. Further policy action may be needed if high rates of growth persist, including additional increases in bank-specific capital buffers and steps to enhance the oversight of nonbank financial institutions. Other areas of potential vulnerability include the valuation of commercial real estate and to some extent housing. CRE prices remain high and have continued to rise after a short-lived dip following the EU referendum. The ratio of new mortgage loans at relatively high loan-to-income ratios has increased somewhat in the last two years, although the share of highly indebted households remains low. Supported by strong risk appetite in global markets, market-based corporate borrowing has expanded rapidly, with significant foreign investment in CRE and leveraged loans. The authorities’ effort to collect information on leverage outside the banking system and assess potential vulnerabilities is welcome. More broadly, the commitment of the FPC and Prudential Regulation Authority to continue to implement robust prudential standards that would maintain a level of financial sector resilience post-Brexit that is at least as great as that currently planned is commendable.
The UK’s current account deficit has narrowed, but it remains large in absolute terms and financing trends are a potential concern. Higher returns on UK-owned assets held abroad and higher revenues from net trade led to a narrowing of the current account deficit to 3.9 percent of GDP last year. This is a significant improvement over the deficits of around 5 percent of GDP that prevailed in recent years. However, the share of external financing that is short-term and therefore subject to financing risks—such as wholesale deposits in banks—has risen. Associated stability risks are limited by the strong capital and liquidity positions of UK banks, as well as the high credibility of the fiscal and monetary policy frameworks. Nevertheless, this trend should be monitored carefully, especially in an environment where rising US interest rates and concerns about the UK’s long-term growth potential may affect refinancing prospects. Continued fiscal consolidation should help further reduce the current account deficit over time.
The UK has taken a proactive approach to supporting the Brexit preparations of regulated financial institutions and mitigating financial stability risks. Potential risks include disruptions to the provision of financial services, shifts in asset prices and liquidity conditions, and a deterioration of balance sheets from macroeconomic shocks. The Bank of England has stated that its 2017 annual cyclical stress test suggests the major UK banks are sufficiently well-capitalized to withstand a range of macroeconomic risks that could be associated with Brexit. The UK government is focused on identifying and mitigating potential stability risks that could arise during the Brexit transition. For example, legislation is being prepared to create temporary permissions and recognition regimes to allow EEA financial services firms, funds, and central counterparties to continue their activities in the UK for a time-limited period after the UK has left the EU, providing a backstop in case a Brexit agreement is not ratified.
Regulatory and supervisory cooperation between UK and EU authorities will be crucial to maintaining the integrity of cross-border financial transactions . A technical working group, chaired by the heads of the Bank of England and the European Central Bank, has been established to discuss Brexit-related risk management. As suggested in the recent Euro Area FSAP, the EU and UK authorities should work together to ensure legal continuity in insurance and derivative contracts and proper data sharing to avoid cliff-edge effects, which could potentially be highly disruptive.
Structural Policies
Over the long run, UK living standards will predominantly depend on productivity growth. Productivity levels and growth in the UK lag those in peer economies, meaning that output growth has depended largely on increases in employment. The scope for substantial future employment gains is limited, as the unemployment rate is around historic lows and the rate of net immigration of workers from the EU is already falling. Therefore, economic performance will increasingly depend on the ability of firms to raise output per worker. Here, too, the implications of Brexit are largely negative: reduced migration will result in less efficient matching of jobs and workers, while a more closed UK economy will be less competitive and a less attractive environment for foreign direct investment.
Further sustained policy efforts are needed to support productivity and help reduce income inequality and regional disparities. Inequality has declined since the crisis, but remains high compared to other advanced economies, and intergenerational income mobility is low. At the regional level, disparities are large: the UK has some of the most productive regions in any advanced economy, but also some of the least productive. Several initiatives have been announced in recent years to improve infrastructure and human capital. The introduction of T-level qualifications and the apprenticeship levy aim to raise job-specific skills and to promote higher level technical skills and reduce regional disparities in skills provision. It will be important to monitor and evaluate the effectiveness of these programs once they have been in place for some time. A £31 billion National Productivity Investment Fund has been created, which targets investments in transport, housing, digital, and research and development. Infrastructure investment is targeted to increase by over 50 percent from 2012/13 to 2020/21, and the fiscal remit for the National Infrastructure Commission aims for sustained public infrastructure investment of 1 to 1.2 percent of GDP over the long-term. An expert review will examine competition challenges in the digital economy and recommend appropriate policy responses by early 2019.
Boosting economic opportunities for women would promote growth and equity. The female participation rate in the UK, at 74 percent, is already relatively high by advanced economy standards. Recent government initiatives have sought to increase it further by improving government support for childcare costs and doubling the free childcare available to 3- and 4-year-olds of eligible working parents. The government has also introduced free childcare for disadvantaged children aged 2. Nevertheless, fully closing the participation rate gap would boost output by around 5 to 6 percent in the long run. Policies to facilitate job sharing and compressed work schedules could be helpful in this regard. Efforts should also focus on measures to close the gender pay gap (which stands at 10 percent on average for full-time employees) and to increase representation of women in senior positions and in corporate boards, where they remain relatively few in number. Recently-enacted legislation requiring larger firms to make public data on gender pay gaps has helped focus attention on pay disparities.
Brexit will lead to important shifts in the structure of the UK economy and policies could play a role in facilitating the transition. Changes in the trade and migration regimes are likely to vary in effect across industries and regions. Government policies could help smooth the flow of workers both geographically and across economic sectors. In particular, the increased use of active labor market policies, including support for re-training such as the National Retraining Scheme, policies that promote entrepreneurship, higher investment in research and development, and reforms to promote housing supply and mobility could facilitate the transition and reduce the associated costs. Policies should seek to support workers and not particular jobs or sectors.
Corporate transparency has further strengthened. Measures to verify beneficial ownership information of UK companies in the People with Significant Control register continue to be developed and implemented. Financial institutions should be required to report discrepancies in the PSC register. The proposal for a register for foreign owners of UK real estate is also welcome and should include verification measures. The new Office for Professional Body Anti-Money Laundering Supervision is expected to improve consistency of professional body AML supervision in the accountancy and legal sectors, especially firms that provide trust and company services. Continued exchange of ownership information on companies and trusts among the UK authorities, Crown Dependencies, and British Overseas Territories is important.